
Market Participants Analysis dated 01.10.2026
KRVPrime — Daily Market Outlook
Key Market Signals — Data: 01 Oct 2026
NIFTY 50 22,421.95 ▼ -198.50 (-0.88%) | BANK NIFTY 54,450.75 ▼ -182.30 (-0.33%) | SENSEX 71,909.70 ▼ -570.59 (-0.79%) |
OVERALL PCR 0.78 ▼ -0.01 (-1.83%) PCR below 0.80 signals call-side dominance — market is leaning bearish with put writers partially retreating | INDIA VIX 14.46 ▲ +0.97 (+7.15%) VIX spike of +7.15% on a down-day confirms fear is rising — elevated uncertainty, option premium expensive | TOTAL OI CHANGE 45,207,208 ▲ +3,990,946 (+9.68%) Massive OI addition on a falling market confirms fresh short buildup — bears are adding conviction |
FUTURES OI 870,782 ▲ +40,074 (+4.82%) Futures OI expanding on a down-close points to fresh directional shorts being added | CALL OI CHANGE 11,520,976 ▲ +1,796,431 (+18.47%) Call OI surging +18.47% signals aggressive supply-side buildup — resistance being heavily written and bought | PUT OI CHANGE 8,953,136 ▲ +1,254,728 (+16.30%) Put OI also expanding sharply — hedging demand is rising but lagging call OI growth, keeping PCR depressed |
Participant-wise Key Points
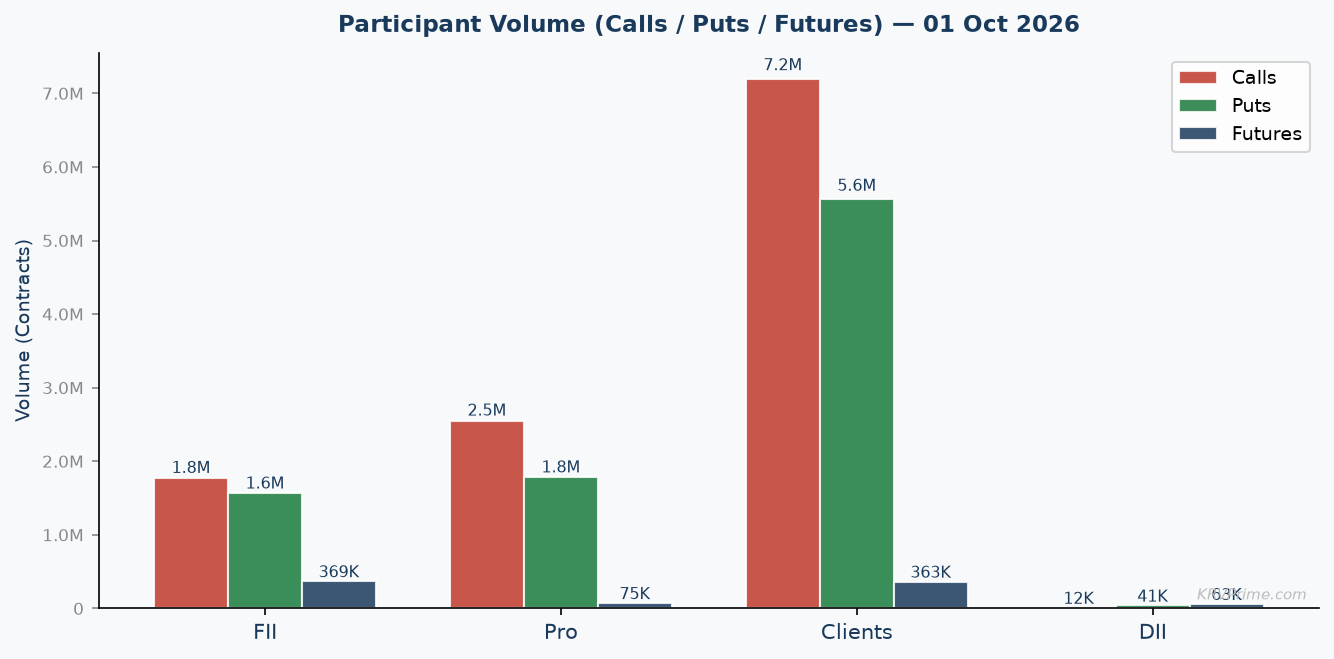
FII Strongly Bearish — Accelerating Dual-Leg Short Architecture
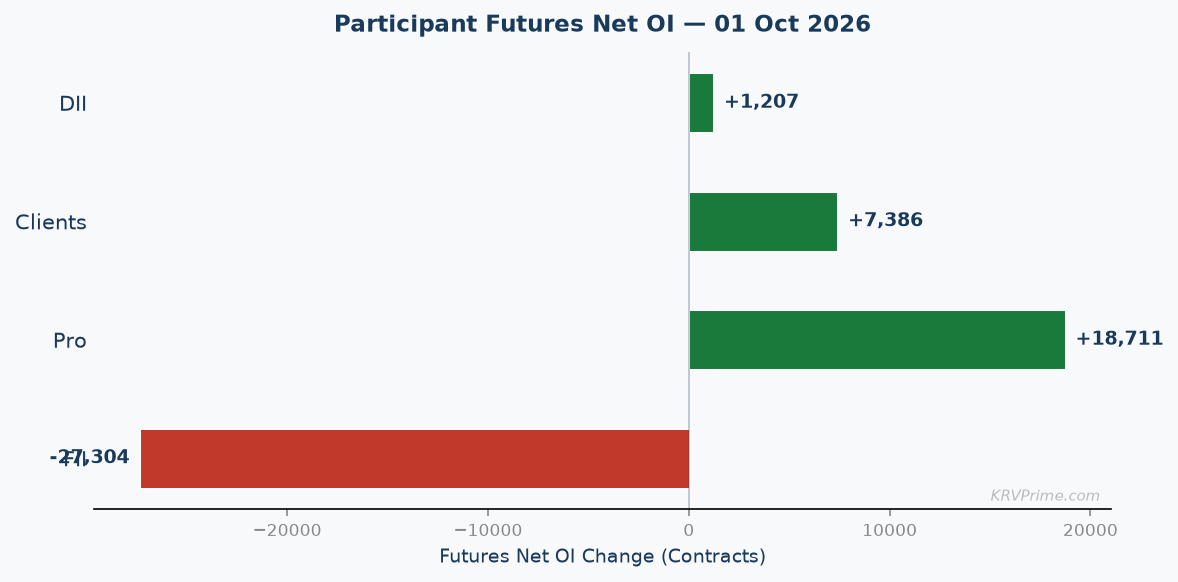
- Futures net deteriorated from -282,870 to -310,174 (net change -27,304 contracts), marking a significant deepening of FII's already dominant directional short book. The Long side added a modest 211 contracts (prev 29,394 → today 29,605, [Long Buildup - Low Vol]), while the Short side surged by 27,515 contracts (prev 312,264 → today 339,779, [Short Buildup - Low Vol]). The Low Vol tag on the short buildup is particularly important — it means this aggressive addition of 27,515 new short contracts was executed on below-average volume, suggesting FIIs did not need high conviction urgency to push their thesis; rather, they added shorts quietly without triggering a panic cover in the opposite camp. The gross short-to-long ratio now stands at a staggering 11.48:1 (339,779 shorts versus 29,605 longs), which is not a hedging posture — this is an outright directional conviction short of rare magnitude, and today's addition accelerates a trend that has been building for multiple sessions.
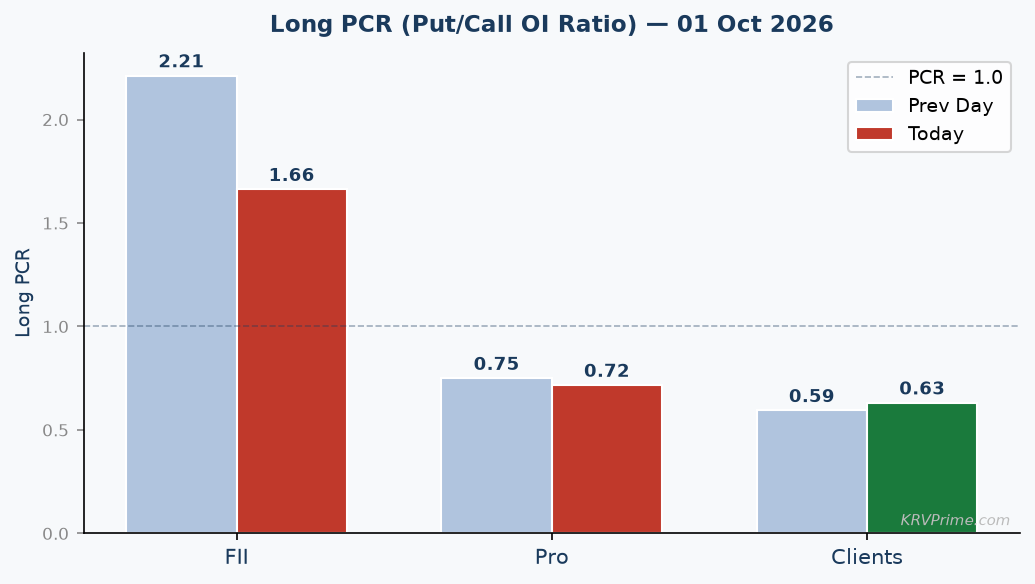
- Long PCR fell sharply from 2.21 to 1.66 (change -24.85%) and Short PCR rose modestly from 0.39 to 0.41 (change +4.18%). The Long PCR of 1.66 means FIIs hold 66% more put longs than call longs — even after falling from 2.21, this remains a deeply defensive posture indicating either systematic equity portfolio protection or a pure bearish expression through options. The sharp -24.85% drop in Long PCR is the key signal today: it was driven by FIIs adding 203,970 new call longs alongside 82,725 put longs, meaning they expanded their call long book proportionately faster than their put long book — this is a nuanced point worth flagging as it suggests some speculative upside lottery buying embedded within a predominantly bearish options book. The Short PCR inching up from 0.39 to 0.41 tells us FIIs are now writing slightly more puts relative to calls on the short side, a marginal shift toward range-income behavior but not enough to reverse the overwhelmingly bearish architecture.
- Call OI net improved from -465,583 to -431,465 (net change +34,118) — Long 670,483 [Long Buildup - Low Vol] versus Short 1,101,948 [Short Buildup - Low Vol]. Put OI net held near flat at +666,578 (prev +668,125, net change -1,547) — Long 1,114,773 [Long Buildup - Avg Vol] versus Short 448,195 [Short Buildup - Avg Vol]. The call side reveals a specific structural message: FIIs added 203,970 call longs and 169,852 call shorts simultaneously — gross call activity was massive on both sides, but the net call position improved by +34,118, meaning they bought more calls than they sold. This partial net call-long shift is the only bearish-contradicting data point in FII's entire positioning, but in isolation it is dwarfed by the -310,174 futures net and +666,578 put net long — the dominant architecture remains a synthetic short + protective collar where futures shorts are buttressed by net long puts, and the call longs may represent cheap hedges against a short-squeeze rather than a bullish directional bet.
- Synthesis — FII Dual-Leg Accelerating Short Conviction: FIIs present the clearest and most internally consistent bearish thesis across all four participants today. A futures net of -310,174 (deepened by -27,304 today), a Long PCR of 1.66 (even after falling -24.85%), a net put long of +666,578, and a still net-short call book of -431,465 collectively describe a synthetic short with embedded tail-risk protection — FIIs are simultaneously short the index via futures, protected on the put side, and only modestly hedged on the call side. The quiet execution under Low Vol tags on both futures legs suggests this is a deliberate, planned addition rather than a reactive panic trade. The only internal nuance — the partial improvement in call net OI from -465,583 to -431,465 — indicates a thin hedging layer against a short-squeeze scenario, but it does not alter the dominant bearish posture. Compared to the previous session where net futures stood at -282,870, today's -310,174 shows FIIs are not simply holding — they are actively pressing their short book on every weak close, and the VIX spike of +7.15% to 14.46 today aligns perfectly with their playbook of building short positions while fear-premium rises.
- Forward trigger: If FII futures net worsens further through -325,000 contracts in tomorrow's data, it will confirm a third consecutive session of accelerated short addition and the probability of a momentum breakdown toward the 22,000 Nifty PE support zone escalates materially. Conversely, if FII futures net begins to recover above -300,000 (net short reduction of ~10,000 contracts or more), that would be the first signal of a potential short-squeeze catalyst — watch this number closely before reading tomorrow's intraday tape. The critical PCR threshold to monitor is whether Overall PCR drops further below 0.75 (from today's 0.78), which alongside FII short addition would confirm the bears are in full control.
DII Mildly Bearish — Reducing Long Exposure and Unwinding Hedges
- Futures net improved marginally from +32,050 to +33,257 (net change +1,207 contracts), but the internal composition tells a more cautious story than the headline net suggests. The Long side shed -1,523 contracts (prev 49,642 → today 48,119, [Long Unwinding - Low Vol]) and the Short side simultaneously reduced by -2,730 contracts (prev 17,592 → today 14,862, [Short Covering - Low Vol]). Both legs carry Low Vol tags — meaning both the long unwinding and the short covering were executed with below-average volumes, suggesting this is routine portfolio trimming rather than a high-conviction directional flip. The gross long-to-short ratio stands at 3.24:1 (48,119 longs versus 14,862 shorts), maintaining DII's structurally long bias in futures, but the fact that they trimmed longs on a down-day rather than defended them is a mild signal of caution — they are not adding to long exposure into this weakness.
- DII does not have published Long PCR or Short PCR data for this session. However, the options OI changes provide a substitute directional read. The put long unwinding of -6,556 contracts (from 46,958 to 40,402) is the most telling signal — DIIs were reducing their put protection precisely on a day when Nifty fell -0.88% and VIX spiked +7.15%, which implies one of two things: either they believe the downside is limited and protection is no longer required at this level, or they are rolling put protection to lower strikes as the market has moved down to their target. The call short addition of +625 contracts (from 2,932 to 3,557, [Short Buildup - High Vol]) carries a High Vol confirmation tag — the only High Vol signal in DII's entire data set today — indicating this is a deliberate, high-conviction call-writing move, consistent with a range-cap or income strategy.
- Call OI net fell from +5,551 to +4,976 (net change -575) — Long 8,533 [Long Buildup - High Vol] versus Short 3,557 [Short Buildup - High Vol]. Put OI net collapsed from +46,658 to +39,526 (net change -7,132) — Long 40,402 [Long Unwinding - Low Vol] versus Short 876 [Short Buildup - Low Vol]. The most significant structural shift for DII today is the -7,132 reduction in net put OI, driven almost entirely by the unwinding of 6,556 put longs at Low Vol — DIIs are dismantling their hedging put book quietly. Simultaneously, the put short book more than tripled from 300 to 876 (a +192% increase), which, although small in absolute terms, signals DII is beginning to write puts — a net income/range strategy that implicitly bets the market will not fall significantly from current levels. The combination of reduced put longs and growing put shorts creates a structural reduction in bearish option protection — DII is becoming less hedged on the downside.
- Synthesis — DII Defensive Reduction with Range Income Overlay: DII's positioning today can be summarized as a controlled long-bias reduction — they are trimming futures longs at Low Vol, dismantling put-long hedges that are now partially in-the-money given the market decline, and selectively adding call shorts and put shorts to generate range income. This is NOT a bearish flip; their futures net remains solidly positive at +33,257 contracts, and they retain structural long bias in equities. However, compared to the FII picture, DII's directional confidence has clearly diminished today — the High Vol call short buildup is consistent with a view that Nifty will not reclaim meaningfully higher levels in the near term, and the put long unwinding at -6,556 on a down-day is a notable de-risking action. The internal contradiction worth noting is that they added +625 call shorts (High Vol = conviction) while also adding call longs (net call position fell only -575), suggesting they are simultaneously buying calls for gamma exposure while writing them for income — a classic market-maker-style strangle-reduction posture. DII today represents a cautious income harvester in a declining market, not an aggressive buyer of the dip.
- Forward trigger: If Nifty breaches and closes below the 22,000 PE support level (the dominant OI support from week and month combined), watch whether DII restores their put long book above 46,000 contracts — a re-addition of put longs above that threshold would signal they have re-engaged their hedging posture and believe further downside is probable. Conversely, if DII futures net expands above 40,000 with fresh long additions (High Vol tag), it would signal institutional domestic buyers stepping in to support the market, which would be a strongly contrarian bullish signal against FII's dominant short book.
Pro Cautiously Bullish — Aggressively Building Net Long Futures with Hedged Options
- Futures net surged from +8,394 to +27,105 (net change +18,711 contracts), representing the largest absolute net futures improvement of any participant today and a remarkable +223% improvement in net positioning. The Long side added 15,823 contracts (prev 35,278 → today 51,101, [Long Buildup - Avg Vol]) while the Short side simultaneously shed -2,888 contracts (prev 26,884 → today 23,996, [Short Covering - Low Vol]). The combination of Avg Vol on the long buildup and Low Vol on the short covering tells a specific story: Pro desks built their long book with moderate-conviction volume while covering shorts quietly — this is a deliberate net long tilt, not just mechanical arbitrage rolling. The gross long-to-short ratio has improved dramatically from 1.31:1 to 2.13:1 (51,101 longs versus 23,996 shorts), a meaningful shift that places Pro traders in direct opposition to FII's dominant short book — Pro desks are betting the current weakness is a buying opportunity or at minimum a range-trade setup at lower levels.
- Long PCR fell from 0.75 to 0.72 (change -4.44%) and Short PCR rose from 0.64 to 0.68 (change +5.65%). A Long PCR of 0.72 means Pro desks hold 28% fewer put longs than call longs — this is a net bullish options long posture, the inverse of FII's deeply defensive Long PCR of 1.66. The further decline of -4.44% in Long PCR confirms Pro is tilting their options long book incrementally more toward calls relative to puts today, even as the market sold off — a counter-trend bullish positioning. The Short PCR rising from 0.64 to 0.68 (+5.65%) means Pro desks are now writing proportionately more puts versus calls on the short side, which is a classic range income / bullish short-put strategy — they are comfortable selling put premium at current levels, implying they do not expect a catastrophic downside move. Together, a falling Long PCR and a rising Short PCR create the most consistently bullish options PCR signal among all four participants.
- Call OI net rose from +26,254 to +131,005 (net change +104,751) — Long 1,337,674 [Long Buildup - Low Vol] versus Short 1,206,669 [Short Buildup - Low Vol]. Put OI net rose from +127,910 to +137,044 (net change +9,134) — Long 958,371 [Long Buildup - Low Vol] versus Short 821,327 [Short Buildup - Low Vol]. The call OI net explosion from +26,254 to +131,005 is the most dramatic single-leg options change in today's data — Pro desks added 284,865 call longs against 180,114 call shorts, resulting in a +104,751 net call long surge. Both legs carry Low Vol tags, suggesting this was not panic buying but rather systematic accumulation of call longs as a directional or delta-hedging strategy. The net put OI of +137,044 (net long puts) combined with the massively net long calls of +131,005 creates a long strangle or straddle architecture — Pro desks are positioned for a significant directional move in EITHER direction, but the futures long buildup of +18,711 and the bullish PCR tilt suggest the primary directional bet is upward, with the put longs serving as tail-risk insurance.
- Synthesis — Pro Contrarian Long Strangle with Bullish Futures Tilt: Pro desks today present the most internally active and nuanced positioning of all participants. Their futures net nearly tripled from +8,394 to +27,105, their call net exploded to +131,005, and their put net held at +137,044 — together creating a long strangle anchored by a bullish futures position. This is a sophisticated strategy that profits maximally if Nifty makes a large move upward (futures + call longs win), while being partially protected on the downside (put longs provide a cushion). The falling Long PCR (0.72) and rising Short PCR (0.68) confirm the tilt is directionally bullish rather than neutral strangle. Critically, Pro desks stand in direct contrast to FIIs today — while FIIs are pressing shorts at -310,174 net futures, Pro desks are aggressively adding longs at +27,105 net, and their call-buying surge suggests they may be anticipating a short-squeeze or V-shaped reversal. The Low Vol tags on virtually all Pro legs are worth flagging as a mild caveat — high-conviction contrarian longs would ideally carry Avg or High Vol confirmation, and the Low Vol signal leaves open the possibility this is delta-hedging by market makers rather than pure directional conviction.
- Forward trigger: The critical validation level for Pro's bullish thesis is whether Nifty can stabilize and reclaim the area above 22,421 (today's close) without the FII futures net worsening beyond -325,000 contracts. If tomorrow's data shows Pro's call net long expanding further above 150,000 contracts alongside a stable or improving futures net above +27,000, it would confirm they are doubling down on a contrarian long and the probability of a short-squeeze rally increases substantially. Conversely, if Pro's futures net retreats below +15,000 (reduction of ~12,000 contracts), it would signal their contrarian thesis is being abandoned quickly under FII selling pressure — a bearish confirmation signal for the overall market.
Client Cautiously Bullish — Long Futures, Aggressive Put Hedging, Selling Calls
- Futures net improved from +242,426 to +249,812 (net change +7,386 contracts), extending Client's already dominant long futures position. The Long side added 5,526 contracts (prev 301,040 → today 306,566, [Long Buildup - Low Vol]) while the Short side reduced by -1,860 contracts (prev 58,614 → today 56,754, [Short Covering - Low Vol]). Both legs carry Low Vol tags — meaning Clients are adding futures longs and covering futures shorts on below-average volume, suggesting retail and HNI participants are selectively buying the dip in futures but without strong conviction or high trading intensity. The gross long-to-short ratio stands at 5.40:1 (306,566 longs versus 56,754 shorts) — Clients are structurally the most futures-long participant by net position (+249,812), standing in direct opposition to FII's -310,174 net short. This FII-vs-Client tug-of-war in futures is the dominant structural tension in today's market, and historically when FII presses shorts while Clients add longs on Low Vol, the institutional short tends to prevail.
- Long PCR rose from 0.59 to 0.63 (change +6.24%) and Short PCR fell from 0.97 to 0.93 (change -4.48%). A Long PCR of 0.63 means Clients hold 37% more call longs than put longs — despite being heavily net long in futures, they are buying more calls than puts on the options long side, which is internally consistent bullish retail positioning (buying calls to leverage upside exposure). The rise in Long PCR from 0.59 to 0.63 (+6.24%) signals Clients are incrementally adding put protection relative to calls — they are becoming slightly more hedged even as they remain net bullish, which is a healthy sign of risk-awareness on the long side. The Short PCR falling from 0.97 to 0.93 means Clients are writing proportionately fewer puts and more calls on the short side — this shift away from put writing toward call writing suggests Clients are now capping their upside shorts (writing calls) rather than writing puts for income, consistent with a view that the market may struggle to recover quickly.
- Call OI net fell sharply from +433,777 to +295,484 (net change -138,293) — Long 3,743,798 [Long Buildup - Low Vol] versus Short 3,448,314 [Short Buildup - Low Vol]. Put OI net held near flat at -843,148 (prev -842,693, net change -455) — Long 2,363,022 [Long Buildup - Low Vol] versus Short 3,206,170 [Short Buildup - Low Vol]. The most significant structural shift for Clients is the -138,293 collapse in call net OI — Clients added 409,331 call longs but added 547,624 call shorts, resulting in a net call position that turned increasingly short. This is a critical divergence: Clients are net long futures (+249,812) but are becoming increasingly net short calls (+295,484 and declining), which creates a covered call architecture — a bullish-but-capped strategy where the call shorts reduce cost basis and cap upside at current resistance. The put OI net of -843,148 means Clients are net short puts by a massive margin (3,206,170 short versus 2,363,022 long), adding further complexity — they are writing puts AND writing calls simultaneously, which at this scale describes a short strangle around their long futures book, expressing a range-bound view rather than a strong directional conviction.
- Synthesis — Client Covered Long with Short Strangle Overlay: Clients today are running a multi-leg strategy that superficially appears bullish (futures net +249,812, call longs 3,743,798) but is structurally more range-bound than directionally aggressive. The combination of net long futures + net short calls (+295,484 falling) + net short puts (-843,148 stable) creates a synthetic covered-call strangle — Clients are long the underlying via futures, writing calls to cap upside premium collection, and writing puts to collect income on the downside. This architecture is consistent with retail HNI behavior on weak days: they did not panic-sell futures (added +7,386), but they are monetizing both sides of the options market to offset the MTM loss from their futures longs. The Low Vol tags across ALL Client legs today is consistent with retail-driven, scattered accumulation rather than institutional conviction. Compared to FII's dominant short of -310,174, Clients at +249,812 longs remain the primary counterparty absorbing FII futures supply — but without High Vol conviction, this retail long book is vulnerable to being squeezed lower by institutional FII pressure. The sharp call-short addition (547,624 new call shorts versus 409,331 call longs) is the one genuine bearish nuance — Clients themselves appear to believe upside is limited even as they hold long futures.
- Forward trigger: The key metric to watch for Clients tomorrow is whether their futures net long expands beyond 260,000 (from 249,812) — any material expansion with improving volume tags would signal retail participants aggressively buying the dip and could provide a technical floor for Nifty near 22,000 OI support. Conversely, if Client futures net deteriorates below 240,000 (a reduction of ~10,000 contracts), it would mean retail is beginning to capitulate their long book — historically a precursor to a sharper decline, as the cushion absorbing FII shorts would be removed. Watch the 22,000 Nifty PE support strike as the level at which Client put shorts become threatened — if Nifty approaches 22,000, Client short puts will come under pressure and forced covering could accelerate the downside move.
Bull vs Bear Strength by Participant
FII Strongly Bearish 87% ▼▼ | DII Mildly Bearish 58% ▼ | Pro Contrarian Bullish 65% ▲ | Client Cautious Long / Capped 52% ▶ |
Conclusion — Market Outlook for Tomorrow (01 Oct 2026)
The collective participant positioning on 01 Oct 2026 is unambiguously bearish at the structural level, led by FII's deepening futures short of -310,174 contracts (expanded by -27,304 today) and buttressed by a net put long of +666,578 contracts — a dual-leg bearish architecture of rare scale. DII has begun reducing long exposure, trimming futures longs to 48,119 and unwinding 6,556 put longs, removing a key cushion from the bull side. Pro desks are the lone contrarian voice with a futures net long of +27,105 and a call net surge to +131,005, but their Low Vol confirmation tags limit the conviction score of this counter-move. Clients remain the largest futures long at +249,812 but are simultaneously writing calls and puts in a short strangle structure, which signals they expect range-bound conditions rather than a meaningful recovery — their own behavior betrays a lack of upside confidence despite holding long futures.
India VIX spiking to 14.46 from 13.49 (a +7.15% single-session surge) on a down-close of -0.88% in Nifty is a textbook fear escalation signal — option premium is expanding, hedging demand is rising, and sellers are pressing positions. The Overall PCR has slipped further to 0.78 from 0.79 (prev change -1.83%), with Call OI growing at +18.47% versus Put OI at +16.30% — call side supply is outpacing put side demand, keeping the PCR suppressed and the sentiment bearish. The OI support at 22,000 Nifty (PE max OI) is now the critical structural floor watched by all participants — FII put longs are clustered there, Client short puts are at risk below it, and a breach would trigger a cascade of forced covering. Total OI surging by +9.68% on a day when all three major indices declined confirms that bears are adding fresh short positions rather than bulls stepping in — the weight of evidence points toward continued selling pressure with a downside target toward the 22,000 OI support unless FII shorts are meaningfully reduced.
The bearish thesis would be invalidated if FII futures net begins to recover above -300,000 contracts (short covering of approximately 10,000+ contracts) alongside a VIX reversal below 13.50 and Overall PCR recovering above 0.85 — these three concurrent signals would suggest the bearish positioning is being unwound and a short-squeeze is underway. Pro's contrarian long buildup to +27,105 is the primary early-warning indicator to watch — if tomorrow's data shows Pro expanding futures longs above 35,000 with Avg or High Vol tags, the probability of a technical recovery toward 23,000 CE resistance (Nifty week) increases substantially.
Scenario 1 — Bull case:
If FII futures net short begins to recover toward -295,000 contracts (implying short covering of ~15,000 contracts), concurrent with Overall PCR rising back above 0.85 and India VIX declining below 13.50, the conditions for a short-squeeze rally materialize. Pro's call net long of +131,005 would act as fuel, and Client put short covering (if the 22,000 support holds firm) would add momentum. The upside OI resistance at 23,000 (Nifty week CE) and 23,500 (Nifty month CE) would be the next structural targets in this scenario.
Scenario 2 — Bear case:
If FII futures net worsens beyond -325,000 contracts tomorrow, VIX extends above 15.50, and Overall PCR slides below 0.70, the bearish momentum would accelerate toward the 22,000 PE OI support (Nifty week and month combined). A breach below 22,000 would threaten Client short puts (gross 3,206,170 contracts), triggering forced covering that acts as additional selling pressure. DII's reduced put long book (trimmed to 40,402 from 46,958) means there is less institutional buy-side cushion than in previous sessions, making a clean break of 22,000 more probable in this scenario.
Key Resistance 23,000 (Nifty Week CE) and 23,500 (Nifty Month CE) — FIIs hold gross call shorts of 1,101,948 concentrated at upper strikes, while Clients have added 547,624 fresh call shorts today. This dual-participant call-writing wall creates heavy supply at and above these strikes, making any recovery likely to stall unless FII short covering materially reduces this overhead. | Key Support 22,000 (Nifty Week and Month PE) — FII net put longs of +666,578 are anchored here as a structural hedge floor. However, Client's net short puts of -843,148 become dangerously exposed below this level — a breach would force Client put-short covering that could accelerate selling rather than absorb it. This support is therefore a double-edged level: strong as long as it holds, but self-reinforcing to the downside if breached. | Trigger to Watch Overall PCR crossing above 0.85 (from current 0.78) alongside FII futures net recovering above -300,000 contracts — both signals together would confirm bearish positioning is being reversed. A single signal without the other should be treated as a false alarm. Also watch India VIX: if it spikes above 16.00 without a corresponding further PCR decline, it signals volatility panic rather than directional selling — a different risk scenario requiring options-specific management. |