
Market Participants Analysis dated 02.09.2026
KRVFinMart — Daily Market Outlook
Key Market Signals — Data: 02 Sep 2026
NIFTY 50 23,914.45 ▼ -141.35 (-0.59%) | BANK NIFTY 57,172.00 ▼ -237.60 (-0.41%) | SENSEX 76,570.35 ▼ -373.93 (-0.49%) |
OVERALL PCR 0.90 ▼ -0.01 (-2.07%) PCR below 1.0 and declining — call OI expanding faster than puts, signalling cautious to bearish sentiment. | INDIA VIX 11.59 ▲ +0.10 (+0.87%) VIX nudging higher from 11.49 — low but rising, indicating slight increase in hedging demand on a down day. | TOTAL OI CHANGE 43,075,790 ▲ +3,611,508 (+9.15%) Large OI build on a falling market — fresh shorts being added across the board, bearish OI signal. |
FUTURES OI 754,344 ▲ +24,988 (+3.43%) Futures OI rising with price declining — classic short buildup confirmation in index futures. | CALL OI CHANGE 8,758,497 ▲ +1,642,892 (+23.09%) Sharp call OI expansion signals heavy resistance writing and bearish directional call buying above market. | PUT OI CHANGE 7,839,946 ▲ +1,336,245 (+20.55%) Put OI also surging, but at a slower pace than calls — net PCR decline confirms call-heavy expansion. |
Participant-wise Key Points
FII Strongly Bearish — Accelerating Dual-Leg Short Architecture
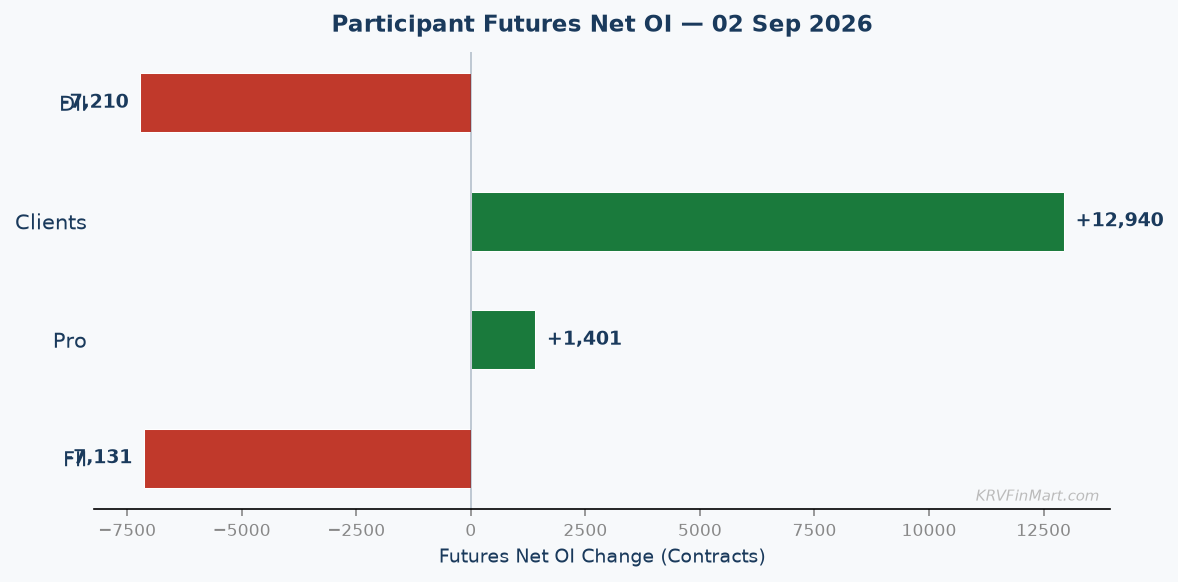
- Futures net deteriorated from -222,032 to -229,163 (net change -7,131 contracts), driven by the long side adding 3,819 contracts (prev 24,718 → today 28,537, +15.45% [Long Buildup - High Vol]) and the short side adding 10,950 contracts (prev 246,750 → today 257,700, +4.44% [Short Buildup - High Vol]). Both legs carry the High Vol confirmation tag, which is critical — High Vol indicates these are deliberate, conviction-driven prints rather than passive or routine rollovers. The gross short-to-long ratio stands at a towering 9.03:1 (257,700 short vs 28,537 long), which is unambiguously an outright directional short position of the highest order; this is not a hedge against an equity long book at any reasonable size. FIIs are not merely leaning bearish — they deepened this short book by a net 7,131 contracts on a day when Nifty was already falling, confirming they are not covering into weakness but pressing the position with conviction. Notably, the long buildup of +3,819 at High Vol may represent a small tactical hedge or spread leg, but it is dwarfed by the short addition of +10,950, leaving the net position decisively more negative.
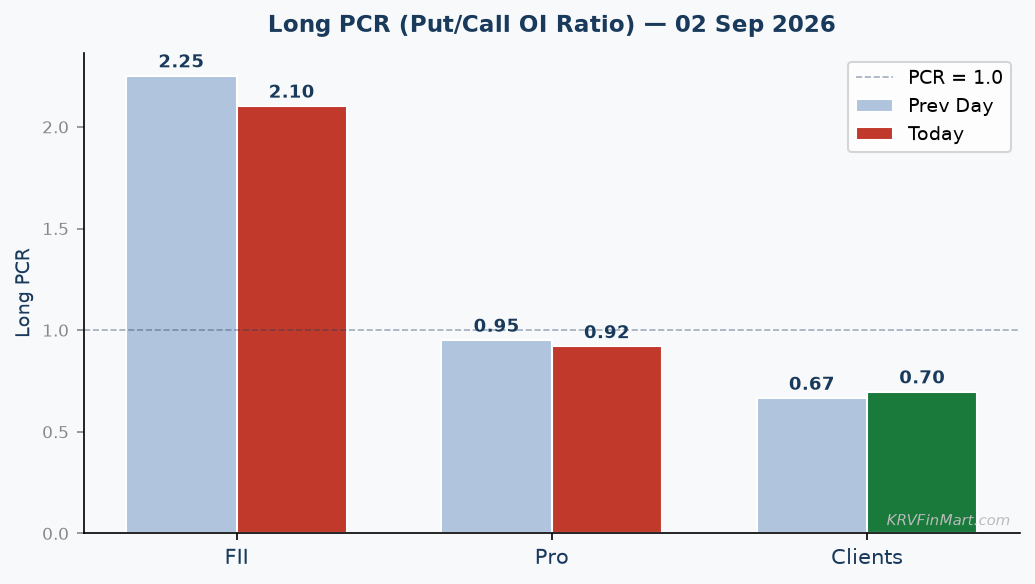
- FII Long PCR declined from 2.25 to 2.10 (chg -6.62%) and Short PCR rose from 0.43 to 0.50 (chg +16.26%). A Long PCR of 2.10 means FIIs hold 2.10 times as many put longs as call longs — for every one call they own, they own more than two puts, which is a deeply defensive-to-bearish posture that signals either massive equity book protection or outright directional bearishness through the options market. The decline in Long PCR from 2.25 to 2.10 could appear as hedging reduction, but in context it reflects faster call long addition (+57,199) relative to put long addition (+59,991) — the absolute put long book at 971,327 remains enormous. The Short PCR rising from 0.43 to 0.50 (+16.26%) is a significant signal: FIIs are now writing more puts than before relative to calls on the short side, which means they are expanding their put-writing book aggressively (+99,233 new short puts) — this introduces a nuanced element: the short put writing at scale could represent premium income collection with downside selling, implying FIIs see a floor somewhere around the 23,000 PE support level while still shorting futures above. The dominant signal today is the Short PCR rise (+16.26%), which tells us FIIs are not purely buying puts for protection — they are simultaneously selling puts below, creating a structured range trade with a bearish upper bias.
- Call OI net deteriorated from -248,061 to -299,253 (net change -51,192 contracts): FII Call Longs stand at 461,823 [Long Buildup - Low Vol] vs Call Shorts at 761,076 [Short Buildup - Low Vol]. Put OI net declined from +632,465 to +593,223 (net change -39,242 contracts): FII Put Longs at 971,327 [Long Buildup - Low Vol] vs Put Shorts at 378,104 [Short Buildup - Low Vol]. The Low Vol tags on all four options legs are noteworthy — unlike futures where High Vol confirms strong conviction, the Low Vol on options suggests these builds happened on thinner-than-average options volumes, meaning these are deliberate positioned prints but in a low-liquidity window, possibly spread construction or end-of-day positioning. The net short call position of -299,253 is one of the largest gross net short call books visible in this dataset, capping upside above the 24,200 CE resistance, while the net long put book of +593,223 anchors downside protection below — together this is a synthetic short collar: short calls above market to cap upside + long puts below market for downside participation. This architecture as a whole perfectly complements and reinforces the outright futures short of -229,163, making FII positioning a three-legged bearish construction (short futures + short calls + long puts).
- Synthesis — FII Accelerating Three-Legged Bearish Architecture: FIIs present the most internally consistent and structurally complete bearish positioning of any participant today. Their futures net of -229,163 (gross short 257,700 at a 9.03:1 ratio) is supported on both options legs: net short calls at -299,253 cap any upside rally at the 24,200 CE resistance, and net long puts at +593,223 provide full downside participation below market. The Short PCR rising to 0.50 (+16.26%) adds a sophisticated layer — FIIs are also selling puts, likely around the 23,000 PE support, creating a defined downside profit window roughly between 23,000 and 24,200 — a structured bearish range trade, not an open-ended crash bet. The High Vol confirmation on both futures legs signals this is not passive carry — they actively added to both sides today with conviction. Compared to the previous session, this is an acceleration of the bearish thesis: futures net worsened by 7,131, put long net reduced by 39,242 (some protection monetised or rolled), and short call net expanded by 51,192 (more upside capping). The single internal nuance is the Long PCR decline from 2.25 to 2.10, which could suggest slight reduction in protective hedging intensity, but with 971,327 put longs outstanding this remains an overwhelmingly defensive and directionally bearish options book.
- Forward: The critical trigger to watch is whether FII futures net crosses -235,000 (i.e., a further net deterioration of ~5,837 contracts from today's -229,163) in tomorrow's data — if it does, this confirms FIIs are pressing the short into any bounce and the market faces a high-probability continuation lower toward the 23,000 PE support zone. Conversely, if FII futures net improves (short covering, net moving back toward -220,000 or better) AND the Short PCR retreats below 0.45, that would be the first genuine signal of a thesis reversal and could trigger a sharp short-covering bounce. Watch the 24,200 CE resistance level closely — a sustained move above it in Nifty cash would put maximum pressure on FII's massive short call book and could accelerate covering-driven upside momentum.
DII Bearish Shift — Aggressively Adding Futures Shorts While Reducing Longs
- Futures net declined from +20,477 to +13,267 (net change -7,210 contracts), driven by long unwinding of -1,528 contracts (prev 43,641 → today 42,113, -3.50% [Long Unwinding - Low Vol]) and a sharp short buildup of +5,682 contracts (prev 23,164 → today 28,846, +24.53% [Short Buildup - High Vol]). The contrast in confirmation tags is telling: the long reduction carries a Low Vol tag (passive, routine trimming of longs without aggression) while the short addition carries a High Vol tag (deliberate, high-conviction fresh short initiation). This asymmetry — quiet long unwinding + aggressive short buildup — is not a neutral repositioning; it is a directional bearish pivot. The gross short-to-long ratio has shifted meaningfully: from a prior 23,164:43,641 (0.53:1 short-to-long) to today's 28,846:42,113 (0.69:1), meaning DIIs are closing the gap between their long and short futures books rapidly, and if this trend continues for 2-3 sessions, their net futures position could approach flat or even flip negative — a historically significant signal from this typically bullish participant class. This move stands in sharp contrast to FII behavior (both are net adding to bearish futures exposure today), and notably it diverges from their usual role as market stabilisers — DIIs appear to be taking a tactical defensive stance.
- DII does not have a reported Long PCR or Short PCR in today's dataset, so a precise PCR ratio analysis is not available for this participant. However, directional inference from their options OI changes is possible: DII's Call OI net declined from +4,835 to +4,260 (chg -575), driven by a large call short addition of +575 contracts in shorts while longs remained flat at 5,176 [Long Flat - Low Vol]. Their Put OI net declined slightly from +31,923 to +30,008 (chg -1,915), from 30,048 long puts [Long Unwinding - Low Vol] vs 40 short puts [Short Flat - High Vol]. The directional implication from these option changes is that DII reduced their net long put exposure (unwinding protective hedges) while simultaneously adding call shorts — a combination that mildly points toward income-generation or premium collection rather than pure directional hedging. The absence of PCR data means we rely on the options OI architecture for DII's options-side sentiment, and the dominant read is one of cautious income positioning rather than aggressive directional options play.
- Call OI net declined from +4,835 to +4,260 (net change -575 contracts): DII Call Longs held flat at 5,176 [Long Flat - Low Vol] while Call Shorts jumped from 341 to 916 [Short Buildup - High Vol, +168.62%]. Put OI net declined from +31,923 to +30,008 (net change -1,915 contracts): DII Put Longs fell from 31,963 to 30,048 [Long Unwinding - Low Vol] while Put Shorts held flat at 40 [Short Flat - High Vol]. The +168.62% surge in call shorts (from 341 to 916 contracts) carries the High Vol tag — this tiny but aggressively built call short book signals DII is writing calls at current levels, likely collecting premium near the 24,200 CE resistance zone, aligning with a view that the market will not sustain a meaningful rally above current levels. Simultaneously, their quiet put long unwinding (-1,915 contracts at Low Vol) suggests they are reducing downside protection rather than adding it — which creates a mild contradiction with their aggressive futures short buildup. The overall options architecture for DII is a net long puts + net short calls structure (despite the reductions), which is still a mild synthetic short collar, reinforcing the bearish lean seen in futures but at a much smaller scale than FII.
- Synthesis — DII Tactical Bearish Pivot with Premium Collection Overlay: DIIs are in the midst of a notable behavioral shift today. Their net futures position dropped sharply from +20,477 to +13,267 (-7,210 contracts) through a combination of Low Vol long trimming and High Vol short addition (+5,682 at +24.53%) — the latter being the most assertive bearish futures move from DIIs in this data. Historically a net long, stabilising participant in index futures, this aggressive short buildup represents a tactical shift toward bearish hedging or outright short positioning, consistent with broader market weakness (Nifty -0.59%, Sensex -0.49%). Their options posture — flat call longs, surging call shorts (+168.62% at High Vol), and quietly reducing put longs — suggests they are layering on a premium-collection strategy: writing calls at resistance to benefit from time decay in a rangebound-to-lower environment, while not aggressively buying new put protection (implying they see limited acute downside, just controlled downward drift). The combination of futures net short buildup and call short writing creates a bearish income overlay: positioned to profit if the market stays flat-to-down with the short calls generating income and the short futures generating mark-to-market gains. Compared to the previous session where DII had net +20,477 futures, this is a significant directional acceleration to the bearish side, and it aligns directionally with FII but is more measured in scale.
- Forward: The key trigger for DII is whether their futures net continues toward +5,000 or below in tomorrow's data — a further net deterioration by ~8,000 contracts would bring them close to flat futures exposure for the first time in a prolonged bullish cycle, which would be a strong bearish confirmation signal for the broader market. If instead DII's futures longs rebuild (net improving back above +18,000) and call shorts are covered, it would signal their bearish pivot was a one-day tactical adjustment rather than a trend change. Watch the 23,000 PE support level — DIIs holding or adding to their existing long put base near that level in tomorrow's data would confirm they are protecting against a breakdown below that key OI support zone.
Pro Cautiously Bullish Bias — Futures Net Long Expanding, Options Straddling Both Sides
- Futures net improved from +14,425 to +15,826 (net change +1,401 contracts): Longs added +1,807 contracts (prev 44,427 → today 46,234, +4.07% [Long Buildup - Avg Vol]) while Shorts added a smaller +406 contracts (prev 30,002 → today 30,408, +1.35% [Short Buildup - Avg Vol]). Both legs carry the Avg Vol confirmation tag, indicating this is a routine, measured addition rather than a high-conviction directional thrust — Pros are not making an aggressive bet here, they are gradually extending their net long position. The gross long-to-short ratio stands at 46,234:30,408 (1.52:1 long-to-short), a moderately bullish lean with a meaningful long-side advantage. Notably, Pro futures behavior stands in direct contrast to both FII (deeply net short -229,163) and DII (rapidly shrinking net long, pivoting to shorts) — Pros are the only participant class adding net long futures exposure today, making them a contrarian bullish voice in the futures market. This Avg Vol build suggests Pros are methodically positioning for a potential bounce or range-low entry at current Nifty levels around 23,914, possibly anticipating that FII short covering could trigger a mean-reversion rally.
- Pro Long PCR declined from 0.95 to 0.92 (chg -3.32%) and Short PCR rose from 0.81 to 0.84 (chg +3.79%). A Long PCR of 0.92 means Pros hold nearly equal put longs and call longs (92 puts for every 100 calls), which is a balanced, hedged options posture — neither deeply defensive nor aggressively bullish through options alone. The decline in Long PCR from 0.95 to 0.92 (-3.32%) indicates Pros added slightly more call longs than put longs today (their call long addition of +109,535 significantly outpaced put long addition of +77,306), tilting their long options book marginally more bullish. The Short PCR rising from 0.81 to 0.84 (+3.79%) means Pros are writing slightly more puts relative to calls on the short side, which is a mild bullish-income signal: selling puts suggests a view that downside is limited near current levels, consistent with their futures net long position. Together, the declining Long PCR and rising Short PCR both lean mildly bullish in options, complementing rather than contradicting their futures long bias, though the magnitudes are small and neither PCR has crossed a decisive threshold (Long PCR below 0.80 would signal strong bullish tilt; Short PCR above 1.00 would signal heavy put writing conviction).
- Call OI net improved from -18,758 to +21,925 (net change +40,683 contracts): Pro Call Longs surged to 853,160 [Long Buildup - Low Vol] while Call Shorts rose to 831,235 [Short Buildup - Low Vol], flipping Pro from a net short call to a net long call position for the first time in this comparison period. Put OI net declined slightly from +92,559 to +88,909 (net change -3,650 contracts): Pro Put Longs at 784,778 [Long Buildup - Low Vol] vs Put Shorts at 695,869 [Short Buildup - Low Vol]. The flip of the call options net from -18,758 to +21,925 (+40,683 swing) is the single most significant options development in the Pro book today — Pros are now net long calls, which is an explicitly bullish directional bet through options. Combined with their net long put position (+88,909), Pros are running a net long strangle or synthetic long with a put hedge: net long calls above + net long puts below. However, all four legs carry Low Vol tags, meaning this massive options expansion happened on below-average volume — the positions are there but the conviction level from a volume-intensity standpoint is moderate rather than extreme. The overall architecture confirms Pros are positioned for a volatility expansion or directional move, with a slight long-side tilt given futures and the call PCR data.
- Synthesis — Pro Asymmetric Long Bias with Strangle Hedging: Pros are the most nuanced participant today, running a multi-leg strategy that combines a modest net long futures position (+15,826 contracts) with a freshly flipped net long call book (+21,925) and a sustained net long put book (+88,909). This creates a net long strangle overlay on a long futures base: they profit most if the market makes a meaningful directional move (preferably up, given futures longs) while the long puts cushion against a downside break. The Avg Vol on futures and Low Vol across all options legs tells us this is a methodical, spread-driven construction rather than a high-conviction single-direction bet — Pros are professional market-makers and prop traders who tend to position for volatility and range resolution rather than pure directional momentum. The flip from net short calls (-18,758) to net long calls (+21,925) is the key behavioral change: yesterday Pros were capping upside via short calls; today they are opening upside optionality, which is a subtle but meaningful bullish shift. Compared to the previous session, Pros have accelerated their bullish lean in futures and reversed their options architecture from bearish (short calls) to bullish (long calls), making them today's only participant with a constructive near-term view — a meaningful divergence from FII and DII. The Low Vol caveat means this could be spread-driven positioning that is not purely directional, but the net composite picture leans cautiously bullish.
- Forward: The critical trigger for Pro is whether their futures net continues to expand above +18,000 in tomorrow's data — a move to +18,000 or better would signal their long bias is strengthening and could precede institutional covering-driven upside. Watch also whether their Call OI net (today at +21,925) expands further above +30,000 tomorrow: sustained expansion of net long calls by Pros would confirm the low-vol call buying today was a deliberate directional bet on a bounce rather than a hedge. If instead Pros' futures net retreats below +12,000 and call longs are covered, the bullish case weakens and the weight of FII-DII bearish positioning takes precedence.
Client Cautiously Bullish — Adding Long Futures, Covering Shorts, Heavy Options Activity Both Sides
- Futures net improved from +187,130 to +200,070 (net change +12,940 contracts): Longs added +8,396 contracts (prev 251,892 → today 260,288, +3.33% [Long Buildup - High Vol]) while Shorts reduced -4,544 contracts (prev 64,762 → today 60,218, -7.02% [Short Covering - Avg Vol]). The High Vol tag on the long buildup is significant — Clients are adding to futures longs with high conviction, not passively rolling. Simultaneously, the Avg Vol short covering (-4,544) suggests routine but meaningful short unwinding. The gross long-to-short ratio stands at 260,288:60,218 (4.32:1 long-to-short), an emphatically bullish futures posture — Clients hold more than four times as many long futures as short futures. This behavior is a direct contradiction to FII (-229,163 net) and DII (shrinking net long to +13,267): Clients are aggressively buying futures longs and covering shorts on a down day, which is classic retail-contrarian behavior — buying weakness with conviction. With a net futures position of +200,070, Clients represent the largest gross net long in the market today, directly offsetting a significant portion of FII's massive short book.
- Client Long PCR rose from 0.67 to 0.70 (chg +4.75%) and Short PCR declined from 1.10 to 1.02 (chg -7.20%). A Long PCR of 0.70 means Clients hold 70 put longs for every 100 call longs — they own more calls than puts on the long side, which is a net bullish options posture. The rise in Long PCR from 0.67 to 0.70 (+4.75%) indicates Clients added more put longs relative to call longs today, slightly increasing their hedging posture (+532,741 put longs vs +654,712 call longs), though the absolute direction remains net call-heavy (bullish). The Short PCR declining from 1.10 to 1.02 (-7.20%) is a notable shift: Clients were previously writing more puts than calls on the short side (Short PCR 1.10 = range-income bearish), but today moved closer to parity — this means they reduced their put-writing relative to call-writing, potentially closing out some put short positions or adding more call shorts. The dominant signal is still net bullish through options (more call longs than put longs, Long PCR 0.70), consistent with their futures long stance, but the Short PCR decline suggests Clients are incrementally pulling back from aggressive put selling, possibly recognising increased downside risk from FII/DII positioning.
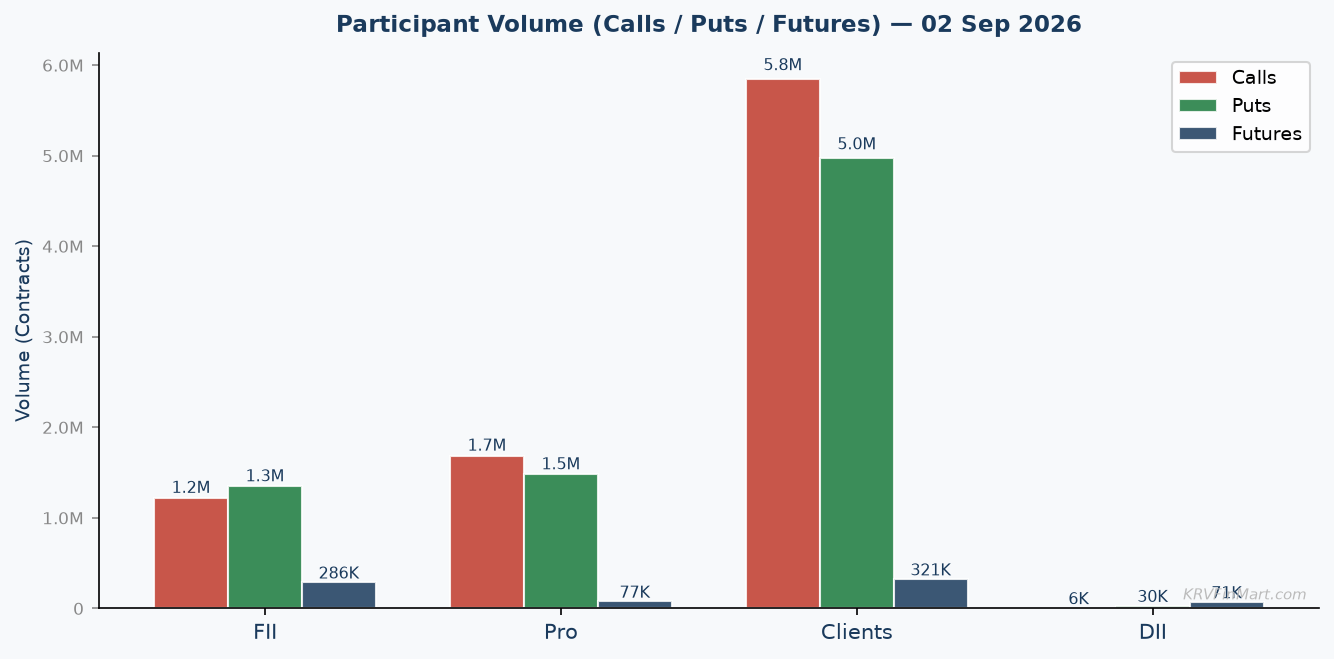
- Call OI net improved from +261,983 to +273,067 (net change +11,084 contracts): Client Call Longs exploded to 3,059,089 [Long Buildup - Low Vol] vs Call Shorts at 2,786,022 [Short Buildup - Low Vol]. Put OI net improved from -756,948 to -712,140 (net change +44,808 contracts): Client Put Longs at 2,133,820 [Long Buildup - Low Vol] vs Put Shorts at 2,845,960 [Short Buildup - Low Vol]. Clients added a staggering +654,712 call longs and +643,628 call shorts on the same day — the scale of activity (+1.3M contracts across both call legs) points to massive options activity, likely dominated by short-dated weekly option buying and selling. The net call position of +273,067 (net long calls) combined with a net short put position of -712,140 creates a synthetic long overlay: net long calls (upside participation) combined with net short puts (downside income selling, i.e., willing to own the market lower). This is a classic bullish risk-reversal orientation among retail/client participants — they are buying calls for upside and selling puts for income, expressing a directional long view with income generation. The Low Vol tags on all four legs indicate this happened in a thin-volume options session, suggesting broad retail participation across many small trades rather than concentrated institutional action.
- Synthesis — Client Bullish Risk-Reversal Architecture on Decline: Clients are behaving as the structural bulls of today's market — with futures net leaping from +187,130 to +200,070 (+12,940 at High Vol long buildup), net long calls at +273,067, and a net short put book of -712,140 (indicating willingness to absorb downside at lower levels). This classic bullish risk-reversal positioning (long calls + short puts + long futures) is directionally unanimous and strongly signals Clients expect a market recovery from current Nifty levels near 23,914. Their Long PCR of 0.70 and Short PCR of 1.02 both confirm the bullish orientation. However, a critical risk flag must be noted: Clients are also net short puts at -712,140, which means if the market breaks below the 23,000 PE support level, they face accelerating mark-to-market losses on short puts — their position has asymmetric risk to the downside. Compared to the previous session, Clients have accelerated their net long exposure across all three legs (futures, call longs, put shorts), doubling down on a contrarian bullish thesis against FII's massive short. This positions Clients as the key counterparty to FII's bearish trade — if FII short covering triggers a rally, Clients' long book profits maximally; if FII deepens shorts and the market falls further, Clients' short put book amplifies losses beyond just futures losses.
- Forward: The critical trigger for Clients is whether the 23,000 PE support (maximum put OI level) holds as floor in the coming sessions — as long as Nifty stays above 23,000, Clients' short put book remains safe and their bullish thesis stays intact. Watch if Client futures net breaks decisively above 210,000 in tomorrow's data — a move to that threshold would confirm Clients are continuing to press the contrarian long aggressively and could signal a capitulation squeeze for FII shorts. Conversely, if Nifty breaks below the 23,000 PE support level, Clients' massive short put book (2,845,960 contracts) could trigger a wave of forced covering and stop-loss selling that amplifies downside — the net short put position of -712,140 is a key vulnerability that makes Client positioning a double-edged sword for market stability.
Bull vs Bear Strength by Participant
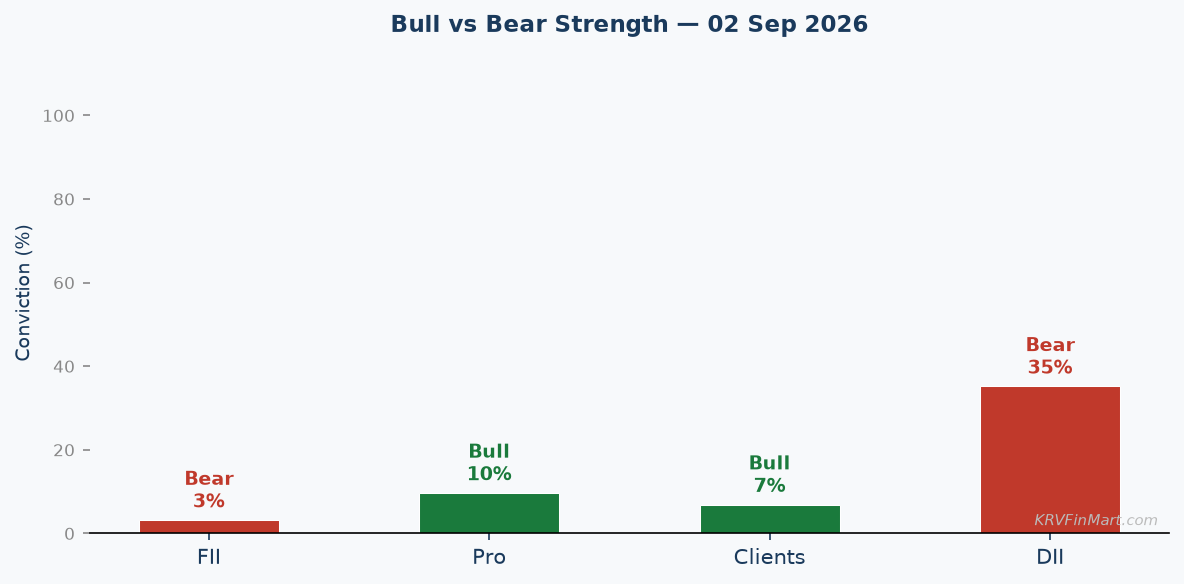
FII Strongly Bearish 88% ▼▼ | DII Bearish Shift 68% ▼ | Pro Cautiously Bullish / Hedged 55% ▲ | Clients Contrarian Bullish 62% ▲▲ |
Conclusion — Market Outlook for Tomorrow (03 Sep 2026)
The collective participant positioning on 02 Sep 2026 presents a structurally bearish picture with a critical but fragile counterweight. FIIs hold the dominant narrative: a futures net of -229,163 at a gross 9.03:1 short-to-long ratio, reinforced by net short calls of -299,253 and net long puts of +593,223, constitutes the most comprehensive three-legged bearish architecture visible in today's data. DIIs have joined the bearish camp with an aggressive pivot — their futures net collapsed from +20,477 to +13,267 on a High Vol short buildup of +5,682 contracts, and their call short book surged +168.62% at High Vol. Against this institutional bearishness, Clients are the contrarian force with a futures net of +200,070 (+12,940 today at High Vol), net long calls of +273,067, and a risk-reversal structure that profits from a recovery — but their -712,140 net short put position creates tail risk if the market breaks down. Pros are the most nuanced, running a net long futures position of +15,826 with a freshly flipped net long call book (+21,925), leaning cautiously bullish but at Avg/Low Vol conviction. The weight of institutional positioning (FII + DII both bearish) significantly outpresses the retail-driven (Client) long bias, and the total OI surge of +9.15% on a declining market is the textbook signature of fresh short buildup — not covering or new longs.
The Overall PCR declined from 0.91 to 0.90 (-2.07%), and with Call OI expanding at +23.09% versus Put OI at +20.55%, the options market is also reflecting a net bearish lean — calls are being added faster than puts, capping the upside and indicating either directional call buying or call writing at resistance. India VIX at 11.59 (+0.87%) is rising from a low base: while it remains in a complacent zone overall, the uptick on a down day suggests incremental hedging demand is returning, and if VIX continues to rise toward 13.00–14.00, it would signal genuine fear entering the market and likely accelerate the bearish thesis. The OI Resistance at 24,200 (CE) is FII's primary short call strike for Nifty, acting as a hard ceiling — any rally toward that level will encounter massive call-writer selling pressure. The OI Support at 23,000 (PE) is where FII put longs and Client short puts converge — it is simultaneously a floor (put long protection) and a trap (massive short puts that could amplify selling below it). BankNifty's OI Support at 57,000 (PE) and OI Resistance at 57,500 (CE) define an extremely compressed 500-point range, suggesting BankNifty is in a tight option writer's pin zone for the near term.
The bearish thesis would be challenged if FII futures net improves meaningfully above -220,000 (indicating short covering) AND the Overall PCR recovers above 0.95 in the next 1-2 sessions, which would signal put buying is outpacing call writing — a defensive repositioning toward downside protection rather than upside capping. A VIX spike above 14.00 could paradoxically become bullish if accompanied by PCR expansion above 1.00 (panic put buying = capitulation = potential bottom). The bull case requires Clients' contrarian longs to be vindicated by institutional covering — without FII short covering, the +200,070 Client long faces the full weight of -229,163 FII short and increasing DII shorts, making the market structurally vulnerable to a controlled grind lower toward the 23,000 PE support level as the path of least resistance in the near term.
Scenario 1 — Bull case:
If FII futures net improves from -229,163 toward -215,000 or better (net short covering of ~14,000+ contracts) AND the Overall PCR recovers above 0.95 in tomorrow's session, it would signal the FII short thesis is being challenged or trimmed. A VIX decline back below 11.00 alongside PCR expansion would confirm the bearish pressure is abating. Under this scenario, Clients' net long futures of +200,070 and Pros' net long calls of +21,925 become the lead positions, targeting the 24,200 CE resistance zone as the first upside objective. FII's massive short call book at 24,200 would face maximum squeeze pressure if this level is approached.
Scenario 2 — Bear case:
If FII futures net deteriorates further beyond -235,000 (additional net short addition of ~5,800+ contracts from today's -229,163) AND the Overall PCR slides below 0.85, the bearish architecture deepens with strong institutional backing. A VIX rise above 13.50 would confirm hedging demand is growing and margin-of-safety concern is rising. Under this scenario, the market grinds toward the 23,000 PE support — the convergence point where FII long puts (+971,327) are in-the-money and Client short puts (2,845,960) face accelerating losses. A break and sustained close below 23,000 with expanding OI would trigger Client short put covering/forced exits, potentially producing a sharp, disorderly decline.
Key Resistance 24,200 (Nifty CE max OI / Weekly OI Resistance): This is the strike where FIIs carry their largest net short call position (-299,253 net calls overall, with aggressive call short buildup of +108,391 today). DIIs have also added call shorts at High Vol (+168.62% today). Maximum call writer supply is concentrated at this level — any approach toward 24,200 from current Nifty at 23,914 will encounter institutional supply from two participant classes simultaneously, making this a high-conviction resistance ceiling for the near term. | Key Support 23,000 (Nifty PE max OI / Weekly & Monthly OI Support): This strike represents the intersection of FII put long protection (971,327 put longs, net +593,223) and Client short put exposure (2,845,960 short puts, net -712,140). FIIs have long puts here as directional instruments; Clients have short puts here as income trades. A market approach toward 23,000 will see FII put longs appreciate (potentially encouraging monetisation rather than protection) while Client short puts face mounting losses — the 23,000 level is simultaneously a structural floor and a potential amplification zone if breached. | Trigger to Watch Overall PCR threshold of 0.85: Today's PCR stands at 0.90 (declined from 0.91, -2.07%). If tomorrow's PCR falls to 0.85 or below, it signals call OI is overwhelmingly dominating put OI — confirming institutional participants are aggressively capping upside rather than buying downside protection. This would be the quantitative confirmation that the bearish architecture is strengthening and the market is likely to resolve lower toward 23,000 OI support. Alternatively, a PCR recovery above 0.95 with FII futures net improvement would be the clearest bull-reversal signal to watch. |