
Market Participants Analysis dated 04.09.2026
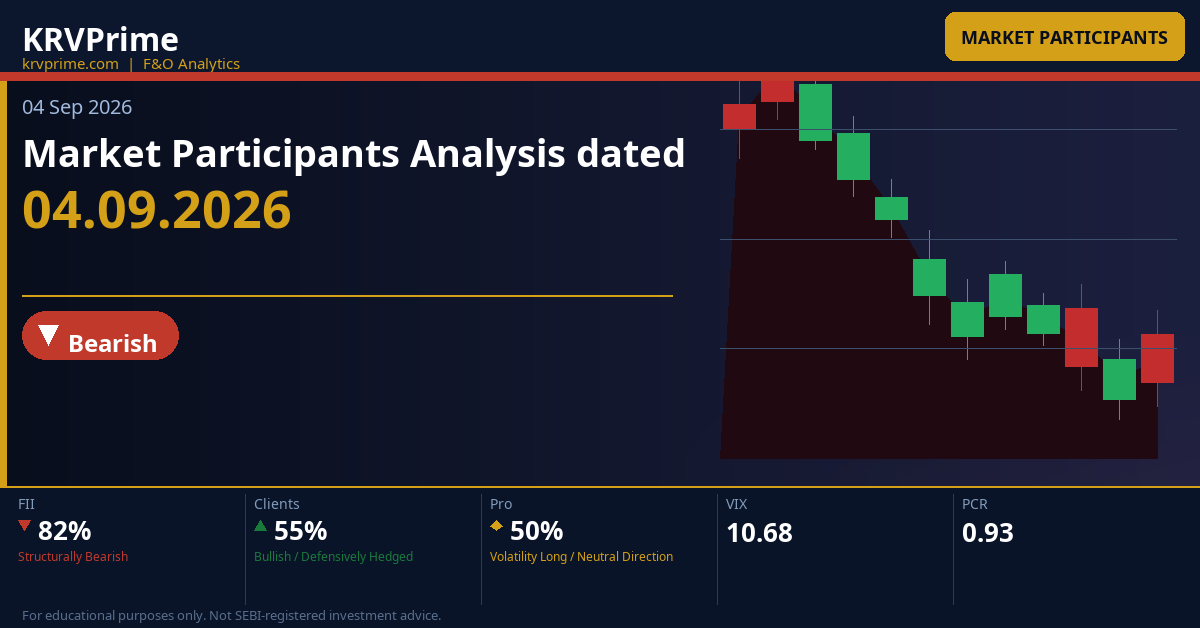
KRVPrime — Daily Market Outlook
Key Market Signals — Data: 04 Sep 2026
NIFTY 50 23,897.70 ▲ +24.25 (+0.10%) | BANK NIFTY 57,369.65 ▼ -10.95 (-0.02%) | SENSEX 76,515.43 ▲ +362.57 (+0.48%) |
OVERALL PCR 0.93 ▲ +0.11 (+13.95%) PCR rising from 0.82 to 0.93 — put buying surging, market building protective floor but not yet in extreme fear territory. | INDIA VIX 10.68 ▼ -0.66 (-5.80%) VIX at 10.68 — ultra-low complacency zone; sharp collapse from 11.34 signals premium sellers in control, low hedging demand. | TOTAL OI CHANGE 47,900,018 ▲ +1,488,980 (+3.21%) Significant OI expansion of +1.49M contracts — fresh positions being built across options, mostly on the put side. |
FUTURES OI 768,216 ▼ -2,738 (-0.36%) Marginal futures OI contraction — slight position reduction at current levels signals caution in directional futures bets. | CALL OI CHANGE 10,690,666 ▼ -90,449 (-0.84%) Call OI marginally contracting — short-covering at call strikes, slight supply reduction at resistance levels. | PUT OI CHANGE 9,978,958 ▲ +1,147,650 (+13.00%) Massive put OI surge of +13% — dominant signal of the day; protective buying and speculative put longs building aggressively. |
Participant-wise Key Points
FII Cautiously Bearish — Short Buildup in Futures and Puts, Hedged Call Cover
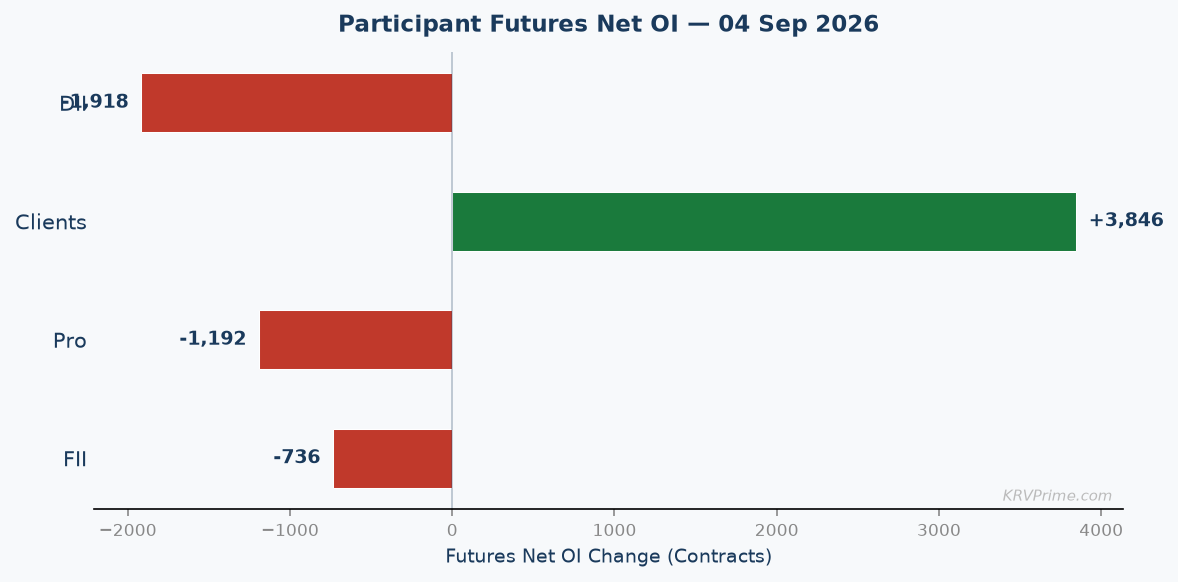
- Futures net deteriorated from -235,102 to -235,838 (net change -736 contracts, -0.31%). On the long side, FIIs added a modest +187 contracts (prev 33,502 → today 33,689), tagged [Long Buildup - Low Vol], while on the short side they added +923 contracts (prev 268,604 → today 269,527), tagged [Short Buildup - Low Vol]. Both the long and short additions carry a Low Vol confirmation tag, meaning these incremental moves were made in thin, hesitant conditions — this is not a high-conviction fresh push but rather a maintenance of an existing directional bias. The gross short-to-long ratio today stands at a staggering 7.99:1 (269,527 shorts vs 33,689 longs), which is an unambiguous structural directional short — this is not hedging, it is an outright bearish thesis on index futures that FIIs have been building and holding over multiple sessions. The marginal net deterioration of -736 tells us they are not yet convinced to cover, even as the market closed fractionally higher.
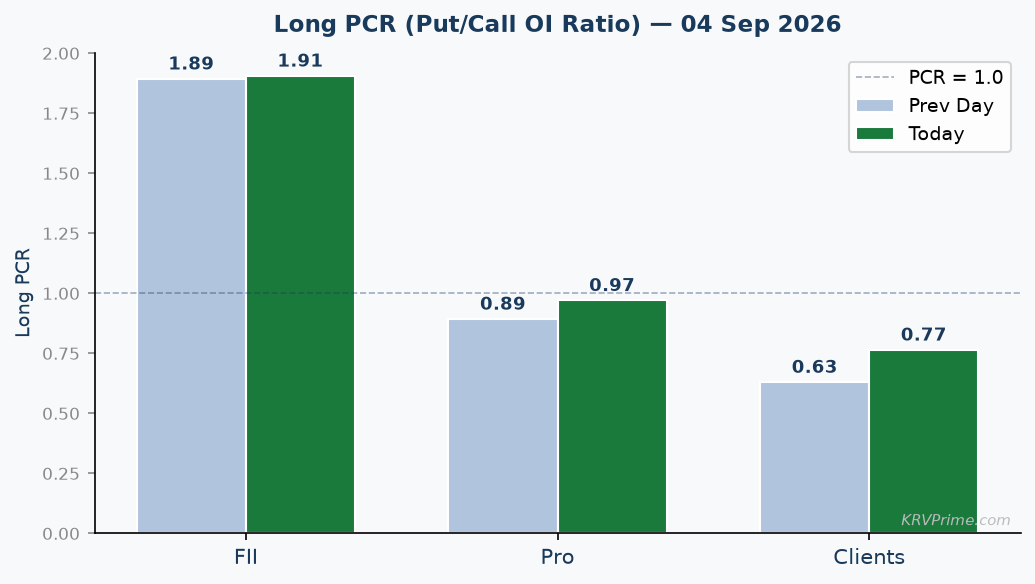
- Long PCR rose from 1.89 to 1.91 (+0.64%) and Short PCR surged from 0.46 to 0.57 (+22.28%). A Long PCR of 1.91 means FIIs hold nearly twice as many put longs as call longs on the long side — this is a deeply defensive or directionally bearish posture in options, consistent with either a large equity book hedge or a standalone bearish expression. The Long PCR inching up from 1.89 to 1.91 signals FIIs continued adding to put longs at a faster pace than call longs today. The Short PCR jumping from 0.46 to 0.57 (+22.28%) is the more explosive move — FIIs are now writing significantly more puts than calls on their short book, and while this could look superficially bullish (put writing), in the context of the Long PCR of 1.91, it more likely reflects monetisation of extreme put premium at lower strikes or a range-income overlay. The dominant signal is the Long PCR at 1.91 confirming the bearish structural view established in futures.
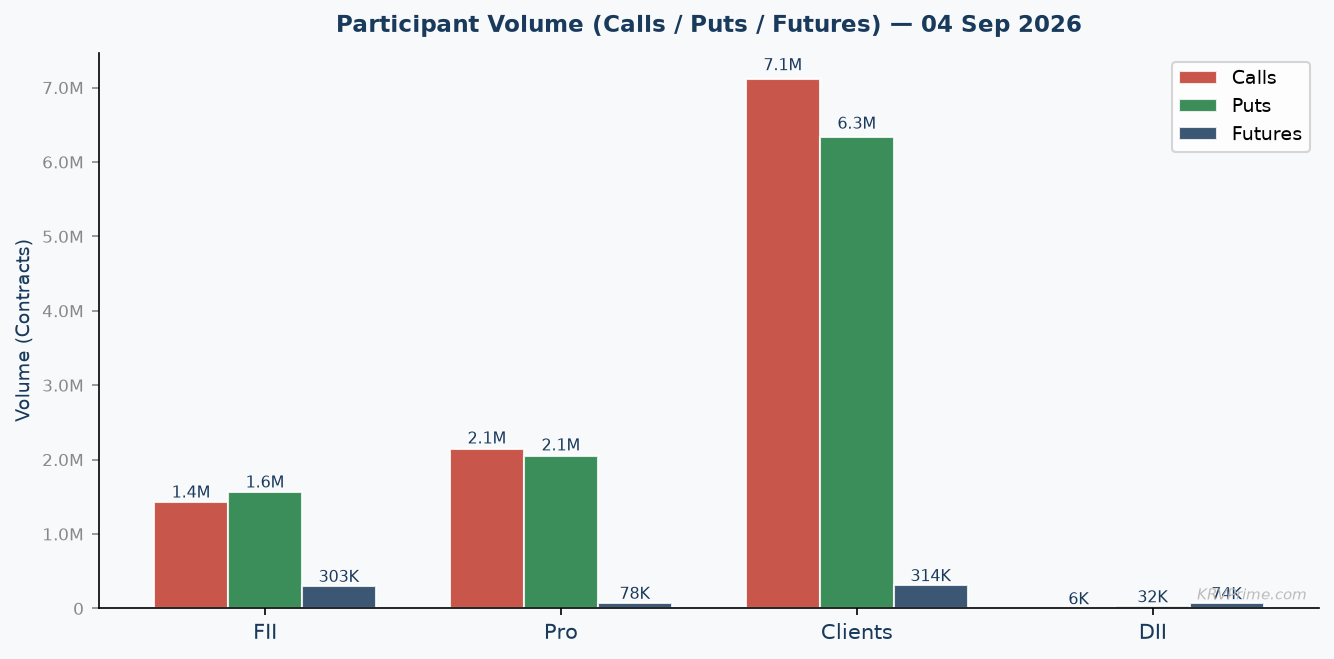
- Call OI net improved from -312,207 to -303,454 (net change +8,753) — FII Call Longs rose from 554,883 to 561,316 (+6,433, [Long Buildup - Avg Vol]) while Call Shorts fell from 867,090 to 864,770 (-2,320, [Short Covering - Avg Vol]). On the Put side, Put OI net deteriorated from +650,049 to +580,911 (net change -69,138) — Put Longs rose from 1,051,305 to 1,070,255 (+18,950, [Long Buildup - Avg Vol]) while Put Shorts exploded from 401,256 to 489,344 (+88,088, +21.95%, [Short Buildup - Avg Vol]). The architecture here is nuanced: net short calls (-303,454) combined with net long puts (+580,911) creates a classic protective collar or synthetic short overlay, but the massive surge in put writing (+88,088 contracts) slightly reduces the net put-long advantage. The Avg Vol confirmation tags on all four legs suggest these are deliberate, routinely managed positions — not emergency hedges.
- Synthesis — FII Dual-Leg Bearish Architecture with Put-Writing Overlay: FIIs present the most internally consistent and multi-layered structural story today. A futures net of -235,838 (maintaining a 7.99:1 gross short-to-long ratio), a Long PCR of 1.91, net short calls of -303,454, and net long puts of +580,911 all collectively point to one directional conclusion — FIIs are positioned for a market that either stalls or declines from current levels. The notable internal twist today is the massive put short addition of +88,088 contracts, which partially offsets the put-long advantage — this is best read as FIIs writing lower-strike puts (monetising the VIX drop from 11.34 to 10.68 by selling cheap insurance to retail put buyers) while retaining the core bearish structure via net short calls and long puts at higher strikes. The Low Vol tag on futures additions tells us FIIs are in maintenance mode, not acceleration mode — they have not panicked into covering despite the market's fractional gain. The call short-covering of -2,320 is a minor tactical adjustment, not a thesis reversal. Compared to the previous session, FII net futures moved from -235,102 to -235,838, showing near-perfect stability in their core bearish position — they are holding steady at a level of extreme gross short conviction.
- Forward: The critical threshold to watch is whether FII futures net crosses above -230,000 (i.e., net short contracts falling below 230,000) in tomorrow's data — such a move would signal the first meaningful short-covering episode and could trigger a momentum squeeze toward the 24,000 CE resistance strike. If instead FII futures net worsens further below -237,000 with an Avg or High Vol tag on the short side, the bearish thesis accelerates and the 23,000 PE support level comes into focus as the structural floor that Clients and DIIs are defending. Watch the FII Short PCR — if it rises above 0.65, it would confirm increasing put-writing income activity and a transition toward range-capping rather than outright short expansion.
DII Mildly Bearish — Net Long Futures Shrinking, Defensive Call Writing Added
- Futures net deteriorated from +13,287 to +11,369 (net change -1,918 contracts). On the long side, DIIs added a modest +282 contracts (prev 42,163 → today 42,445), tagged [Long Buildup - Low Vol], and on the short side they added a more significant +2,200 contracts (prev 28,876 → today 31,076), tagged [Short Buildup - Avg Vol]. The asymmetry between the Low Vol long addition and the Avg Vol short addition is the key tell — DIIs are adding to their long book hesitantly while building shorts with moderate conviction, resulting in a net long position that is shrinking. The gross long-to-short ratio today is 1.37:1 (42,445 longs vs 31,076 shorts), down from 1.46:1 in the prior session, indicating an erosion of net bullish exposure. This is a participant transitioning from a clearly bullish futures posture toward a more balanced, cautious positioning — they are not yet net short but the direction of travel is unambiguously toward reduced net long exposure.
- DII Index Options PCR data is not available in the participant-level dataset (DII does not report Long/Short PCR separately in the source data). However, from the options net OI data we can infer DII's options sentiment directionally. The DII Put Long position rose marginally by +68 contracts while Call Shorts rose by +215 contracts — these two moves together suggest a mildly defensive tilt, consistent with the futures position reduction seen today. The absence of a published DII Long PCR and Short PCR means we cannot make the same numerical ratio comparison as with FII or Pro/Client, but the options architecture confirms the overall direction: DIIs are not aggressively bullish in options, and the addition of call shorts reinforces a near-term upside-cap view at current index levels.
- Call OI net deteriorated from +4,110 to +3,895 (net change -215) — DII Call Longs were unchanged at 5,176 (chg 0, [Long Flat - Low Vol]) while Call Shorts rose from 1,066 to 1,281 (+215, +20.17%, [Short Buildup - Avg Vol]). Put OI net improved marginally from +32,039 to +32,107 (net change +68) — Put Longs rose from 32,079 to 32,147 (+68, [Long Buildup - Avg Vol]) while Put Shorts held unchanged at 40 (chg 0, [Short Flat - Low Vol]). The architecture here is a net long put + marginal net long call overlay, where the dominant position is a large put long book of 32,147 contracts providing downside protection, while the call side is small (net long 3,895 contracts, shrinking as call shorts are added). The Avg Vol tag on the Call Short addition of +215 contracts suggests DII is deliberately writing call premium at resistance levels, a classic range-income or capping strategy. The tiny put short book of just 40 contracts confirms DII is not writing downside away — they are retaining their protective put structure intact.
- Synthesis — DII Defensive Long with Systematic Hedge Maintenance: DIIs today tell a story of a long-biased participant becoming incrementally more defensive without reversing their fundamental bullish bias. The futures net long of +11,369 (down from +13,287) shows a managed reduction — not a panic exit — while the call short addition of +215 contracts at Avg Vol suggests disciplined covered-call writing to generate income at perceived resistance. The massive put long book of 32,147 contracts is the most important DII data point — this is a clear insurance position that DIIs are maintaining and marginally growing (+68 today), which means they expect some near-term volatility or downside risk despite holding net long futures. Comparing to the previous session, the DII net futures moved from +13,287 to +11,369 — a clean -1,918 reduction — which is the largest single-session directional shift for DIIs in recent data, suggesting they are responding to the same macro caution that FIIs are expressing through their massive short book. The overall DII posture can be described as a long futures + long put protective collar with call writing — classic institutional equity portfolio management during uncertain conditions. Notably, DIIs stand in contrast to FIIs: where FIIs hold a 7.99:1 gross short futures book, DIIs remain net long at 1.37:1, making them the natural counterweight to FII bearishness in futures.
- Forward: Watch whether DII futures net long drops below +10,000 contracts in tomorrow's session — if the short buildup continues at Avg Vol while long additions remain Low Vol, the net long position will breach this psychologically significant threshold and signal a more decisive defensive rotation. If instead DII futures net stabilises above +11,000 and their put long book grows above 33,000 contracts, it would confirm maintained conviction in the structural long thesis with hedging overlay rather than outright capitulation. The key watch on the options side is whether DII call shorts grow from 1,281 toward 2,000+ — such expansion would signal DII actively writing resistance at current index levels, providing additional evidence of a near-term range-cap view.
Pro Aggressively Neutral-to-Bullish — Massive Call Long Buildup and Short Covering, Options Net Flip
- Futures net deteriorated from +15,819 to +14,627 (net change -1,192 contracts). Pro Long futures fell from 48,193 to 46,273 (-1,920, -3.98%, [Long Unwinding - Low Vol]) while Short futures also fell from 32,374 to 31,646 (-728, -2.25%, [Short Covering - Low Vol]). Both legs carry Low Vol confirmation tags, meaning neither the long reduction nor the short cover was done with conviction — this was a thin, risk-off squaring of positions in futures, likely ahead of an anticipated big options move. The gross long-to-short ratio is 1.46:1 (46,273 longs vs 31,646 shorts), which remains net long but shrinking. The simultaneous long unwinding and short covering at Low Vol is characteristic of professional desks reducing gross futures exposure to free up margin capital for a large options repositioning — and the options data today confirms exactly this dynamic in dramatic fashion.
- Long PCR rose from 0.89 to 0.97 (+8.67%) and Short PCR surged from 0.73 to 0.94 (+28.44%). A Long PCR of 0.97 means Pros now hold nearly equal quantities of put longs and call longs — this represents a sharp shift from their historical call-dominant positioning, and the +8.67% single-session move is significant. The Short PCR explosion from 0.73 to 0.94 (+28.44%) is the most dramatic move of any participant today — this means Pros were writing puts at an accelerating pace relative to calls on their short side, moving toward near-parity. A Short PCR approaching 1.0 on the short book means Pros are writing roughly equal puts and calls — consistent with a delta-neutral strangle or straddle construction. Together, the rising Long PCR and the surging Short PCR paint a picture of Pros aggressively positioning for a volatility event or a large directional move in either direction, with put structures being the dominant instrument of the day.
- Call OI net flipped dramatically from -74,441 to +73,689 (net change +148,130) — Pro Call Longs surged from 1,079,067 to 1,109,513 (+30,446, +2.82%, [Long Buildup - Avg Vol]) while Call Shorts collapsed from 1,153,508 to 1,035,824 (-117,684, -10.20%, [Short Covering - Avg Vol]). This is the single largest intraday options repositioning across all participants today — a net swing of +148,130 contracts in calls alone, flipping Pros from net short calls to net long calls in one session. Put OI net fell from +119,733 to +103,240 (net change -16,493) — Put Longs surged from 964,885 to 1,078,081 (+113,196, +11.73%, [Long Buildup - Avg Vol]) while Put Shorts also surged from 845,152 to 974,841 (+129,689, +15.35%, [Short Buildup - Avg Vol]). The net result is net long calls (+73,689) + net long puts (+103,240) — this is a textbook long straddle or strangle architecture, where Pros are positioned to profit from a large move in either direction.
- Synthesis — Pro Explosive Long Straddle / Volatility Long Architecture: Today's Pro data contains the most dramatic single-session repositioning of any participant. The call net flip from -74,441 to +73,689 (a swing of +148,130 contracts) combined with a large put long net of +103,240 and the Short PCR surging to 0.94 collectively describe a professional desk that has made a high-conviction bet on elevated realised volatility in the near term. The simultaneous addition of +113,196 put longs and +129,689 put shorts on the put side, combined with massive call short-covering of -117,684 and call long addition of +30,446, is the fingerprint of a delta-neutral options book being constructed around current index levels. Pros appear to be buying both sides of the market (long calls + long puts = long gamma, long vega) while the VIX is at a low of 10.68 — this is the classic 'buy volatility when it's cheap' strategy, anticipating a snap in either direction. The Low Vol tag on futures reductions confirms they freed up margin from futures to fund this large options position. Comparing to the previous session where Pros were net short calls at -74,441, today's flip to +73,689 is a complete architectural reversal — this is not an incremental adjustment but a deliberate strategic rotation. If the anticipated move is upward, their long call book profits; if downward, the long put book profits — Pros have positioned themselves to win from either scenario.
- Forward: The critical trigger for Pro's thesis is a sustained move in India VIX above 12.00 — if VIX snaps back from 10.68 toward 12+, the long straddle/strangle book that Pros have built today will show immediate mark-to-market gains on the vega component, validating their volatility-long thesis. If instead VIX continues to compress toward 9.50 or below, Pros will face theta decay on both long legs simultaneously and may be forced to unwind — watch whether Pro Call Longs drop back below 1,080,000 contracts or Put Longs drop below 980,000 contracts as early warning signals of unwinding. The key level to watch in the underlying is 24,000 on Nifty (CE resistance) — a break above this with volume would force Pro call longs into profit and likely trigger further short-covering from FIIs, creating a compounding upside catalyst.
Client Cautiously Bullish via Futures, Aggressively Defensive in Options — Massive Put Long Surge
- Futures net improved from +205,996 to +209,842 (net change +3,846 contracts). Client Long futures were nearly unchanged at 261,701 (prev 261,619, +82, +0.03%, [Long Buildup - Low Vol]) while Client Short futures fell from 55,623 to 51,859 (-3,764, -6.77%, [Short Covering - Low Vol]). Both tags are Low Vol, meaning the futures net improvement was driven by quiet short-covering rather than aggressive new long additions — Clients did not initiate fresh longs with conviction but did remove shorts. The gross long-to-short ratio stands at 5.05:1 (261,701 longs vs 51,859 shorts), a dominant net long position that makes Clients the largest net-long futures participant by a wide margin. This is a structural characteristic of retail-dominated client accounts — persistent futures long bias — but the short-covering today without new long addition suggests caution rather than aggressive bullishness. Compared to FII (7.99:1 gross short), Clients are the natural opposing structural force in futures, and their removal of shorts today marginally extends the disconnect between these two camps.
- Long PCR surged from 0.63 to 0.77 (+21.30%) and Short PCR rose from 0.94 to 1.02 (+8.83%). The Long PCR jump from 0.63 to 0.77 is the largest single-session move in Long PCR across all participants today — Clients are now holding 77 put longs for every 100 call longs, up sharply from 63 in the previous session. This is a significant defensive rotation: Clients were previously call-dominant on their long side and are rapidly building put-long protection while retaining call longs. The Short PCR crossing 1.00 (from 0.94 to 1.02) means Clients are now writing slightly more puts than calls on their short side — a bullish overlay (writing puts = expecting the market to hold or rise from current levels). The combination of a rising Long PCR (buying protection) and a Short PCR above 1.00 (writing put premium) creates an internally complex and slightly contradictory picture: Clients are simultaneously buying put protection (defensive) and writing puts (income/bullish) — suggesting different sub-accounts or strategies within the Client cohort are taking opposing options views.
- Call OI net deteriorated from +382,537 to +225,870 (net change -156,667) — Client Call Longs fell from 3,751,431 to 3,669,328 (-82,103, -2.19%, [Long Unwinding - Avg Vol]) while Client Call Shorts rose from 3,368,894 to 3,443,458 (+74,564, +2.21%, [Short Buildup - Avg Vol]). Put OI net improved from -801,821 to -716,258 (net change +85,563) — Client Put Longs surged from 2,367,385 to 2,808,996 (+441,611, +18.65%, [Long Buildup - Avg Vol]) while Client Put Shorts also rose from 3,169,206 to 3,525,254 (+356,048, +11.23%, [Short Buildup - Avg Vol]). The dominant story in Client options is the +441,611 put long addition — the single largest absolute contract addition across all participants and all option types today. Despite this massive put buying, Clients remain net short puts (-716,258) because their existing put short book is even larger. The overall options architecture is net long calls (+225,870) shrinking + net short puts (-716,258) partially recovering — describing a participant that has been predominantly short volatility and is now urgently buying put protection to hedge a deteriorating risk profile.
- Synthesis — Client Mass Put-Buying Hedge on a Structurally Long Book: Clients today executed the largest single options repositioning of any participant — adding +441,611 put longs in a single session — and this must be read against their structural context. They are the dominant net-long futures participant (+209,842 net) and have historically been net short puts (writing put premium for income), but today's massive put-long surge signals that retail and semi-institutional Clients are rapidly pivoting to protect their long book. The simultaneous call long unwinding (-82,103) and call short addition (+74,564) — producing a net call deterioration of -156,667 — confirms Clients are no longer aggressively bullish on the upside and are reducing call exposure at current resistance levels. The short PCR crossing 1.02 tells us the put-writing sub-segment of the Client cohort is still active (selling puts to collect premium), creating a fascinating split: one group of Clients is buying puts for protection while another is selling puts for income — both responding to the same market conditions but with opposing views on downside probability. Comparing to the previous session where Client put net was -801,821, the improvement to -716,258 (+85,563) on the back of massive buying confirms this is an accelerating defensive rotation, not a one-off. The contrast with FII is stark: FIIs are structurally bearish via futures shorts and long puts as a professional hedge, while Clients are structurally bullish via futures longs but now scrambling to buy put protection — this asymmetry is a classic late-stage hedging dynamic that often precedes meaningful near-term volatility.
- Forward: The key trigger for Client positioning is whether their Put Long book — which jumped to 2,808,996 contracts today — continues to expand above 3,000,000 contracts in the next session. If Client put longs cross 3 million while futures net stays above +205,000, it would confirm a full-scale protective hedge-buying event (institutions and retail both protecting longs simultaneously), which is a contrarian signal that the downside may be getting over-priced and the actual correction risk is lower than feared. Conversely, if Client Call Longs fall further below 3,600,000 contracts and futures net long starts declining from +209,842 toward +190,000, it would signal Clients are beginning to unwind the structural long itself — not just hedging it — which would represent a more serious bearish development aligned with FII's structural short. Watch the 23,000 PE support strike on Nifty — Client put buying is concentrated around this floor, and any expansion of Client put longs at strikes closer to spot (23,500–23,800 range) would indicate they expect a near-term dip rather than a minor technical correction.
Bull vs Bear Strength by Participant
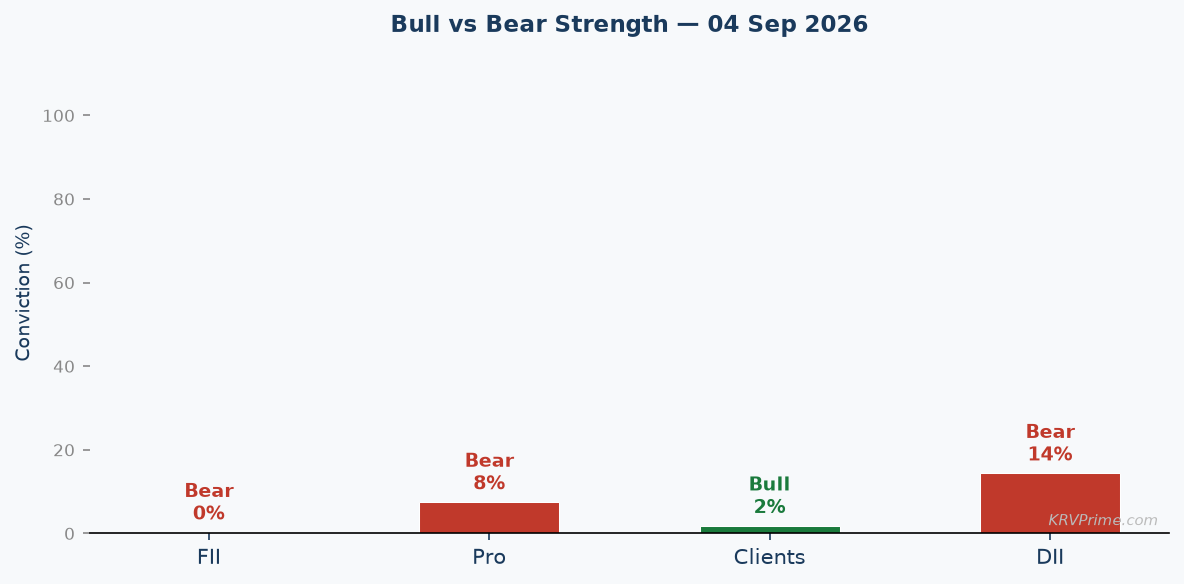
FII Structurally Bearish 82% ▼▼ | Clients Bullish / Defensively Hedged 55% ▲ | Pro Volatility Long / Neutral Direction 50% ▶ | DII Mildly Bearish / Reducing Long 60% ▼ |
Conclusion — Market Outlook for Tomorrow (05 Sep 2026)
The structural picture for 05 Sep 2026 is one of cautious bearish pressure beneath a fragile surface calm. FIIs maintain an overwhelming 7.99:1 gross short-to-long futures ratio with a net short of -235,838 contracts, and their Long PCR of 1.91 confirms this is a multi-leg bearish architecture — not a simple hedge. DIIs are incrementally reducing their net long position (from +13,287 to +11,369) with Avg Vol short additions, suggesting even the traditionally bullish domestic institutional camp is turning cautious. Clients present the most complex picture: they remain the largest net-long futures participant at +209,842, but their single-session addition of +441,611 put longs is the largest defensive repositioning of any participant in today's data — signalling that retail and semi-institutional money is hedging long book risk at an accelerating pace. The Pro desk's dramatic flip from net short calls (-74,441) to net long calls (+73,689) — a swing of +148,130 contracts — combined with their large put long book of +103,240 is the clearest architectural signal that sophisticated money anticipates a near-term volatility event, direction unspecified.
The overall PCR rising from 0.82 to 0.93 (+13.95%) is a meaningful shift — put OI expanded by +1,147,650 contracts (+13.00%) in a single session while call OI marginally contracted by -90,449 contracts (-0.84%). This put OI surge is primarily Client-driven (+441,611 put longs) and FII-driven (+88,088 put shorts, i.e. written puts), with Pro adding +113,196 put longs — confirming broad-based engagement with the put side. India VIX collapsing from 11.34 to 10.68 (-5.80%) simultaneously with this massive put buying creates a technically unusual divergence: typically, large put buying would push VIX up, but here the VIX is compressing — suggesting the put buying is concentrated in strikes far enough from spot that it is not driving near-term implied vol, or that put sellers (FIIs writing +88,088 puts, Clients writing +356,048 puts) are absorbing supply and capping the VIX. A VIX at 10.68 represents deep complacency territory, which is historically a precursor to volatility expansion rather than further compression.
The bearish thesis would be challenged if FII futures net improves above -230,000 contracts (short-covering begins) while the overall PCR climbs above 1.05 (put buyers overwhelming call writers) — that combination would signal an oversold condition where the market can snap back sharply toward the 24,000 CE resistance (Nifty week) and then 25,000 CE resistance (Nifty month). The bearish thesis is confirmed if FII futures net deteriorates further below -237,000, VIX begins recovering above 11.50, and Client put longs continue expanding — in that scenario, the 23,000 PE support (Nifty week and month) becomes the primary structural floor being defended by Client and DII put long books, and any breach of that level would trigger a sharp acceleration to the downside.
Scenario 1 — Bull case:
If FII futures net short improves toward -230,000 (covering approximately 5,800 shorts) accompanied by an Avg or High Vol tag, and the overall PCR holds above 0.95 confirming sustained put-floor support, the market could squeeze toward the 24,000 Nifty CE resistance and then the 57,500 BankNifty CE resistance. A VIX compression below 10.00 in this scenario would confirm premium sellers in control and further reduce hedging demand, adding fuel to the squeeze. Clients reducing their put-long book below 2,600,000 contracts while holding futures longs above +205,000 would confirm confidence returning to the long side.
Scenario 2 — Bear case:
If FII futures net worsens below -237,000 with an Avg Vol tag on the short buildup, and the overall PCR retreats below 0.85 as put longs are monetised and closed, downside pressure intensifies toward the 23,000 Nifty PE support (week and month OI floor) and 57,000 BankNifty PE support. A VIX recovery above 12.00 from today's low of 10.68 would validate the Pro long straddle thesis and signal that realised volatility is beginning to match implied volatility fears. Client futures net declining below +195,000 contracts (long unwinding begins, not just short-covering) would be the clearest confirmation that retail money is capitulating from the structural long — the most bearish possible signal in the Client data.
Key Resistance Nifty 24,000 (Week CE) and 25,000 (Month CE) — these are the primary call OI resistance strikes where FIIs hold a net short call book of -303,454 contracts and Clients are building call shorts (+74,564 today). BankNifty 57,500 (Month CE) is the secondary resistance where call writers are concentrated. Pro's massive call short-covering (-117,684) at current levels suggests this resistance is being tested but not yet broken — a sustained close above 24,000 Nifty would be significant. | Key Support Nifty 23,000 (Week and Month PE) — this is the primary put OI support strike defended by Client put longs (2,808,996 contracts, up +441,611 today) and DII put longs (32,147 contracts). BankNifty 57,000 (Month PE) and Sensex 75,000 (Week and Month PE) are the corresponding support floors. FII net long puts of +580,911 provides an additional structural layer at and below this level, making 23,000 Nifty the most heavily defended support in today's data. | Trigger to Watch India VIX crossing above 12.00 from today's close of 10.68 — this is the single most important trigger for tomorrow. If VIX recovers sharply, it validates Pro's long straddle architecture (+148,130 net call swing + +103,240 put long net), signals that the current low-vol complacency is breaking, and will force FII put writers (-88,088 puts written today) to defend or cover — potentially creating a self-reinforcing volatility expansion event. Simultaneously, watch overall PCR: a drop back toward 0.85 would indicate put longs being monetised (market falling, puts gaining), confirming the bear scenario is playing out. |