
Market Participants Analysis dated 05.10.2026
KRVPrime — Daily Market Outlook
Key Market Signals — Data: 05 Oct 2026
NIFTY 50 22,555.75 ▲ +133.80 (+0.60%) | BANK NIFTY 54,714.10 ▲ +263.35 (+0.48%) | SENSEX 72,382.47 ▲ +472.77 (+0.66%) |
OVERALL PCR 0.93 ▲ +0.15 (+19.24%) PCR surged from 0.78 to 0.93 — put OI build outpacing calls; approaching neutral zone with latent support forming. | INDIA VIX 14.78 ▲ +0.32 (+2.21%) VIX rising on an up-day signals options traders are buying protection despite index gains — caution warranted. | TOTAL OI CHANGE 48,797,800 ▲ +3,590,592 (+7.94%) Large OI expansion led by put additions — significant fresh positioning entering the market. |
FUTURES OI 866,026 ▼ -4,756 (-0.55%) Marginal futures OI contraction on a positive close suggests short-covering rather than fresh long accumulation. | CALL OI CHANGE 12,146,161 ▲ +625,185 (+5.43%) Call OI expanding — fresh resistance supply being written at higher strikes, capping upside. | PUT OI CHANGE 11,255,014 ▲ +2,301,878 (+25.71%) Massive put OI addition of +25.71% — largest cross-segment OI move today, reflecting broad hedging demand. |
Participant-wise Key Points
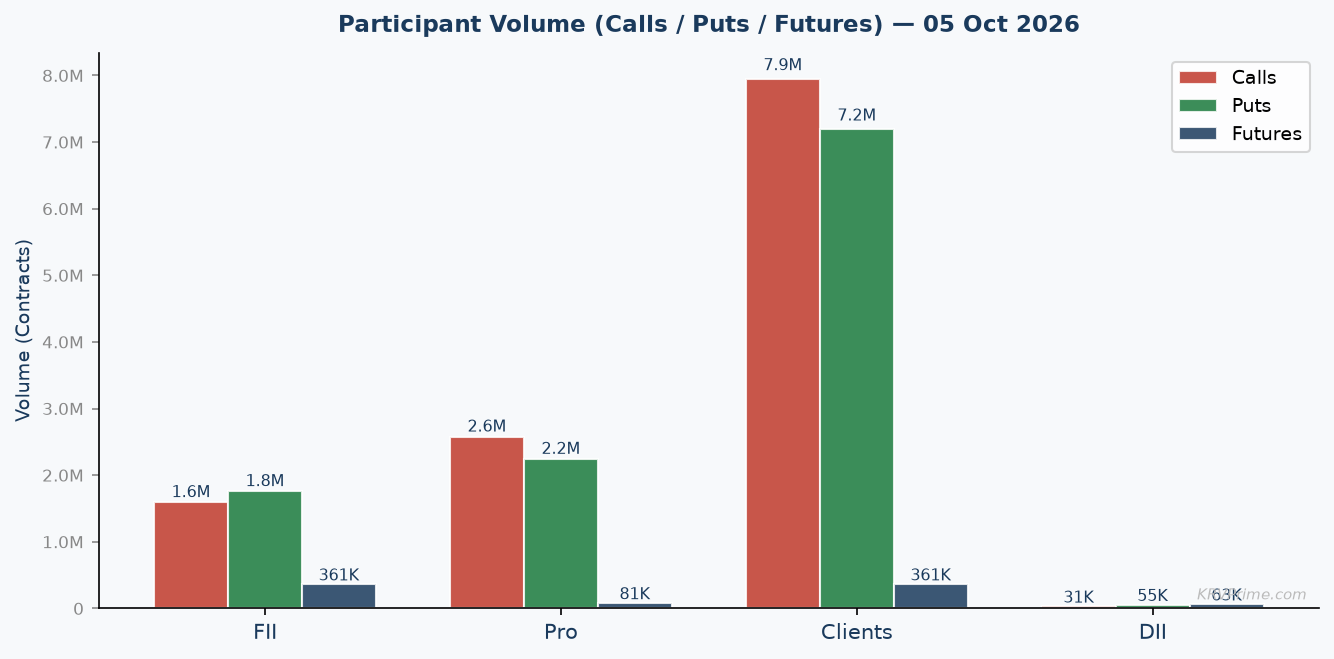
FII Cautiously Bearish — Covering Shorts but Aggressively Hedging via Puts
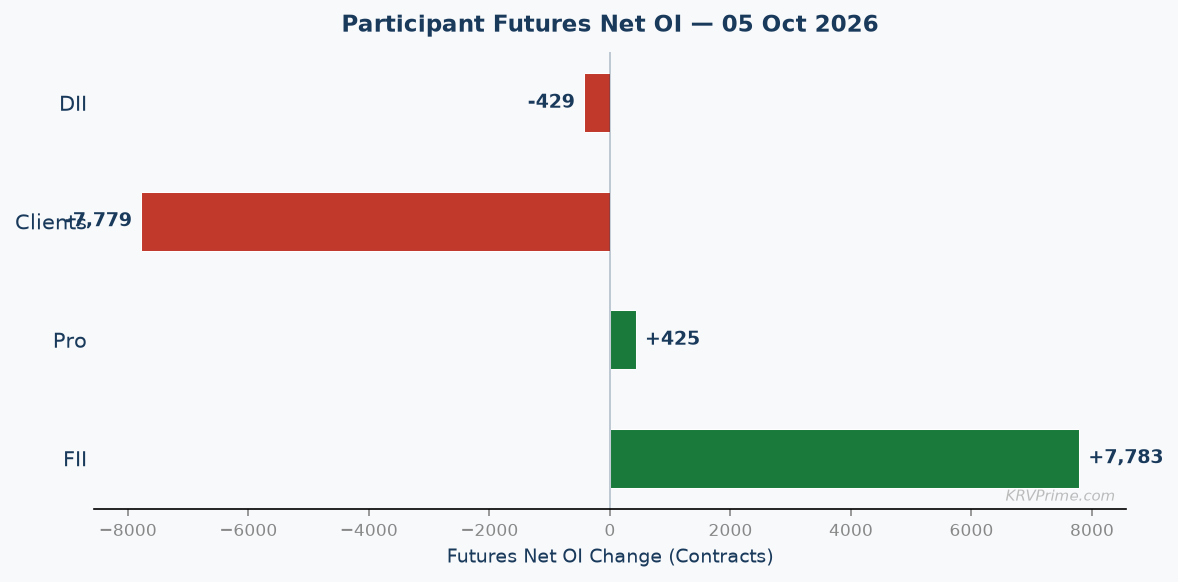
- Futures net improved from -310,174 to -302,391 (net change +7,783 contracts, a reduction in net short exposure). The Long side declined from 29,605 to 29,117 (chg -488, -1.65%) tagged [Long Unwinding - Low Vol], indicating FIIs are trimming marginal long positions with low conviction — this is not aggressive selling but rather a passive reduction. The Short side fell from 339,779 to 331,508 (chg -8,271, -2.43%) tagged [Short Covering - Low Vol], which means FIIs are closing shorts tentatively, consistent with the market's +0.60% gain forcing partial cover. The gross short-to-long ratio remains dominant at 11.38:1 (331,508 shorts vs 29,117 longs) — this is not a neutral futures book but an overwhelmingly directional short position, and today's low-volume short-covering does nothing to change that structural bearish posture. The Low Vol tags on both legs confirm neither the long trim nor the short cover carries high conviction — FIIs are adjusting marginally at the edges, not repositioning fundamentally.
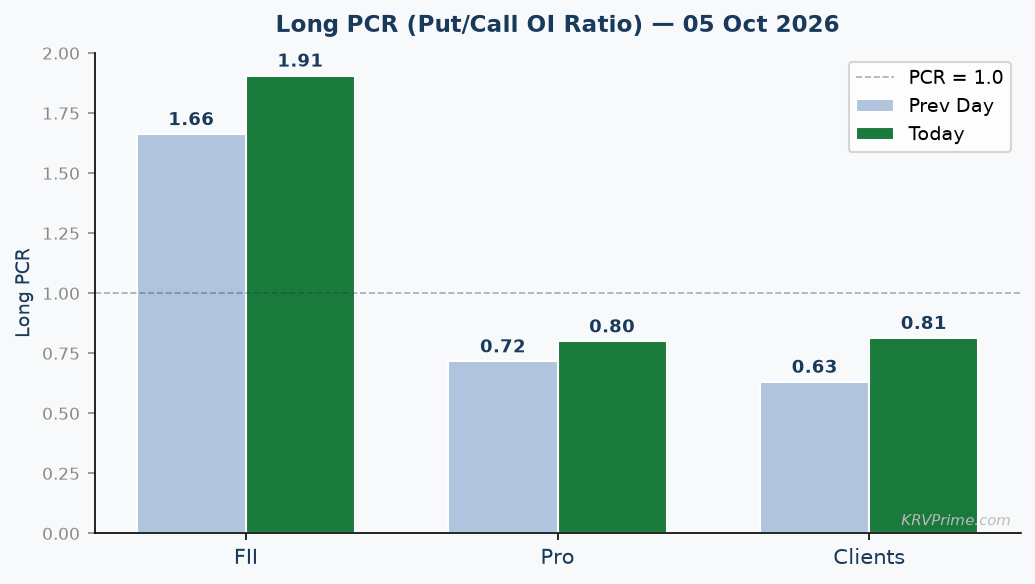
- Long PCR rose from 1.66 to 1.91 (+14.65%) and Short PCR rose from 0.41 to 0.60 (+46.91%). A Long PCR of 1.91 means FIIs now hold 91% more put longs than call longs — an extremely defensive hedge posture that confirms FIIs are actively protecting against a downside move, whether on a large equity book or as an outright directional bearish expression through options. This is the sharpest one-day Long PCR increase among all participants today and reflects the +5.42% High Vol long put buildup seen in the options data. The Short PCR surging from 0.41 to 0.60 (+46.91%) is equally significant — FIIs have dramatically increased their put writing on the short side, meaning they are now writing 60 put contracts for every 100 call contracts they short, versus 41 per 100 yesterday. Rising Short PCR in isolation could suggest a bullish bias (writing puts), but in the context of their futures short of -302,391 and a Long PCR of 1.91, this rising Short PCR most likely represents premium collection on puts they believe will expire worthless in the near term — a range-income overlay on an otherwise bearish book.
- Call OI net moved from -431,465 to -365,731 (chg +65,734) with Long side at 616,526 (prev 670,483, chg -53,957, -8.05%) tagged [Long Unwinding - Avg Vol] and Short side at 982,257 (prev 1,101,948, chg -119,691, -10.86%) tagged [Short Covering - Avg Vol]. FIIs are closing both call longs and call shorts in tandem — an Avg Vol tag on both legs confirms routine de-grossing rather than a strategic directional shift on calls. Put OI net moved from +666,578 to +588,315 (chg -78,263) with Long side at 1,175,238 (prev 1,114,773, chg +60,465, +5.42%) tagged [Long Buildup - High Vol] and Short side at 586,923 (prev 448,195, chg +138,728, +30.95%) tagged [Short Buildup - High Vol]. Both High Vol tags on the put side confirm deliberate, high-conviction positioning — FIIs are simultaneously building put longs (bearish hedge) and aggressively writing puts (premium income), creating a bull put spread or short put collar architecture on the downside, while the net put long of +588,315 remains their dominant options exposure. Combined with net short calls, the overall options architecture is a synthetic short with income overlay — net long puts + net short calls = directional downside positioning with premium collection to fund the carry.
- Synthesis — FII Covered-Short with Escalating Put Hedge: FIIs today present a nuanced but ultimately bearish picture — their futures book remains a massive -302,391 net short at an 11.38:1 gross short-to-long ratio, and the Low Vol short-covering is entirely explained by the market's +0.60% intraday move forcing partial cover rather than any genuine thesis change. The critical signal is in the options: the High Vol Long Buildup in puts (+60,465 contracts at 1,175,238 long) combined with the Long PCR rising to 1.91 confirms that FIIs spent today aggressively adding put protection — this is not routine hedging but conviction buying of downside insurance. The simultaneous High Vol Short Buildup on puts (+138,728 at 586,923 short) adds complexity — FIIs are writing lower-strike puts against their long puts, consistent with a bear put spread construction where maximum profit is at a defined lower level. The overall architecture of net short futures (-302,391) + net long puts (+588,315) + net short calls (-365,731) is a textbook multi-leg directional short — FIIs are positioned for a decline, have funded it with call and put premium, and today's partial futures short-covering was marginal and low conviction. Compared to yesterday, the put long book is now larger and more aggressively structured, signalling FIIs are accelerating their downside thesis, not moderating it.
- Forward: The key watch for tomorrow is whether FII futures net short improves beyond -300,000 (a further reduction toward -290,000 range) on the back of sustained market strength — that would signal genuine short-covering pressure and a potential near-term squeeze. If instead FII futures net short deepens back toward -310,000 or worse while VIX continues rising above 14.78, it confirms their bearish architecture is being reinforced and the upside in Nifty is likely capped at the 23,000 weekly CE resistance. Watch FII Long PCR — if it crosses 2.00 tomorrow, it would be the clearest signal that FIIs are treating any market strength purely as an opportunity to add more downside hedges.
DII Structurally Bullish — Aggressively Adding Calls and Puts as Protective Longs
- Futures net moved from +33,257 to +32,828 (net change -429 contracts, a marginal reduction). The Long side declined from 48,119 to 47,700 (chg -419, -0.87%) tagged [Long Unwinding - Low Vol], indicating a very minor trimming of long futures exposure with minimal volume conviction — this is not a meaningful position change. The Short side rose from 14,862 to 14,872 (chg +10, +0.07%) tagged [Short Buildup - Low Vol], an almost negligible addition of just 10 contracts with very low volume — this confirms DIIs are essentially holding their futures book flat. The gross long-to-short ratio is 3.21:1 (47,700 longs vs 14,872 shorts), which is a moderately bullish futures positioning consistent with DII's traditional role as a net equity buyer in the Indian market. The Low Vol tags on both legs confirm today's futures activity was largely passive — DIIs are not aggressively repositioning on futures but are maintaining their structural long bias with minimal disruption.
- DII PCR data is not reported in the participant-level data — DIIs do not have a separately published Long PCR or Short PCR figure in today's data. However, we can infer directional intent from their options activity: the High Vol Long Buildup in both calls and puts signals that DIIs are buying options protection comprehensively across both strikes, suggesting they are either hedging a large equity book (institution-style) or expressing a view that volatility will expand. The absence of PCR data for DIIs is a structural data constraint — sentiment must be derived purely from the OI direction and volume tags on their calls and puts. Given the +220.44% surge in call longs and +34.13% buildup in put longs, DIIs are clearly adding to optionality on both sides, which is more consistent with a long straddle/protective hedge posture than a directional bet.
- Call OI net moved from +4,976 to +23,886 (chg +18,910) with Long side surging from 8,533 to 27,343 (chg +18,810, +220.44%) tagged [Long Buildup - High Vol] and Short side declining marginally from 3,557 to 3,457 (chg -100, -2.81%) tagged [Short Covering - Low Vol]. The +220.44% call long buildup at High Vol is the single most dramatic positioning change across all participants today — DII bought calls in massive volume, which either reflects a directional bullish bet on the index or a hedge against a short-equity position, though the latter is unlikely given their net long futures. Put OI net moved from +39,526 to +53,315 (chg +13,789) with Long side rising from 40,402 to 54,191 (chg +13,789, +34.13%) tagged [Long Buildup - High Vol] and Short side flat at 876 (chg 0, +0.00%) tagged [Short Flat - Low Vol]. The architecture is clearly net long calls (+23,886) + net long puts (+53,315) — this is a long strangle or protective collar structure, where DIIs are buying upside participation while simultaneously securing downside protection via put longs. This architecture is distinctly different from FIIs and confirms DIIs are bullish on the underlying but are hedging the tail risk of a sharp reversal.
- Synthesis — DII Bullish Strangle with Structural Long Bias: DIIs present the clearest bullish-but-hedged picture among institutional participants today. Their futures book at +32,828 net long with a 3.21:1 long-to-short gross ratio provides the directional anchor — DIIs are net buyers of the market. The explosive +220.44% High Vol call long buildup (18,810 new contracts added to reach 27,343) confirms DIIs are expressing upside conviction through options too, consistent with the view that today's +0.60% market gain is the beginning of a continuation rather than a fade. Simultaneously, the +34.13% High Vol put long buildup (+13,789 contracts to 54,191) tells us DIIs are not blind bulls — they are buying downside insurance at scale, aware that VIX is rising and FII shorts remain dominant. The combined net long call + net long put architecture is a long strangle, which profits if the market moves sharply in either direction — DIIs appear positioned for a volatility expansion while maintaining a slight upward directional bias through their futures longs. In direct contrast to FIIs (who are net short futures at -302,391), DIIs are net long at +32,828 — the two institutional groups are on opposite sides, a divergence that historically resolves in the direction of sustained OI — and today's High Vol tags on DII options suggest they are the more actively managed and conviction-driven participant today.
- Forward: The critical watch for DII tomorrow is whether their call long position (currently 27,343 contracts) continues to expand — a further buildup above 35,000 in call longs with High Vol confirmation would validate an aggressive bullish directional stance and could presage a move toward the 23,500 monthly CE resistance. If instead DII call longs are unwound without replacement, it would suggest today's burst was event-driven or expiry-positioning rather than sustained conviction, and the strangle thesis would weaken. Watch DII futures net — a dip below +30,000 would signal that their structural long bias is being eroded and their net long futures position is no longer supportive of the bullish case.
Pro Bifurcated — Bullish Futures Bias but Aggressively Shorting Puts for Range Premium
- Futures net improved marginally from +27,105 to +27,530 (net change +425 contracts). The Long side rose from 51,101 to 54,509 (chg +3,408, +6.67%) tagged [Long Buildup - Low Vol], indicating Pros are adding to their futures long book but with low volume conviction — this is tentative rather than aggressive accumulation. The Short side also rose from 23,996 to 26,979 (chg +2,983, +12.43%) tagged [Short Buildup - Low Vol], meaning Pros are simultaneously adding both longs and shorts on futures — a two-sided futures expansion that nets out to a marginal +425 change. The gross long-to-short ratio is 2.02:1 (54,509 longs vs 26,979 shorts), mildly bullish in isolation but the simultaneous build on both sides suggests Pros are expanding gross exposure rather than expressing a clean directional view. Low Vol tags on both legs are consistent with algorithmic or market-making activity — Pros (proprietary desks) often take both sides as part of hedging their larger options book, and today's bifurcated futures build is likely linked to their massive put short expansion on the options side.
- Long PCR rose from 0.72 to 0.80 (+11.63%) and Short PCR surged from 0.68 to 0.96 (+40.55%). A Long PCR of 0.80 means Pros hold 80 put longs for every 100 call longs — broadly balanced on the long side with a slight lean toward put protection, but far less defensive than FII's 1.91. The bigger story is the Short PCR surge from 0.68 to 0.96 — Pros are now writing 96 put contracts for every 100 call contracts on the short side, approaching a 1:1 short put-to-call ratio. This dramatic +40.55% rise in Short PCR over a single session is the defining signal for Pros today: they have aggressively shifted toward writing puts relative to calls, which is classically consistent with either a range-neutral view (selling both sides for premium) or a mild bullish lean (believing puts will expire worthless). The Long PCR rising simultaneously suggests Pros are also hedging with some put longs — the net effect is a complex strangle sell overlay on top of a lightly net-long futures book.
- Call OI net moved from +131,005 to +222,584 (chg +91,579) with Long side rising from 1,337,674 to 1,397,750 (chg +60,076, +4.49%) tagged [Long Buildup - Avg Vol] and Short side declining from 1,206,669 to 1,175,166 (chg -31,503, -2.61%) tagged [Short Covering - Avg Vol]. Pros are buying calls and simultaneously covering call shorts — an Avg Vol tag on both confirms routine, measured activity rather than urgent repositioning. The call OI net expanding from +131,005 to +222,584 means Pros are increasingly net long calls — adding upside optionality. Put OI net swung from +137,044 to -6,533 (chg -143,577) with Long side rising from 958,371 to 1,117,777 (chg +159,406, +16.63%) tagged [Long Buildup - High Vol] and Short side surging from 821,327 to 1,124,310 (chg +302,983, +36.89%) tagged [Short Buildup - High Vol]. Both put legs carry High Vol tags — this is high-conviction positioning on both sides of the put book. The put OI net turning negative to -6,533 (effectively flat but just net short) from +137,044 confirms Pros have dramatically shifted: they have written 302,983 new put contracts while also buying 159,406, producing a near-neutral put net but with a massive gross book. The combined architecture of net long calls (+222,584) + near-flat puts (-6,533) is a synthetic long tilt with put spread overlay — Pros are positioned for upside with the put short book serving as premium income to finance the call longs.
- Synthesis — Pro Desk Synthetic Long with Put-Writing Premium Engine: Pro desks today have constructed one of the more complex cross-leg strategies visible in the data. On futures, they are marginally net long at +27,530 with a 2.02:1 long-to-short ratio — a mild directional long. On calls, they have aggressively expanded their net long to +222,584 by buying 60,076 new call contracts while covering 31,503 short calls — a clear upside conviction expression. On puts, the High Vol Short Buildup of +302,983 contracts (the largest single put short addition across all participants today) is Pros writing massive put premium, funded by the long put buildup of +159,406 — consistent with a bear put spread or short put vertical where they are collecting premium by selling lower-strike puts against bought higher-strike puts. The net result is a bull call spread + short put vertical combination: Pros are bullish on the market and are using the put-writing income to fund their call long book. This is a sophisticated range-bullish strategy: they make money if the market stays above support and potentially rallies — the Short PCR at 0.96 (nearly writing as many puts as calls on the short side) is the fingerprint of this put-selling engine. Compared to yesterday, Pros have sharply accelerated their put short book (from 821,327 to 1,124,310) while also adding call longs — this is a meaningful shift from yesterday's more balanced posture to today's leaning-bullish architecture.
- Forward: The key watch for Pro desks is whether the put short book continues to expand — if Pro short puts cross 1,200,000 contracts tomorrow with High Vol confirmation, it would signal the most aggressive put-selling posture in recent sessions, which historically acts as a floor for the market (market makers defending their short puts). If however the market drops sharply and Pro Short PCR reverses below 0.85, it would indicate rapid put buyback (covering the short put book), which would accelerate downside momentum. Watch the 22,000 monthly PE support — that is where Pro and FII put books are concentrated, and a breach there would trigger the most significant OI unwind of the session.
Client Aggressively Two-Sided — Massive Put Long Buildup Signals Retail Hedging Surge
- Futures net declined from +249,812 to +242,033 (net change -7,779 contracts, the largest futures net reduction among all participants today). The Long side fell from 306,566 to 301,687 (chg -4,879, -1.59%) tagged [Long Unwinding - Low Vol], indicating retail/client participants are trimming their long futures exposure in a low-conviction manner — possibly taking partial profit on the day's +0.60% gain or reducing overnight risk. The Short side rose from 56,754 to 59,654 (chg +2,900, +5.11%) tagged [Short Buildup - Low Vol], showing Clients are also adding incremental shorts simultaneously — a mixed signal that suggests some participants within the Client segment are turning cautious or setting up hedges. The gross long-to-short ratio remains dominant at 5.06:1 (301,687 longs vs 59,654 shorts) — Clients remain by far the most heavily net-long participant in futures across all groups, but today's -7,779 net change marks a measurable erosion of that structural long position. Low Vol tags on both legs suggest this is not a panic unwind or aggressive reversal — it is a cautious, tentative trimming that could simply reflect intraday profit-booking by retail participants on a positive day.
- Long PCR rose from 0.63 to 0.81 (+28.91%) and Short PCR rose from 0.93 to 1.00 (+7.64%). The Long PCR surging from 0.63 to 0.81 in a single session is the largest absolute PCR change for Clients and signals a dramatic shift in hedge posture — Clients moved from holding only 63 put longs per 100 call longs to 81 put longs per 100 call longs, a decisive tilt toward downside protection. This is particularly notable because Clients are traditionally the most directionally long participant (futures net +242,033) — the fact that they are now adding puts at near-call pace signals that even retail participants are becoming nervous about the sustainability of the rally. The Short PCR rising from 0.93 to 1.00 means Clients are now writing exactly as many puts as calls on the short side — a perfectly balanced short-side premium write that is consistent with a neutral short-strangle or income-collection strategy on options they are writing. The combined picture of Long PCR at 0.81 (defensive) + Short PCR at 1.00 (perfectly balanced) signals Clients are simultaneously building defense (buying puts) and collecting premium (writing calls and puts in equal proportion) — a complex behaviour for a traditionally directional group.
- Call OI net moved from +295,484 to +119,262 (chg -176,222) with Long side rising from 3,743,798 to 4,031,462 (chg +287,664, +7.68%) tagged [Long Buildup - High Vol] and Short side rising from 3,448,314 to 3,912,200 (chg +463,886, +13.45%) tagged [Short Buildup - High Vol]. Both call legs carry High Vol tags and both are expanding — Clients are buying and selling calls in massive volume simultaneously. The net call OI narrowing sharply from +295,484 to +119,262 despite both sides expanding is because the short side grew significantly faster (13.45% vs 7.68%) — Clients are writing more calls than they are buying, a supply-heavy action that suppresses upside. Put OI net moved from -843,148 to -635,097 (chg +208,051, an improvement toward neutral) with Long side surging from 2,363,022 to 3,280,301 (chg +917,279, +38.82%) tagged [Long Buildup - High Vol] and Short side rising from 3,206,170 to 3,915,398 (chg +709,228, +22.12%) tagged [Short Buildup - High Vol]. The +917,279 put long addition by Clients is the single largest options OI addition across all participants and instruments today — an extraordinary volume of put buying that dwarfs all other moves. Clients remain net short puts (3,915,398 short vs 3,280,301 long) but the gap narrowed dramatically from -843,148 to -635,097, confirming a meaningful shift toward put long protection. The architecture of near-neutral call net (+119,262) + improving but still net short puts (-635,097) reflects a transition from a classic call long / put short retail structure toward a more hedged, cautious positioning.
- Synthesis — Client Panic-Hedge Inflection with Retained Structural Long: Clients today represent the most instructive behavioural signal in the market. As the largest futures long (+242,033), they are structurally bullish — but today's data shows they are simultaneously buying the largest volume of put protection seen across all participants (+917,279 put longs at High Vol), which is a classic retail hedge-at-the-top or fear-of-missing-the-rally-down behaviour. The Long PCR spike from 0.63 to 0.81 (+28.91%) confirms this hedging is broad-based and urgent — not just a few sophisticated accounts but widespread put buying across the Client cohort. The simultaneous High Vol call short buildup (+463,886 at 13.45%) reflects the other side of retail behaviour: call writers trying to collect premium on strikes they believe won't be reached. The net effect is a Client book that is structurally long futures but is buying puts aggressively — this is the classic protective put or collar strategy, where the underlying equity/futures position is hedged against a downside move while upside is partially capped by call selling. Compared to yesterday, Clients have dramatically accelerated both put buying (+917,279 today vs much lower OI base) and call writing (+463,886) — suggesting a rapid shift in sentiment from outright bullish to cautiously hedged. In direct contrast to FIIs (also bearish but through futures shorts and put longs), Clients are achieving downside coverage while retaining upside through their futures longs — both groups are hedging, but via structurally different instruments.
- Forward: The critical watch for Clients is whether tomorrow's put long position continues to expand above 3,500,000 (from today's 3,280,301) with continued High Vol tagging — if it does, it signals retail participants are not done hedging and the protective put buying could act as a support floor around the 21,500 weekly PE support level (the strike at which Client put longs are concentrated). If however the put long book reverses and falls below 3,000,000 on a strong market day, it would signal put profit-booking and a removal of the protective hedge — which could allow the market to extend gains toward 23,000 weekly CE resistance without the put OI floor dampening moves. Watch the overall PCR — if it crosses 1.00 tomorrow (from today's 0.93), it would confirm that put buying has overwhelmed call supply, a classically bullish sentiment signal for medium-term market direction.
Bull vs Bear Strength by Participant
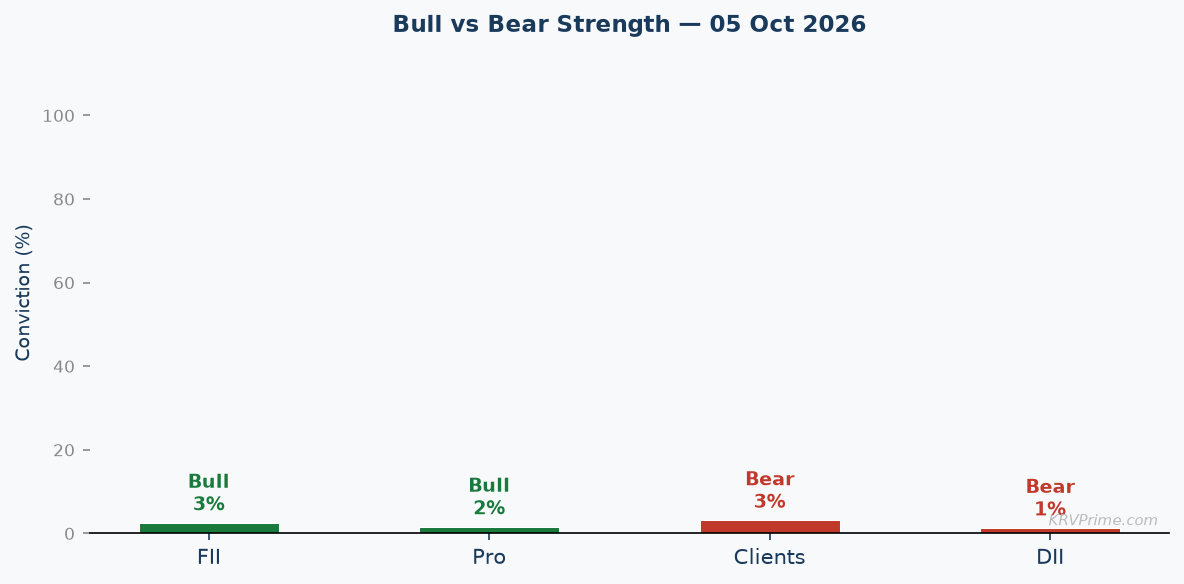
FII Strongly Bearish 82% ▼▼ | Clients Hedged Long / Cautious 55% ▶▼ | Pro Mildly Bullish / Range 60% ▲ | DII Structurally Bullish 68% ▲▲ |
Conclusion — Market Outlook for Tomorrow (06 Oct 2026)
The structural picture as of 05 Oct 2026 is one of deep inter-participant divergence with a rising undercurrent of caution despite the positive index close. FIIs remain the most consequential bear with a futures net short of -302,391 at an 11.38:1 gross short-to-long ratio — a position that has barely moved today despite the market's +0.60% gain, and which is now accompanied by an aggressively expanded put long book of 1,175,238 contracts at High Vol confirmation. DIIs sit on the opposite side with a futures net long of +32,828 at a 3.21:1 long-to-short ratio, reinforced by an extraordinary +220.44% call long buildup — the two institutional camps are in direct confrontation, with FII bears outnumbering DII bulls in gross futures contracts by nearly 9:1 (331,508 FII shorts vs 47,700 DII longs). Pro desks have taken a pragmatic middle path, constructing a synthetic bullish overlay via call longs and put shorts while maintaining a marginally net long futures book — their aggressive put-writing of +302,983 contracts at High Vol effectively creates a floor below which their book becomes vulnerable, which they will defend. Clients, despite being the largest net futures longs at +242,033, spent today frantically buying +917,279 put contracts — the largest single-session put long addition across all participants — signalling that retail sentiment is shifting from complacent long to defensively hedged.
The overall PCR surging from 0.78 to 0.93 (+19.24%) in a single session reflects this broad-based put buying frenzy — a PCR approaching 1.00 traditionally signals that markets are becoming more balanced between bulls and bears, and that a meaningful support zone is being constructed. However, the India VIX rising +2.21% to 14.78 on a positive market day is a critical divergence signal — options traders are paying more for protection even as the index gains, which historically precedes a period of elevated volatility or a sharp directional move. The total OI surge of +7.94% (predominantly driven by +25.71% put OI expansion) confirms that today's positioning was overwhelmingly about downside risk management rather than bullish participation — markets that see this kind of OI build on up-days often experience whipsaw action in the near term as competing forces (FII shorts vs Client longs) resolve. The OI Resistance at 23,000 (NIFTY weekly CE) and 23,500 (NIFTY monthly CE) remains formidable with fresh call writing from both FII (net short calls at -365,731) and Client (expanding call shorts at 3,912,200). The OI Support at 21,500 (NIFTY weekly PE) and 22,000 (NIFTY monthly PE) is now fortified by the massive put long accumulation from Clients and FIIs combined.
The thesis for a sustained bullish move requires FII futures net short to improve meaningfully — specifically, a reduction from -302,391 toward -280,000 or better with High Vol confirmation would signal genuine short-covering rather than the tentative Low Vol cover seen today. Should that occur alongside PCR crossing 1.00 and VIX retreating below 14.00, the structural setup would shift decisively bullish with a target at 23,000 weekly CE resistance. Conversely, if FII deepens shorts back toward -315,000, VIX sustains above 15.00, and the PCR fails to hold above 0.90, the bear case dominates — the existing put long infrastructure from all participants would be monetised aggressively, and the first downside magnet would be the 22,000 monthly PE support and then 21,500 weekly PE support.
Scenario 1 — Bull case:
If FII futures net short improves from -302,391 toward -280,000 with confirmed short-covering (High Vol tag replacing current Low Vol), PCR sustains above 0.95 and ultimately crosses 1.00, and VIX retreats below 14.00, the bull case activates. Pro desks defending their massive put short book of 1,124,310 contracts would amplify any upward move through delta hedging, and DII's call long book (+27,343 at High Vol) would gain significant mark-to-market. The primary target in the bull case is 23,000 NIFTY weekly CE OI resistance, beyond which 23,500 monthly CE resistance becomes the next magnet.
Scenario 2 — Bear case:
If FII futures net short deepens from -302,391 back toward -315,000 or beyond with a shift from Low Vol to High Vol Short Buildup confirmation, VIX rises above 15.50, and the overall PCR fails to hold 0.90 (reverting toward 0.78 or lower), the bear case activates. FII's High Vol put long book of 1,175,238 contracts would be aggressively monetised, Clients' 3,280,301 put longs would gain rapidly, and Pro desks' put shorts of 1,124,310 would face forced buyback — accelerating the downside. The first structural support magnet is 22,000 NIFTY monthly PE OI support, and a breach there exposes 21,500 weekly PE support where the maximum put OI concentration provides the last meaningful demand floor.
Key Resistance 23,000 (NIFTY Weekly CE OI Resistance) — FIIs hold a net short call position of -365,731 contracts concentrated at and above this level, while Client call writers have expanded their short book to 3,912,200 contracts. The combined supply from FII and Client call writers makes 23,000 the primary resistance ceiling for the week. Monthly CE resistance at 23,500 represents the next supply zone above that. | Key Support 22,000 (NIFTY Monthly PE OI Support) backed by 21,500 (NIFTY Weekly PE OI Support) — Clients hold 3,280,301 put long contracts (the largest single-session put accumulation seen today), FIIs hold 1,175,238 put longs at High Vol, and Pro desks hold 1,117,777 put longs. Combined put long concentration at these strikes creates a formidable demand floor. BankNifty 54,000 monthly PE support and SENSEX 70,000 weekly and monthly PE support corroborate the broader institutional defence zone. | Trigger to Watch Overall PCR crossing 1.00 (from today's 0.93) with VIX simultaneously retreating below 14.00 would confirm the bull case — put buying has transitioned from fear-based hedging to structural support construction. Conversely, FII futures net short deepening past -310,000 with a volume-tag shift to High Vol Short Buildup would be the definitive bear trigger, signalling FIIs are not done pressing the downside and the current rally is being treated as a selling opportunity. |