
Market Participants Analysis dated 06.10.2026
KRVPrime — Daily Market Outlook
Key Market Signals — Data: 06 Oct 2026
NIFTY 50 22,776.10 ▲ +220.35 (+0.98%) | BANK NIFTY 55,128.40 ▲ +414.30 (+0.76%) | SENSEX 73,067.81 ▲ +685.34 (+0.95%) |
OVERALL PCR 1.03 ▲ +0.10 (+10.75%) PCR rising above 1.0 signals put-side dominance — mild bullish undertone with protective hedging in play. | INDIA VIX 13.61 ▼ -1.17 (-7.90%) VIX at 13.61, falling sharply — fear dissolving, markets pricing lower risk premium into the near term. | TOTAL OI CHANGE 40,078,006 ▼ -8,719,794 (-17.87%) Massive OI reduction signals post-expiry or contract-roll unwind rather than fresh directional build. |
FUTURES OI 856,416 ▼ -9,610 (-1.11%) Futures OI marginally lower — no strong fresh directional commitment in the futures segment today. | CALL OI CHANGE 7,036,223 ▼ -5,109,938 (-42.07%) Massive call OI collapse — expiry cleanup or aggressive short-covering across the call segment. | PUT OI CHANGE 7,220,354 ▼ -4,034,660 (-35.85%) Put OI also collapsed — widespread options unwind; PCR rising despite both sides falling suggests call unwind faster. |
Participant-wise Key Points
FII Structurally Bearish — Covering Edges, Core Short Intact
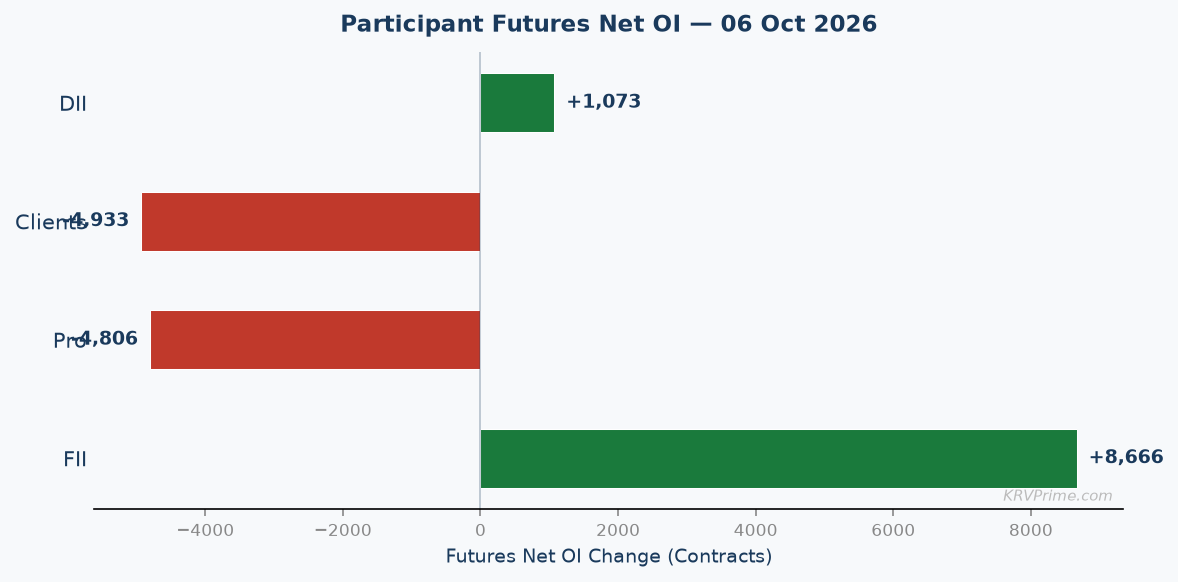
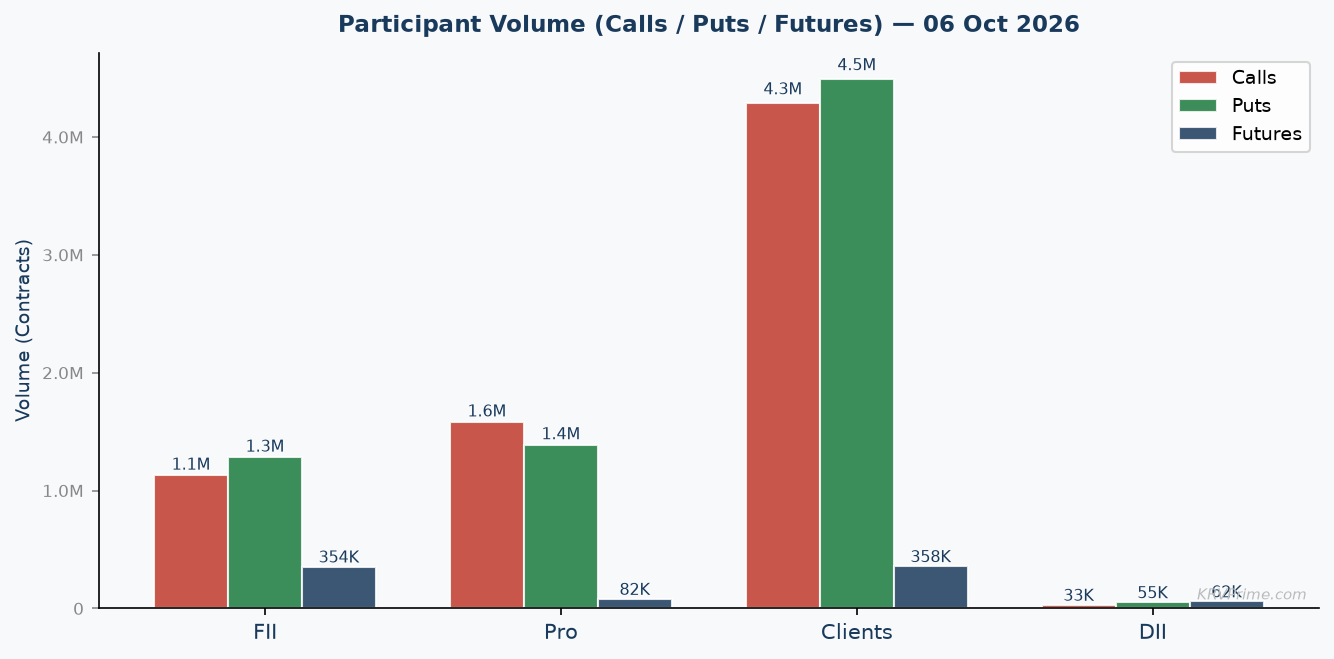
- Futures net improved from -302,391 to -293,725 (net change +8,666 contracts). On the long side, FIIs added 1,168 contracts (prev 29,117 → today 30,285, +4.01%) tagged [Long Buildup - Low Vol], while on the short side they covered 7,498 contracts (prev 331,508 → today 324,010, -2.26%) tagged [Short Covering - Low Vol]. The Low Vol tag on both legs is critical — this is hesitant, thin-volume activity, not a high-conviction repositioning; the short-covering appears tactical rather than a thesis reversal. The gross short-to-long ratio today stands at 324,010 : 30,285 = 10.7:1 — an extraordinary imbalance that confirms FIIs remain structurally and dominantly net short in futures, with the modest improvement in net merely reflecting marginal position trimming around the edges of a fortress-sized short book.
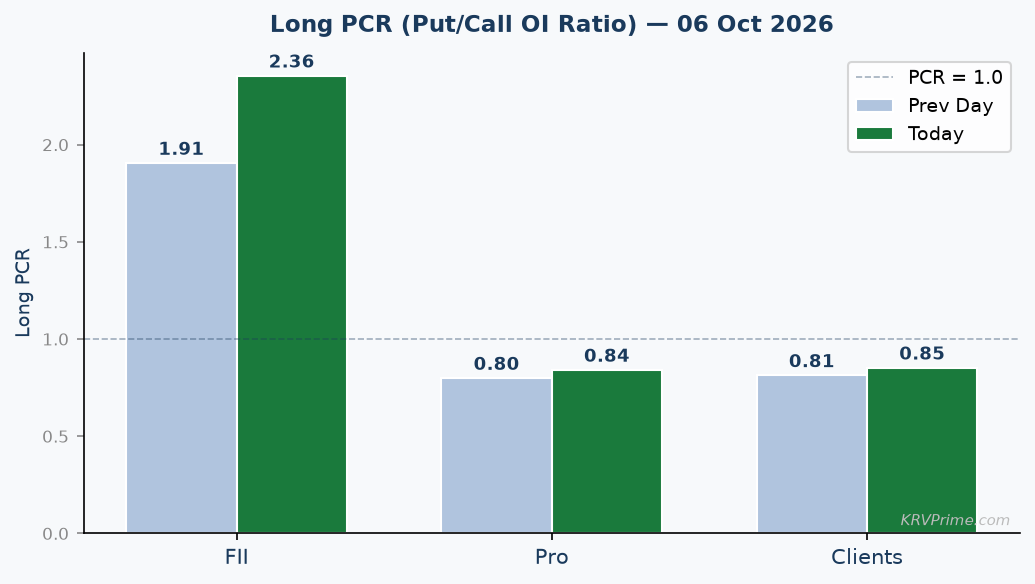
- Long PCR improved from 1.91 to 2.36 (+23.56%) and Short PCR compressed from 0.60 to 0.48 (-18.93%). A Long PCR of 2.36 means FIIs now hold 2.36 put longs for every call long — an extremely defensive and bearish hedging posture that has actually intensified today relative to the prior session, suggesting they are adding protection or rotating into puts even as markets rallied. The Short PCR falling from 0.60 to 0.48 means FIIs are now writing significantly fewer puts relative to calls on their short side — in other words, they are not selling puts aggressively (which would be a bullish income play), but are instead allowing the short-put book to shrink faster than the short-call book, further reinforcing a bearish directional bias in options. The dominant signal today is the Long PCR spike to 2.36 — this is the most extreme put-long bias FIIs have shown and it directly contradicts any narrative of FII capitulation or bullish rotation.
- Call OI net moved from -365,731 to -347,484 (net change +18,247): Long side fell from 616,526 to 393,444 (-223,082, [Long Unwinding - High Vol]) while Short side fell from 982,257 to 740,928 (-241,329, [Short Covering - High Vol]). Put OI net moved from +588,315 to +567,766 (net change -20,549): Long side fell from 1,175,238 to 926,672 (-248,566, [Long Unwinding - High Vol]) while Short side fell from 586,923 to 358,906 (-228,017, [Short Covering - High Vol]). All four legs carry High Vol tags — this is deliberate, large-scale position management, not passive roll-off. The net result is FIIs remain net short calls (-347,484) and net long puts (+567,766) — a classic synthetic short / protective collar architecture that mirrors and amplifies the directional message of their massive futures short book.
- Synthesis — FII Bearish Fortress with Tactical Edge-Trimming: FIIs present the most internally consistent and conviction-heavy bearish architecture across all four data dimensions today. Their futures net of -293,725 remains deeply negative despite modest covering, their Long PCR has surged to a session-extreme 2.36 meaning they now hold more than twice as many put longs as call longs, their net short call position of -347,484 caps market upside from their book, and their net long put position of +567,766 provides aggressive downside monetisation capability. The High Vol tags on all four options legs confirm this is not stale overnight carry — these are actively managed, high-conviction positions being deliberately rolled and reshaped. The only nuance worth noting is that the Low Vol tags on futures long buildup and short covering suggest the futures trimming is cautious and hesitant, not a confident reversal — the core bearish thesis is intact, and today's rally has not forced FII capitulation. Compared to the prior session, FIIs have actually increased their Long PCR from 1.91 to 2.36, meaning the rally today prompted MORE hedging, not less — a clear signal that FIIs view this rally as an opportunity to add protection rather than a reason to reduce their bearish positioning.
- Forward: The critical threshold to monitor is whether FII futures net improves decisively above -280,000 in tomorrow's data — any move in that direction, especially accompanied by High Vol tags on short-covering, would signal the first genuine thesis reconsideration. Conversely, if FII futures net holds at or deteriorates below -293,725 and the Long PCR remains above 2.00, the bearish structure remains completely intact and the market rally should be treated with suspicion. Watch the NIFTY 22,800 CE resistance level (week) — if the market fails to breach and sustain above this level and FII short-call OI begins rebuilding, that would confirm FIIs are re-establishing their cap and the range-down scenario becomes the base case.
DII Mildly Bullish — Steady Long Bias, Reducing Shorts
- Futures net improved from +32,828 to +33,901 (net change +1,073 contracts). DIIs added 273 contracts on the long side (prev 47,700 → today 47,973, +0.57%) tagged [Long Buildup - Low Vol], while reducing 800 contracts on the short side (prev 14,872 → today 14,072, -5.38%) tagged [Short Covering - Low Vol]. The Low Vol tags on both legs indicate this is a quiet, incremental positioning day for DIIs — no dramatic repositioning, just a steady drift toward a cleaner long posture. The gross long-to-short ratio is 47,973 : 14,072 = 3.41:1 in favour of longs — DIIs maintain a structurally bullish futures posture and today's marginal net improvement confirms they are not disturbed by any macro headwinds that are keeping FIIs aggressively short. In direct contrast to FIIs (who have a 10.7:1 short-to-long ratio in futures), DIIs represent the domestic institutional counter-narrative — steady, long-biased, and composed.
- DII options PCR data is not separately broken out in the provided data set in the same Long PCR / Short PCR format as FII and Client segments. However, from the options OI data available, DIIs show Call OI net of +27,771 (Long 30,177, Short 2,406) and Put OI net of +53,541 (Long 54,041, Short 500) — the implied long-put-to-long-call ratio is approximately 54,041 : 30,177 = 1.79:1, suggesting DIIs hold nearly 1.8 put longs for every call long, a moderately defensive posture consistent with a large domestic equity book requiring downside protection. The extremely small short-call book (only 2,406 contracts) and negligible short-put book (500 contracts) tell us DIIs are not active option writers today — their options book is predominantly a hedge/protection structure rather than an income-generating writing strategy, reinforcing the view that they are protecting long equity exposure rather than making a speculative directional bet.
- Call OI net moved from +23,886 to +27,771 (net change +3,885): Long side grew from 27,343 to 30,177 (+2,834, [Long Buildup - Low Vol]) while Short side fell from 3,457 to 2,406 (-1,051, [Short Covering - Avg Vol]). Put OI net moved from +53,315 to +53,541 (net change +226): Long side fell marginally from 54,191 to 54,041 (-150, [Long Unwinding - Low Vol]) while Short side fell from 876 to 500 (-376, [Short Covering - Low Vol]). The call side is notable — DIIs actually added call longs (+2,834) on a day when the broader market saw massive call OI contraction (-42.07% overall), suggesting DIIs may be positioning for further upside through long calls or using calls as a hedge against a short futures book component. The put side is nearly flat with minimal change on both legs, confirming their downside protection book is essentially stable and not being monetised despite the market rally.
- Synthesis — DII Quiet Bullish Stewardship: DIIs present the most consistent and least volatile positioning story across today's session. Their futures net of +33,901 is the highest it has been relative to the prior session, their options book is net long calls (+27,771) and net long puts (+53,541) — a long-biased structure that carries both upside participation (long calls) and downside protection (long puts), consistent with a large domestic equity book management mandate. The Low Vol tags across futures suggest this is steady-state management, not reactive repositioning — DIIs are not alarmed by today's session in either direction. Critically, DIIs are moving in the opposite direction to FIIs on every dimension: where FIIs have a 10.7:1 futures short ratio, DIIs have a 3.41:1 long ratio; where FIIs are net short calls, DIIs are net long calls; this structural divergence between FII and DII is the dominant inter-participant tension in today's market and historically such divergences are resolved in favour of the participant with the larger absolute position — which today remains FII. The one mildly bullish signal from DIIs worth highlighting is the addition of 2,834 call longs against the market-wide call OI collapse — a contrarian call-buying signal that suggests domestic institutions may see further upside from current levels.
- Forward: Watch whether DII futures net crosses above 35,000 in tomorrow's data — any acceleration in long buildup from the current 33,901 accompanied by a High Vol tag would be the first signal that domestic institutions are increasing conviction in the bullish thesis. If instead the futures net stagnates below 33,000 and DII call longs begin unwinding, it would suggest even domestic institutions are losing confidence in the near-term upside. The NIFTY 22,700 PE support (week OI support) is the floor that DII put longs are implicitly defending — a breach of 22,700 on a closing basis would likely trigger DII put monetisation and a rapid shift in the domestic institutional stance.
Pro Tactically Bearish — Flipping Futures Short, Rolling Options
- Futures net deteriorated from +27,530 to +22,724 (net change -4,806 contracts). On the long side, Pros unwound 1,907 contracts (prev 54,509 → today 52,602, -3.50%) tagged [Long Unwinding - Low Vol], while simultaneously building 2,899 new short contracts (prev 26,979 → today 29,878, +10.75%) tagged [Short Buildup - Low Vol]. This dual-leg move — reducing longs AND adding shorts — is a clear directional tilt toward the bear side, even if the Low Vol tags indicate the conviction is currently measured rather than aggressive. The gross long-to-short ratio has compressed from the prior session's 54,509:26,979 = 2.02:1 to today's 52,602:29,878 = 1.76:1, meaning Pros are steadily moving toward a more balanced and then potentially net-short futures book — a meaningful shift in stance for a participant group that has historically used its futures book as a dynamic hedge against options positions.
- Long PCR moved from 0.80 to 0.84 (+5.24%) and Short PCR moved from 0.96 to 0.92 (-3.65%). A Long PCR of 0.84 means Pros hold 0.84 put longs for every call long — they are slightly underweight puts relative to calls on the long side, suggesting their long options book is modestly call-heavy or at near-parity, which is not a strongly defensive posture. The Short PCR falling from 0.96 to 0.92 means Pros are now writing relatively fewer puts compared to calls on the short side — a mild drift toward net-call-writing, which is a supply-cap / range-top strategy. These PCR readings are the most neutral of all participants today, but the direction of both — Long PCR rising (adding put protection) and Short PCR falling (writing more calls) — is incrementally bearish at the margin, consistent with the futures short buildup.
- Call OI net moved from +222,584 to +113,207 (net change -109,377): Long side collapsed from 1,397,750 to 847,385 (-550,365, [Long Unwinding - High Vol]) while Short side fell from 1,175,166 to 734,178 (-440,988, [Short Covering - High Vol]). Put OI net moved from -6,533 to +36,450 (net change +42,983): Long side fell from 1,117,777 to 713,185 (-404,592, [Long Unwinding - High Vol]) while Short side fell from 1,124,310 to 676,735 (-447,575, [Short Covering - High Vol]). All four legs carry High Vol tags — this is the largest and most actively managed options repositioning session among all participants today. Critically, the Put OI net flipped from -6,533 to +36,450 — Pros have moved from net short puts to net long puts, a significant architectural shift. Combined with the net long call position of +113,207, Pros now hold a long straddle / long strangle architecture — net long both calls and puts — which is a volatility-long position that profits from large moves in either direction.
- Synthesis — Pro Volatility-Long with Bearish Futures Lean: Pros present the most complex and nuanced positioning story today. Their options book has shifted to a long straddle / long strangle architecture — net long calls (+113,207) and net long puts (+36,450) — which is a bet on volatility expansion from current levels, not a directional position per se. However, the simultaneous futures short buildup (net -4,806, moving from +27,530 to +22,724) creates a delta-hedged long volatility setup with a bearish tilt: if volatility expands to the downside, Pros profit from both the long puts and the futures shorts; if the market surges, Pros profit from the long calls while the futures short limits gains. The High Vol tags on all four options legs confirm this is deliberate, high-conviction repositioning — not a passive roll. Compared to the prior session, Pros have compressed their call-long advantage dramatically (from +222,584 to +113,207) while flipping their put book from net short to net long — a material rotation that signals Pros are preparing for increased volatility rather than range continuation. The falling VIX (now at 13.61) makes long volatility cheap today, which may explain why Pros are building a long vega position at these levels.
- Forward trigger: The key trigger for Pros' long volatility thesis is India VIX recovering above 14.50 (yesterday's close of 14.78 was the prior anchor) — any VIX spike above that level would begin monetising their long straddle. Conversely, if VIX compresses further below 13.00, their long options book will bleed theta and they may be forced to close the long straddle prematurely, which would appear as simultaneous call and put long unwinding in tomorrow's data. Watch the NIFTY 22,800 CE resistance — if the market breaks and sustains above 22,800 with expanding futures OI, Pros' futures short book will come under pressure and we may see short-covering in futures even as their long call book profits, creating a net-neutral outcome for Pros.
Client Mildly Bullish — Reducing Hedges, Net Long Calls
- Futures net declined from +242,033 to +237,100 (net change -4,933 contracts). On the long side, Clients unwound 4,339 contracts (prev 301,687 → today 297,348, -1.44%) tagged [Long Unwinding - Low Vol], while adding 594 new short contracts (prev 59,654 → today 60,248, +1.00%) tagged [Short Buildup - Low Vol]. The Low Vol tags on both legs indicate this is passive, low-conviction position management — Clients are not aggressively repositioning, but the marginal drift is slightly net-negative (reducing longs and adding shorts). The gross long-to-short ratio remains very favourable at 297,348 : 60,248 = 4.94:1 in favour of longs, confirming that retail/Client participants remain the most aggressively net-long futures segment — a stark contrast to FIIs (10.7:1 short) and consistent with retail's historically contrarian-bullish posture at points of institutional bearishness.
- Long PCR moved from 0.81 to 0.85 (+4.81%) and Short PCR moved from 1.00 to 1.26 (+26.04%). A Long PCR of 0.85 means Clients hold approximately 0.85 put longs for every call long — modestly under-hedged on the long side, a slightly bullish tilt in their long options book. The Short PCR surging from 1.00 to 1.26 is the most important single PCR movement in today's data for Clients — this means Clients are now writing 1.26 puts for every call on their short side, a dramatic shift toward put-writing dominance that signals a bullish income / range trade: they are selling puts aggressively, collecting premium, and implicitly betting that the market will not fall below those strike levels. This Short PCR of 1.26 is consistent with a retail community that sees the recent market dip as a buying opportunity and is monetising that view through put-writing. The combination of a slightly call-heavy long book and a strongly put-heavy short book creates an overall net-bullish options architecture for Clients.
- Call OI net moved from +119,262 to +206,507 (net change +87,245): Long side fell from 4,031,462 to 2,247,106 (-1,784,356, [Long Unwinding - High Vol]) while Short side fell from 3,912,200 to 2,040,599 (-1,871,601, [Short Covering - High Vol]). Put OI net moved from -635,097 to -657,757 (net change -22,660): Long side fell from 3,280,301 to 1,916,279 (-1,364,022, [Long Unwinding - High Vol]) while Short side fell from 3,915,398 to 2,574,036 (-1,341,362, [Short Covering - High Vol]). The headline observation is that the massive absolute contraction in Client options OI (largest in gross terms of any participant today) was driven by expiry-related or roll-related cleanup — High Vol tags on all four legs confirm this was active and deliberate. Despite the absolute shrinkage, Client Call OI net improved from +119,262 to +206,507 because short-call covering (-1,871,601) outpaced long-call unwinding (-1,784,356), while the Put OI net worsened from -635,097 to -657,757 because long-put unwinding slightly outpaced short-put covering — net result: Clients have reduced their put-long protection (unwinding hedges) and increased their net call-long position, a bullish realignment.
- Synthesis — Client Retail Bullish Repositioning via Hedge Reduction: Clients today have executed a nuanced but clearly bullish repositioning: they have reduced downside hedges (put longs unwound more than short puts covered, worsening put net from -635,097 to -657,757), increased net call exposure (+119,262 to +206,507), maintained a massive 4.94:1 long-to-short futures ratio, and most critically, driven their Short PCR from 1.00 to 1.26 — aggressively selling puts to generate income and implicitly backstop the market. This is a retail participant base that is interpreting today's rally as confirmation of the bullish thesis and is removing insurance (put longs) while adding upside exposure (calls) and collecting income (put writing). The divergence between Clients (bullish, put-selling) and FIIs (bearish, put-buying) is at its most extreme today — Clients are essentially selling the puts that FIIs are buying, making them direct counterparties in the options market. The High Vol tags on all four Client options legs confirm this is not accidental — the retail community is actively and deliberately repositioning toward a bullish outcome, though the large absolute size of their remaining short-put book (-2,574,036) means any sharp downturn would expose them to significant put-monetisation risk.
- Forward: The critical threshold for Client positioning is the NIFTY 22,700 PE support (week) — with Clients net short puts and holding a large put-writing book, any sustained break below 22,700 would force put monetisation and could accelerate a downside move through stop-triggered futures long unwinding (from their 297,348 futures long book). Watch whether the Client Short PCR holds above 1.20 in tomorrow's data — if it falls back toward 1.00, it signals put-writing retreat and a loss of the retail income-trade conviction that is currently providing implicit market support. Conversely, if Nifty sustains above 22,776 (today's close) and Clients continue adding call longs while Short PCR expands above 1.30, the bullish retail thesis accelerates and could provide upward momentum through a short-squeeze on the FII futures book.
Bull vs Bear Strength by Participant
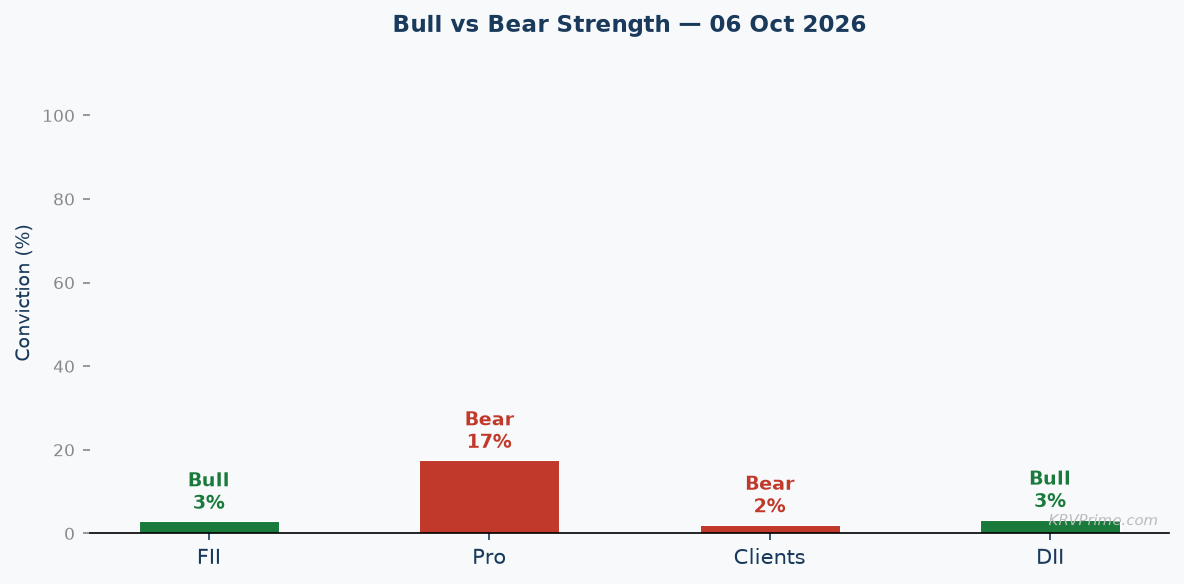
FII Strongly Bearish 85% ▼▼ | Clients Mildly Bullish / Put-Writing 62% ▲ | Pro Volatility Long / Bearish Lean 55% ▼ | DII Mildly Bullish / Steady Long 58% ▲ |
Conclusion — Market Outlook for Tomorrow (07 Oct 2026)
The collective participant picture for 06 Oct 2026 is one of a deeply bifurcated market: FIIs maintain an overwhelming -293,725 futures net with a 10.7:1 short-to-long gross ratio and a Long PCR of 2.36 — the most extreme put-hedging posture seen across today's session — while Clients sit at a +237,100 futures net with a 4.94:1 long-to-short ratio and are aggressively writing puts (Short PCR 1.26). DIIs provide quiet ballast with a +33,901 futures net and a 3.41:1 long ratio, and Pros have tactically rotated to a long-volatility architecture (net long calls +113,207 and net long puts +36,450) with a bearish futures lean (net +22,724, deteriorating). The total options OI collapse of -17.87% (from 48,797,800 to 40,078,006) suggests this is partially a post-expiry or contract-roll cleanup session, which means the raw OI numbers should be read with caution — the directional signals embedded in the PCR and net positioning changes carry more weight than the absolute OI levels today.
The Overall PCR rising from 0.93 to 1.03 (+10.75%) is a constructive signal on the surface — a PCR above 1.0 historically indicates put-side dominance and is associated with market floors and bullish reversals in the near term. However, the mechanism behind today's PCR rise is important: Call OI fell -42.07% while Put OI fell only -35.85% — the PCR rose because calls unwound faster than puts, not because fresh put-buying conviction drove it higher. Meanwhile, India VIX collapsed from 14.78 to 13.61 (-7.90%) — the most bullish single-day signal in today's data, as VIX at 13.61 represents the lower end of the recent range and implies the market is pricing in very low near-term risk. Historically, FII put-heavy positioning at low VIX levels means put protection is being accumulated cheaply — which strengthens rather than weakens the case that FIIs have high conviction in their bearish view, as they are buying insurance at a time when it is inexpensive.
The thesis that would flip tomorrow's outlook from cautiously neutral to decisively bullish would require two simultaneous conditions: FII futures net improving materially toward -275,000 or better (indicating genuine short-covering, not just edge-trimming), accompanied by the FII Long PCR falling back below 2.00 (indicating they are reducing put protection rather than adding it). The thesis that would flip toward decisively bearish would be a breach and sustained close below the NIFTY 22,700 PE weekly support, which would monetise the large Client short-put book, trigger Client futures long stop-losses from the 297,348 long book, and potentially incentivise FIIs to add to their already formidable short position — creating a cascading downside acceleration. Until one of these conditions is met, the market remains in a FII-bear vs Client-bull standoff, with Pros' long-volatility position the most likely to profit from the resolution of this tension in either direction.
Scenario 1 — Bull case:
If FII futures net improves from -293,725 toward -275,000 or better in tomorrow's data, particularly with a High Vol short-covering tag replacing today's Low Vol tag, and the Overall PCR holds above 1.05 driven by fresh put buying rather than call unwinding, the bullish case accelerates. Supporting this scenario would be VIX continuing to fall below 13.00, which would reduce hedging costs and incentivise equity accumulation by domestic and foreign long-only funds. Client put-writing (Short PCR above 1.30) providing a support floor at the 22,700 PE weekly OI support would complete the bull setup — a sustained hold above 22,776 (today's close) with FII short-covering confirmation is the trigger.
Scenario 2 — Bear case:
If FII futures net deteriorates from -293,725 and the Long PCR holds above 2.20 or rises further, FIIs are reinforcing — not reducing — their bearish conviction. A simultaneous VIX reversal back above 14.78 (yesterday's level) would signal fear re-entering the market and would begin monetising both FII long puts and Pro long puts simultaneously. The critical bearish trigger is a sustained close below the NIFTY 22,700 weekly PE support — this would force Client short-put holders (currently carrying 2,574,036 short puts) to cover aggressively, creating a put-covering squeeze that drives premiums higher and simultaneously incentivises Client futures long liquidation from their 297,348 long book, creating a compounding downside move.
Key Resistance NIFTY 22,800 (Weekly CE OI Resistance) — FIIs hold a massive net short call position of -347,484 contracts, actively capping the market at this strike; any market attempt above 22,800 must overcome this FII supply wall, and the High Vol tag on FII call shorts confirms this cap is deliberate and actively maintained. | Key Support NIFTY 22,700 (Weekly PE OI Support) — FIIs hold 926,672 long puts (net +567,766) providing downside monetisation fuel below this level, while Clients have a large short-put book of 2,574,036 that requires 22,700 to hold to remain profitable; breach of this level would trigger simultaneous FII put profits and Client put-loss covering, creating an asymmetric downside accelerant. | Trigger to Watch FII futures net crossing -280,000 (improvement of ~13,725 contracts from today's -293,725) with a High Vol short-covering confirmation tag — this would be the first objective signal that FII bearish conviction is cracking; absent this, the Overall PCR holding above 1.05 with VIX below 13.00 is the secondary bullish confirmation trigger. |