
Market Participants Analysis dated 07.10.2026
KRVPrime — Daily Market Outlook
Key Market Signals — Data: 07 Oct 2026
NIFTY 50 22,603.05 ▼ -173.05 (-0.76%) | BANK NIFTY 55,055.55 ▼ -72.85 (-0.13%) | SENSEX 72,638.70 ▼ -429.11 (-0.59%) |
OVERALL PCR 0.89 ▼ -0.14 (-13.52%) PCR dropped sharply below 1.00 — put-to-call ratio signals rising bearish sentiment and call accumulation dominance. | INDIA VIX 13.88 ▲ +0.27 (+2.04%) VIX rising from 13.61 — fear inching higher; options premiums expanding, confirming directional anxiety. | TOTAL OI CHANGE 44,367,670 ▲ +4,289,664 (+10.70%) Large OI build on a down-day signals fresh short positions, not unwinding — bearish continuation risk. |
FUTURES OI 876,212 ▲ +19,796 (+2.31%) Futures OI rising alongside price decline — classic short buildup confirmation in index futures. | CALL OI CHANGE 9,359,221 ▲ +2,322,998 (+33.01%) Massive call OI expansion — resistance supply being heavily written at upper strikes, capping upside. | PUT OI CHANGE 8,305,886 ▲ +1,085,532 (+15.03%) Put OI building but at a slower pace than calls — PCR falling, market leaning bearish near-term. |
Participant-wise Key Points
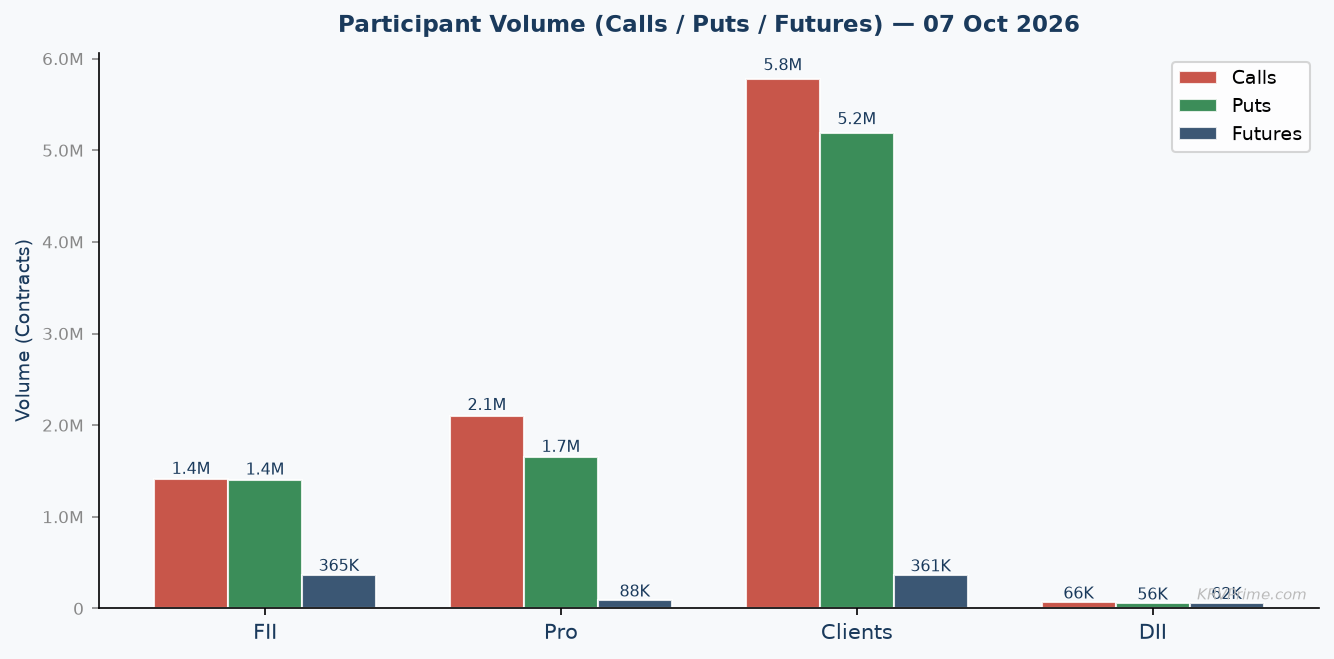
FII Strongly Bearish — Dual-Leg Conviction Short with Defensive Put Hedge
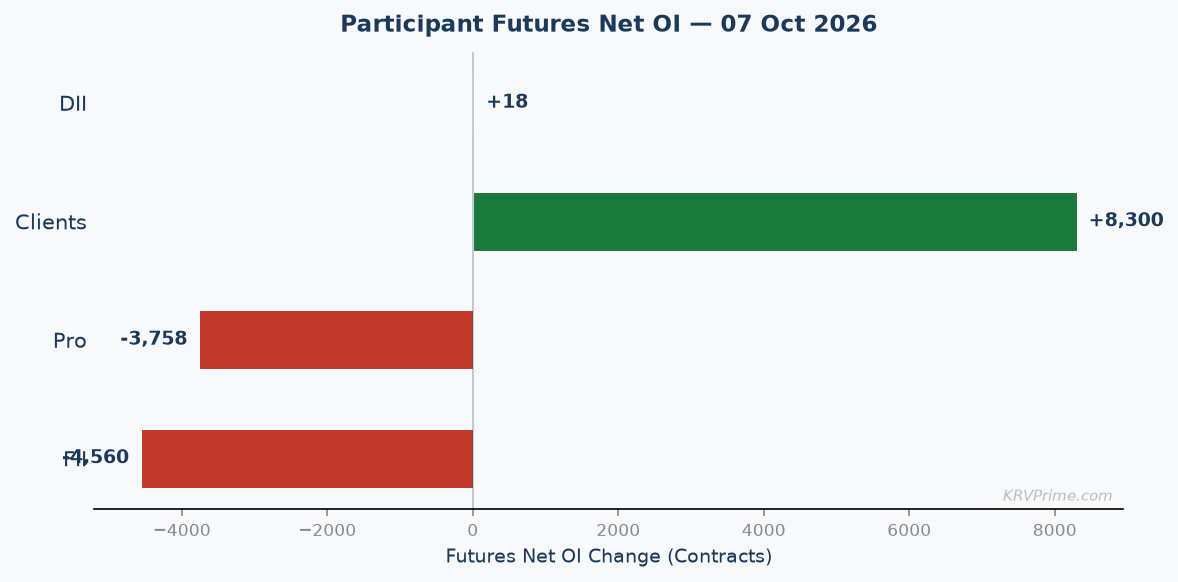
- Futures net deteriorated from -293,725 to -298,285 (net change -4,560, worsening by -1.55%). On the long side, FIIs added 3,141 contracts (prev 30,285 → today 33,426, +10.37%) tagged [Long Buildup - Low Vol], while on the short side they added a far larger 7,701 contracts (prev 324,010 → today 331,711, +2.38%) tagged [Short Buildup - Low Vol]. The Low Vol tag on both legs indicates this net expansion was achieved with below-average volume commitment — it is not a high-conviction thrust but rather a steady, persistent accumulation of an existing short thesis. The gross short-to-long ratio now stands at 331,711 : 33,426 = 9.92:1, an almost 10-to-1 dominance of shorts over longs — this is not a hedged futures book; this is an outright directional short of the highest magnitude, and the ratio has widened from the previous session's 10.70:1 (prev 324,010:30,285), showing FIIs are maintaining structural bearishness without meaningfully reducing exposure despite today's modest price decline.
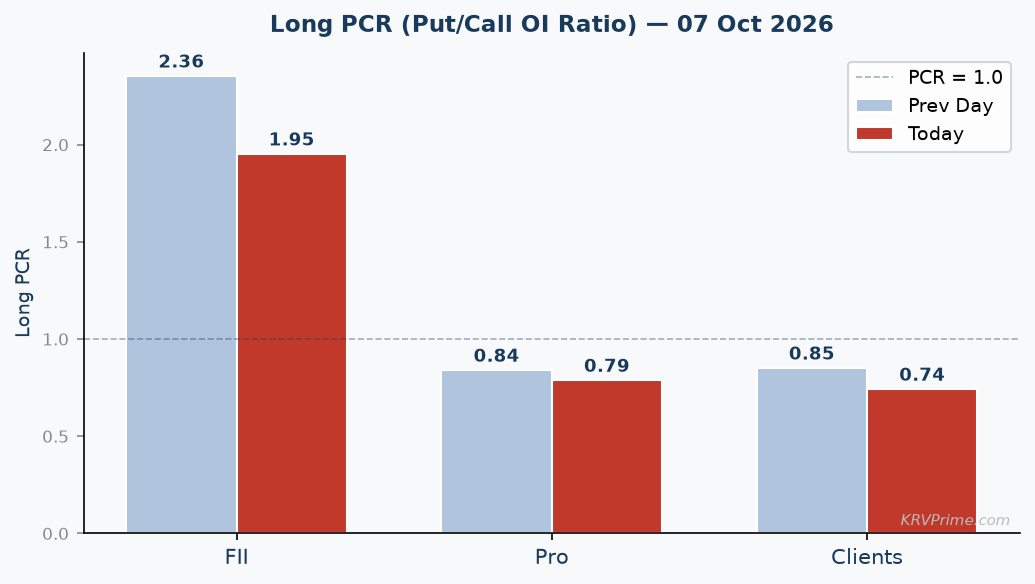
- Long PCR dropped sharply from 2.36 to 1.95 (-17.02%), and Short PCR fell from 0.48 to 0.46 (-5.35%). The Long PCR of 1.95 still means FIIs hold nearly twice as many put longs as call longs — this remains a deeply defensive hedging posture, but the sharp -17.02% drop in Long PCR is significant: it means FIIs added call longs (or reduced put longs) at a faster rate than they added put longs today, which introduces a mild element of ambiguity — are they beginning to hedge their massive short book with some upside coverage? The Short PCR of 0.46 — well below 1.00 — means FIIs are writing nearly twice as many calls as puts on the short side, a classic resistance-capping strategy that confirms they expect the market to struggle on any rally attempts. The dominant signal from both PCRs taken together is still overwhelmingly bearish: short PCR below 0.50 means they are writing calls aggressively at resistance, while Long PCR near 2.00 means they are still holding a large protective put long book.
- Call OI net moved from -347,484 to -400,079 (net change -52,595, becoming more net short). Call longs expanded from 393,444 to 506,730 (+113,286, [Long Buildup - Low Vol]), while call shorts expanded faster from 740,928 to 906,809 (+165,881, [Short Buildup - Low Vol]), creating a net short call book of -400,079 contracts. Put OI net improved marginally from +567,766 to +574,665 (net change +6,899): put longs grew from 926,672 to 990,415 (+63,743, [Long Buildup - Low Vol]), while put shorts also expanded from 358,906 to 415,750 (+56,844, [Short Buildup - Low Vol]), maintaining net long puts of +574,665 contracts. The architecture is unambiguous: net short calls (-400,079) + net long puts (+574,665) = a textbook synthetic short / protective collar — FIIs are simultaneously capping any upside rally through call writing while retaining and even growing their put long hedge for downside monetisation.
- Synthesis — FII Dual-Leg Bearish Conviction with Resistance Capping Architecture: FIIs present the most internally consistent and structurally bearish positioning among all participants today. The futures net of -298,285 is the most extreme gross short in the market, the 9.92:1 short-to-long futures ratio leaves no room for alternative interpretation — this is a directional conviction short, not a hedged book. The net short call position of -400,079 and net long put position of +574,665 together form a complete synthetic short architecture via options, reinforcing every conclusion drawn from futures. The falling Long PCR (from 2.36 to 1.95) is the one nuance: FIIs are adding some call longs even as they add more call shorts, possibly buying OTM calls as cheap delta hedges against a squeeze, but this does not change the dominant bearish architecture. Compared to the previous session, FIIs have deepened their net short futures by 4,560 contracts and deepened their net short call position by 52,595 contracts — they are accelerating into their bearish thesis, not pausing or reversing. VIX rising to 13.88 from 13.61 also suits their put long book, as rising volatility inflates the mark-to-market value of their long put positions.
- Forward: The critical trigger to monitor is whether FII futures net crosses deeper below -300,000 contracts in tomorrow's data — a breach of that psychologically significant threshold would confirm accelerating conviction in the bearish direction and is likely to coincide with Nifty testing the weekly PE support at 21,500 or the monthly PE support at 22,000 over the coming sessions. Conversely, if FII futures net improves (short-covering) back toward -290,000 or better, that would be the first credible signal of thesis relaxation and could trigger a sharp short-covering rally. Watch also whether the FII Long PCR recovers back above 2.00 — a rebound there would confirm they are re-loading put longs, signalling renewed bearish intent rather than thesis abandonment.
DII Structurally Bullish — Futures Flat, Aggressive Call Long Buildup
- Futures net held essentially flat from +33,901 to +33,919 (net change +18, barely changed). The long side was virtually unchanged at 47,974 contracts (prev 47,973, chg +1, [Long Buildup - Low Vol]), while the short side also barely moved at 14,055 contracts (prev 14,072, chg -17, [Short Covering - Low Vol]). The gross long-to-short ratio stands at 47,974 : 14,055 = 3.41:1, confirming DIIs hold a structurally net long futures book with no sign of capitulation — even as markets fell -0.76% today, DIIs did not liquidate a single meaningful long position. The Low Vol confirmation tag on both sides and the near-zero net change indicate DIIs were in a holding pattern in futures today, preferring to express their view through options rather than futures — and the options data tells a dramatically different and more active story.
- DII PCR data is not separately reported in the provided dataset — therefore, no Long PCR or Short PCR ratio can be quoted for this participant. However, the directional signal from DII options positioning can be inferred directly from the Call OI and Put OI net changes, which are detailed in Bullet 3. What is visible is that DII options activity today was overwhelmingly concentrated on the call long side, which — when combined with their net long futures book — creates a consistent and clearly bullish directional message for this participant.
- Call OI net surged from +27,771 to +61,443 (net change +33,672, more than doubling). Call longs exploded from 30,177 to 63,899 (+33,722, [Long Buildup - High Vol]), while call shorts barely changed from 2,406 to 2,456 (+50, [Short Buildup - Low Vol]). The High Vol tag on call longs is a critical distinction — this was not a routine or thin accumulation; DIIs made a deliberate, high-conviction move to nearly double their call long book in a single session. Put OI net edged up from +53,541 to +54,691 (net change +1,150): put longs grew from 54,041 to 55,191 (+1,150, [Long Buildup - Low Vol]), while put shorts held flat at 500 contracts (chg 0, [Short Flat - Low Vol]). The architecture here is net long calls (+61,443) + net long puts (+54,691) = a long straddle / long strangle structure, suggesting DIIs are positioned for a large directional move — but the dominant new money today was entirely in call longs (High Vol), which tilts the bias toward an expected upside resolution.
- Synthesis — DII High-Conviction Call Accumulation Against a Bearish Tape: The most striking feature of DII positioning today is the +33,722 call long addition tagged [Long Buildup - High Vol] — this is the only High Vol confirmation tag in the entire DII book and it occurred on a day when Nifty fell -0.76%. DIIs were buying calls aggressively into weakness, which is a classic contrarian long signal from the most structurally patient participants in the Indian market. Their futures net of +33,919 (long-to-short ratio 3.41:1) has been stable and net long, and today's call long surge is fully consistent with that bullish structural bias — DIIs are not hedging a short book; they are adding upside optionality with conviction. The combination of stable long futures + large new call longs + flat put shorts creates a picture of a participant that expects the current weakness to be temporary and is actively positioning for a rebound rather than following the market lower. This stands in stark contrast to FII positioning, where the dominant strategy is net short futures + net short calls + net long puts — FIIs and DIIs are currently on opposite sides of the directional debate with high conviction.
- Forward: The key trigger for DII positioning is whether Nifty can stabilise at or above the monthly PE support at 22,000 — a hold there would validate DII's call long accumulation and could see them add further aggressively to the call side. If however Nifty breaches 22,000 with expanding OI, DII's call long book (which cost premium outflow) would begin to bleed, and the next session's data showing any reduction in their call long OI (currently 63,899 contracts) would be the first warning that DIIs are cutting losses on their bullish options bet. Watch whether call long OI grows above 70,000 contracts tomorrow — any such expansion would confirm escalating DII bullish conviction.
Pro Cautiously Bearish — Expanding Shorts in Futures, Balanced Options Book Tilting Short
- Futures net deteriorated from +22,724 to +18,966 (net change -3,758, declining). The long side added a modest 1,035 contracts (prev 52,602 → today 53,637, +1.97%, [Long Buildup - Low Vol]), while the short side added a much more aggressive 4,793 contracts (prev 29,878 → today 34,671, +16.04%, [Short Buildup - Avg Vol]). The short addition carries an Avg Vol tag — this is not a thin, hesitant move; it is a routine-to-moderate conviction short addition that pushed the gross short side up significantly. The gross long-to-short ratio is now 53,637 : 34,671 = 1.55:1 — tighter than the previous session's 1.76:1 (52,602:29,878) — confirming that Pros are gradually reducing their net long advantage in futures by adding shorts faster than longs, reflecting growing caution on the directional upside.
- Long PCR fell from 0.84 to 0.79 (-6.18%), and Short PCR fell from 0.92 to 0.78 (-15.38%). A Long PCR of 0.79 means Pros hold more call longs than put longs — they are not in a deeply defensive put-heavy hedge posture, but the falling Long PCR (from 0.84) tells us they are either adding call longs faster or reducing put longs, maintaining a mild call-biased long options book. The Short PCR drop from 0.92 to 0.78 is the more important signal today: a falling short PCR means Pros are now writing significantly more calls than puts on their short side — at 0.78, they are writing ~22% more calls than puts, which is a resistance-capping posture consistent with a view that the market will struggle to rally. The dominant signal from the combined PCR trend is bearish-leaning: Pros are increasing their call-write dominance on the short side while maintaining a call-biased long book, creating a covered call / short strangle tilt.
- Call OI net moved from +113,207 to +96,011 (net change -17,196, declining). Call longs expanded massively from 847,385 to 1,099,880 (+252,495, [Long Buildup - Low Vol]), but call shorts expanded even faster from 734,178 to 1,003,869 (+269,691, [Short Buildup - Low Vol]), causing the net call position to shrink despite gross additions on both sides. Put OI net surged from +36,450 to +85,524 (net change +49,074, more than doubling). Put longs grew from 713,185 to 868,508 (+155,323, [Long Buildup - Low Vol]), while put shorts grew from 676,735 to 782,984 (+106,249, [Short Buildup - Low Vol]) — put longs grew faster than put shorts, creating the large improvement in net put OI. The architecture is a declining net long calls + rising net long puts = shifting from a bullish options lean toward a more defensive/bearish tilt, with the bulk of new money in this session going into put long protection rather than call long speculation.
- Synthesis — Pro Desk Cautious Bearish Pivot with Options Re-Architecture: Pros entered today with a mildly bullish options posture (net long calls at +113,207, net long puts at only +36,450) and have exited the session with a compressed net call position (+96,011) and a dramatically expanded net put position (+85,524). Combined with their futures short addition (+4,793 new shorts, Avg Vol) that compressed their net futures advantage from +22,724 to +18,966, the overall message is of a participant pivoting cautiously toward a more defensive or mildly bearish stance. The Low Vol tags on all options legs prevent this from being called a high-conviction move — Pros are re-balancing their book rather than making a bold directional call, which is consistent with their role as market-makers and arbitrageurs. The falling Short PCR (0.92 → 0.78) confirms increased call-writing activity at upper strikes, suggesting Pros are helping to reinforce the resistance wall at 23,000 (Nifty weekly CE resistance) and 23,500 (monthly CE resistance). Compared to FIIs (dominant structural shorts) and DIIs (aggressive call buyers into weakness), Pros are positioning themselves in the middle — willing to sell calls at resistance but also accumulating put longs for downside coverage, suggesting they see a range-bound or mildly lower resolution for the near term.
- Forward trigger: The critical level to watch for Pros is whether their futures net holds above +15,000 contracts — if tomorrow's data shows the net declining further toward +10,000 or below, it would signal that Pros are actively transitioning from a net long to near-neutral or even net short futures stance, which would be a meaningful bearish confirmation. Equally important, watch whether the net put OI (currently +85,524) continues to expand — if it crosses +100,000 contracts with any volume tag upgrade from Low to Avg or High, that would signal Pros are loading up on downside protection with escalating conviction, reinforcing the bearish case for Nifty toward the 22,000 monthly PE support.
Client Structurally Bullish — Long Futures, Put Writing Tilt but Hedging with Put Longs
- Futures net improved from +237,100 to +245,400 (net change +8,300, strengthening). The long side added 5,721 contracts (prev 297,348 → today 303,069, +1.92%, [Long Buildup - Avg Vol]), while the short side reduced by 2,579 contracts (prev 60,248 → today 57,669, -4.28%, [Short Covering - Low Vol]). The Avg Vol tag on the long buildup indicates this was a routine-to-moderate conviction long addition — not thin or hesitant, but not a high-conviction surge either. Short covering on the short side (reducing from 60,248 to 57,669) with a Low Vol tag suggests small players were opportunistically closing bearish futures bets on the dip. The gross long-to-short ratio stands at 303,069 : 57,669 = 5.26:1 — an overwhelming dominance of longs over shorts that confirms retail clients remain structurally positioned for an upside move despite today's -0.76% decline in Nifty, and they actually increased that dominance from the previous session's 4.94:1 (297,348:60,248).
- Long PCR fell sharply from 0.85 to 0.74 (-12.76%), and Short PCR fell from 1.26 to 1.07 (-15.36%). A Long PCR of 0.74 means Clients hold more call longs than put longs — they are positioned for upside participation more than downside protection, consistent with their overwhelmingly net long futures book. The sharp -12.76% drop in Long PCR tells us call longs expanded faster than put longs today, i.e., Clients were buying calls aggressively into the decline — a classic retail buy-the-dip behavior in the options market. The Short PCR dropping from 1.26 to 1.07 is also important: it was above 1.00 (writing more puts than calls on the short side), which means Clients were funding their long options book partially by selling puts — but the sharp decline to 1.07 shows this put-writing dominance is compressing, potentially because put premiums became expensive with VIX rising to 13.88 making put writing less attractive. Overall, the PCR signals confirm Clients are bullish-leaning but the falling short PCR suggests the put-writing income strategy is being partially unwound.
- Call OI net improved from +206,507 to +242,626 (net change +36,119). Call longs surged from 2,247,106 to 3,009,102 (+761,996, [Long Buildup - Low Vol]), while call shorts also surged from 2,040,599 to 2,766,476 (+725,877, [Short Buildup - Low Vol]), with call longs expanding slightly faster, improving the net. The Low Vol tag on both sides — despite massive gross additions — indicates this is broad retail participation across many strikes rather than concentrated high-conviction positioning. Put OI net declined from -657,757 to -714,880 (net change -57,123, worsening). Put longs grew from 1,916,279 to 2,238,829 (+322,550, [Long Buildup - Low Vol]), but put shorts grew faster from 2,574,036 to 2,953,709 (+379,673, [Short Buildup - Low Vol]), deepening the net short put position. The architecture is net long calls (+242,626) + net short puts (-714,880) — this is a classic synthetic long / bullish risk reversal structure: Clients are buying call optionality while funding it (partially) by selling puts, expressing a bullish view with leveraged risk if the market declines sharply.
- Synthesis — Client Retail Bullish Risk Reversal — Buy-the-Dip Behavior on Display: Clients today demonstrated a textbook buy-the-dip retail response: they improved futures net from +237,100 to +245,400 (+8,300), bought 761,996 new call longs, and deepened their net short put position to -714,880 contracts. The combined net long calls + net short puts creates a synthetic long structure that profits if Nifty rallies but accelerates losses if Nifty falls sharply below the strikes where put shorts are concentrated. This is the polar opposite of FII positioning (net short futures + net short calls + net long puts), making Clients and FIIs the clearest adversaries in today's market — FIIs are the structural bears and Clients are the structural bulls, with the current session seeing both sides add to their respective positions simultaneously. The Low Vol tags throughout the Client options book are typical of retail distribution across many strike prices rather than concentrated institutional bets. One risk embedded in the Client book is the growing -714,880 net short put position: with VIX already rising (13.88, +2.04%) and the overall PCR dropping to 0.89, if Nifty accelerates lower, these short puts will come under pressure and may force defensive unwinding (buying back puts) which would paradoxically provide downside acceleration.
- Forward trigger: The critical threshold to monitor in the Client book is whether the net short put position deepens beyond -750,000 contracts — if it does, Clients are doubling down on their bullish put-writing strategy and creating a larger gamma risk tail on the downside. Watch the overall PCR: if it drops below 0.80 tomorrow (currently 0.89), it would mean call OI is massively outpacing put OI, confirming aggressive retail call buying / put writing is continuing — a setup that historically precedes sharp reversals when stop-loss levels are hit. The OI support at 22,000 (Nifty monthly PE) is the line in the sand for Client put shorts — a Nifty break below that level would trigger rapid put short unwind from the Client book, amplifying any decline.
Bull vs Bear Strength by Participant
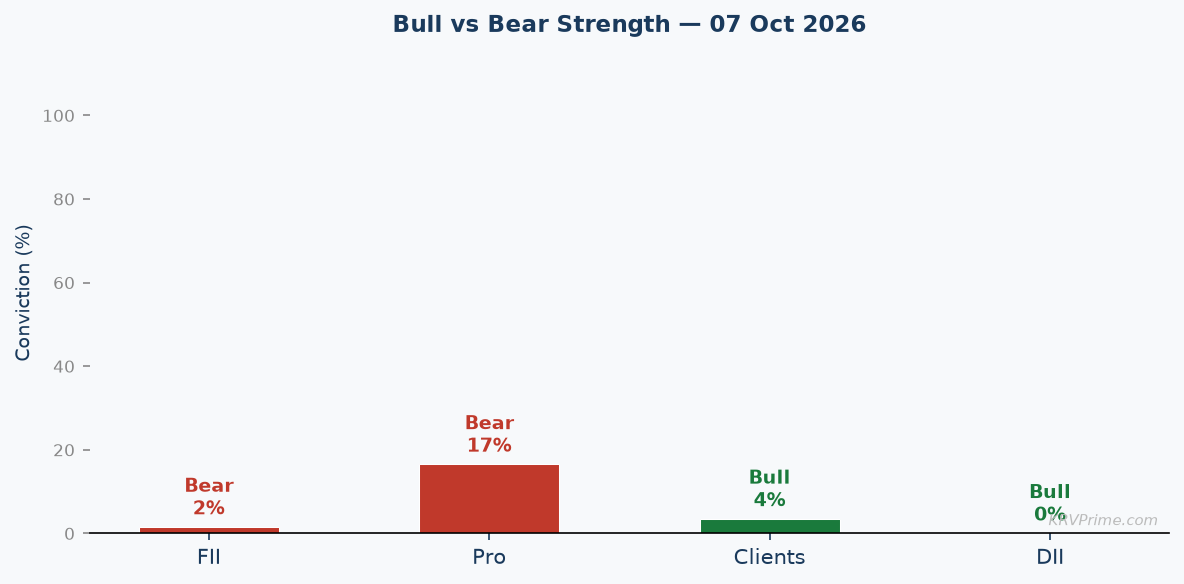
FII Strongly Bearish 88% ▼▼ | DII Bullish — Call Accumulation 72% ▲▲ | Pro Cautiously Bearish 62% ▼ | Client Bullish — Risk Reversal 60% ▲ |
Conclusion — Market Outlook for Tomorrow (08 Oct 2026)
The collective participant positioning on 07 Oct 2026 presents a structurally bearish picture driven overwhelmingly by FII conviction. FIIs deepened their futures net short to -298,285 contracts (short-to-long ratio 9.92:1), expanded their net short call position to -400,079 contracts, and maintained a net long put position of +574,665 contracts — a complete dual-leg synthetic short architecture that dominates the market's directional signal. Pros added to their futures short book (short side grew +4,793 contracts, Avg Vol) and pivoted their options book toward increased put longs (net put OI more than doubled from +36,450 to +85,524), providing secondary bearish confirmation. On the opposing side, DIIs made a high-conviction call long addition (+33,722 call longs, [Long Buildup - High Vol]) — the only High Vol tag in today's entire dataset — signalling institutional domestic buyers are aggressively fading the weakness. Clients maintained their structural net long futures position (+245,400 contracts) and deepened their synthetic long options architecture (net long calls +242,626, net short puts -714,880). The weight of smart money (FII + Pro) is clearly bearish, while domestic money (DII + Client) is positioned bullish — this divergence is the defining tension in the current market.
The overall PCR dropped sharply from 1.03 to 0.89 (-13.52%), a meaningful move below the neutral 1.00 threshold that signals call accumulation is outpacing put accumulation — typically a bearish sentiment indicator when accompanied by price decline, as it reflects hedging demand being overwhelmed by call-writing supply. India VIX ticked higher from 13.61 to 13.88 (+2.04%), confirming that options premiums are expanding and market participants are pricing in incrementally more uncertainty. While 13.88 is not in an elevated fear zone, the direction of change matters: VIX rising alongside a declining market and expanding OI (+10.70% total OI build) on a down-day is a classic short-building confirmation. The OI resistance at 23,000 (Nifty weekly CE) and 23,500 (monthly CE) are heavily fortified by FII and Pro call writing, making any near-term rally to those levels unlikely to sustain. The OI support at 22,000 (monthly PE) and 21,500 (weekly PE) are the key downside anchors held by FII put longs and DII/Client structural longs.
The bearish thesis would be challenged and potentially reversed if FII futures net shows meaningful improvement (short-covering) toward -285,000 or better in tomorrow's session, if the overall PCR recovers back above 1.00, or if VIX reverses sharply below 13.00 — any two of these three triggers firing simultaneously would suggest the FII short thesis is being unwound and a sharp short-covering rally could follow. Conversely, the bearish thesis accelerates if FII futures net crosses below -300,000 contracts, PCR drops below 0.80, and VIX breaks above 15.00 — in that scenario, the Client put short book (-714,880 contracts) becomes a dangerous gamma accelerant on the downside.
Scenario 1 — Bull case:
If FII futures net improves meaningfully toward -285,000 contracts (implying short-covering of ~13,000+ contracts), accompanied by the overall PCR recovering above 1.00, and VIX reversing below 13.00, then DII's aggressive call long positioning (63,899 contracts) would be validated and Client put shorts would be safe. In this scenario, Nifty would likely stabilise above the monthly PE support at 22,000 and begin a recovery toward the 23,000 weekly CE resistance. The trigger confirmation would be FII call short OI declining from the current 906,809 while their put long OI holds — signalling they are relaxing the resistance cap without abandoning the put hedge.
Scenario 2 — Bear case:
If FII futures net deepens below -300,000 contracts in the next session, overall PCR drops below 0.80, and VIX pushes above 15.00, the bearish case accelerates significantly. The Client net short put book (-714,880 contracts) becomes the critical risk amplifier — forced put buybacks as the market declines would create a negative gamma loop. In this scenario, Nifty would likely test the weekly PE support at 21,500 with conviction, and the monthly PE support at 22,000 would break. Pro's expanding put long position (net +85,524 contracts) would begin monetising, and the call OI resistance wall at 23,000–23,500 would become irrelevant as price moves away from it.
Key Resistance Nifty 23,000 (weekly CE max OI) and 23,500 (monthly CE max OI) — FIIs hold 906,809 call shorts and Pros hold 1,003,869 call shorts at and around these strikes, creating a formidable dual-participant supply wall that will cap any intraday rally attempt. | Key Support Nifty 22,000 (monthly PE max OI) and 21,500 (weekly PE max OI) — FIIs hold 990,415 put longs concentrated near these strikes as their primary downside monetisation vehicle; DIIs and Clients hold structural long futures and put longs that provide demand support at these levels. A breach of 22,000 on expanding OI would be the most significant bearish structural event. | Trigger to Watch The most actionable trigger is the overall PCR — currently 0.89. If PCR drops below 0.80 in tomorrow's session, it would confirm that call OI supply is massively overwhelming put demand, validating the FII + Pro bearish architecture and signalling Nifty is headed toward the 22,000 monthly support. A PCR recovery above 1.00 would be the first genuine sign of bullish reversal, favoured by DII and Client positioning. |