
Market Participants Analysis dated 08.10.2026
KRVPrime — Daily Market Outlook
Key Market Signals — Data: 08 Oct 2026
NIFTY 50 22,231.80 ▼ -371.25 (-1.64%) | BANK NIFTY 54,515.05 ▼ -540.50 (-0.98%) | SENSEX 71,593.24 ▼ -1045.46 (-1.44%) |
OVERALL PCR 0.74 ▼ -0.15 (-16.75%) PCR collapsed from 0.89 to 0.74 — aggressive call writing and put unwinding signal rising bearish dominance | INDIA VIX 15.28 ▲ +1.40 (+10.01%) VIX spiked +10.01% to 15.28 — fear zone entry; options premium elevated, directional moves likely | TOTAL OI CHANGE 49,657,832 ▲ +5,290,162 (+11.92%) Massive OI expansion on a down day confirms fresh short buildup, not short-covering |
FUTURES OI 880,396 ▲ +4,184 (+0.48%) Marginal futures OI increase alongside market decline confirms mild short addition | CALL OI CHANGE 12,767,666 ▲ +3,408,445 (+36.42%) Explosive call OI surge (+36.42%) on a down day — aggressive call writing building overhead resistance | PUT OI CHANGE 9,433,294 ▲ +1,127,408 (+13.57%) Put OI expanded +13.57% but lagged call build — PCR compression confirms bearish options flow |
Participant-wise Key Points
FII Strongly Bearish — Dual-Leg Conviction Short with Protective Put Buildup
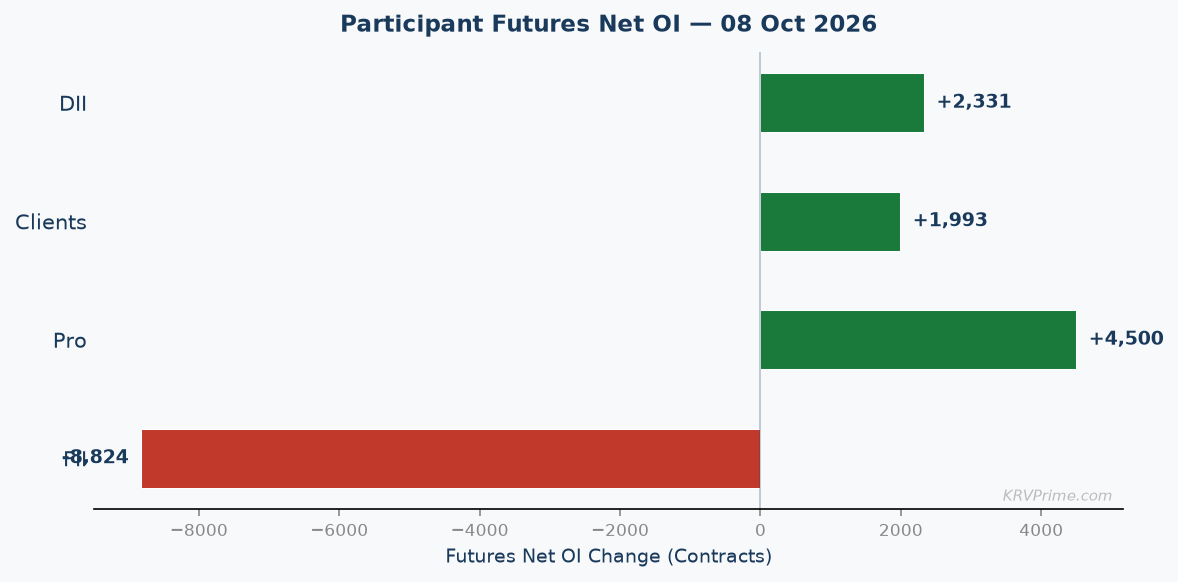
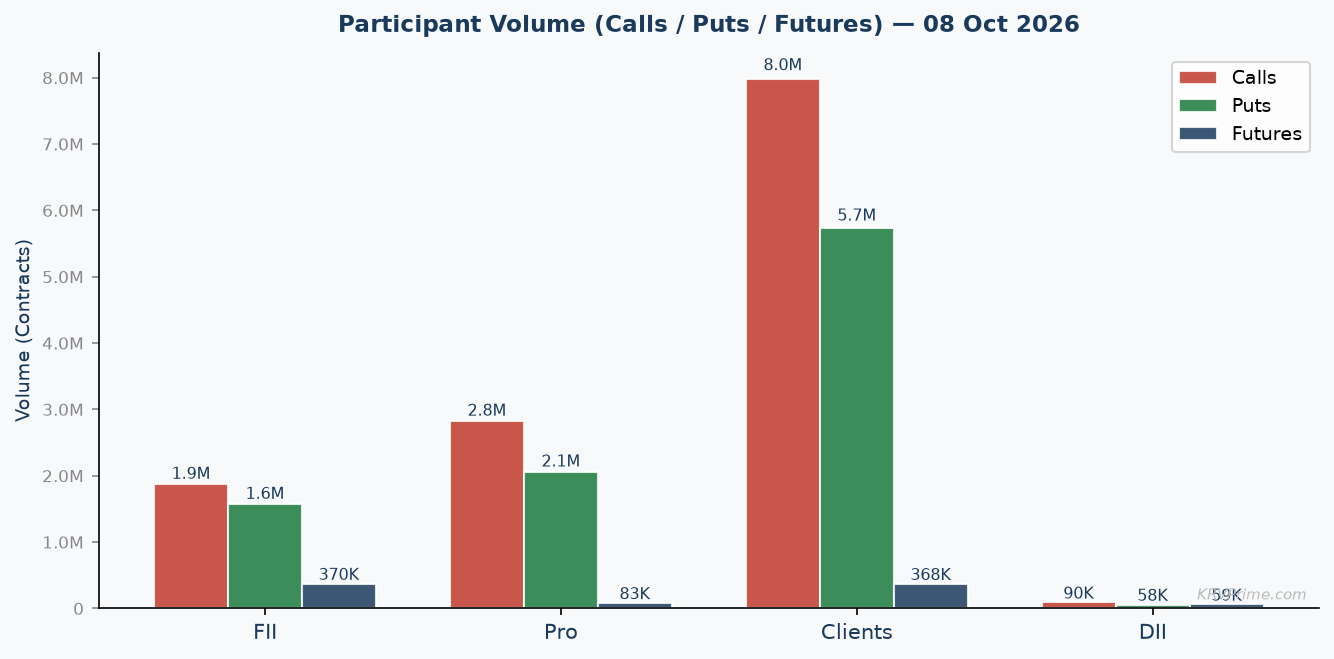
- Futures net deteriorated from -298,285 to -307,109 (net change -8,824 contracts), as FIIs shed 1,843 long contracts [Long Unwinding - Low Vol] and simultaneously added 6,981 short contracts [Short Buildup - Avg Vol]. The low volume on the long unwind suggests FIIs are passively liquidating residual longs rather than aggressively exiting — the dominant action is the Avg Vol short buildup, which reflects a routine yet deliberate addition to an already enormous short book. At 338,692 gross shorts vs 31,583 gross longs, the short-to-long ratio stands at 10.7:1 — this is not a hedge ratio, this is an outright, high-conviction directional short position of the kind that only institutional desks with macro-level conviction take. FIIs have now been deepening this short across multiple sessions, and today's -1.64% Nifty decline confirms their thesis is playing out; they are not covering into weakness, which means they do not believe the current decline is the low.
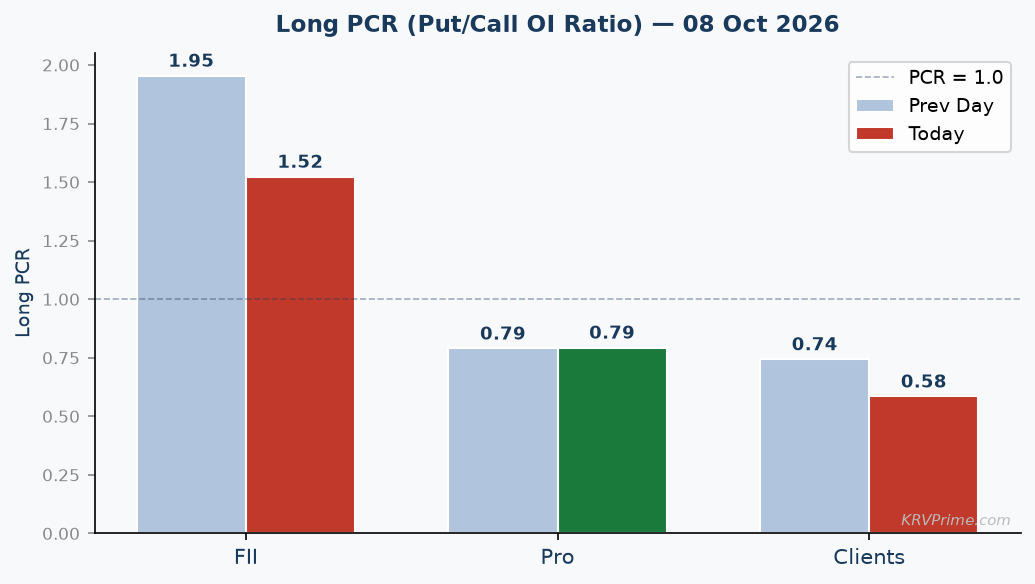
- Long PCR declined from 1.95 to 1.52 (-22.07%) and Short PCR declined from 0.46 to 0.40 (-12.72%). The Long PCR of 1.52 means FIIs still hold 52% more put longs than call longs — a deeply defensive posture that signals either large equity book protection or outright directional bearishness via options. The sharp -22.07% fall in Long PCR is significant: FIIs added far more call longs (+230,429) than put longs (+132,428), reducing their put-heavy tilt but still maintaining a net put-dominant long book. The Short PCR falling from 0.46 to 0.40 means FIIs are writing calls more aggressively relative to puts on their short side — a cap-the-upside strategy entirely consistent with their massive futures short book, telling us they do not expect any meaningful upside recovery in the near term.
- Call OI net moved from -400,079 to -404,278 (net change -4,199). Call Longs expanded from 506,730 to 737,159 [Long Buildup - Low Vol] while Call Shorts expanded from 906,809 to 1,141,437 [Short Buildup - Low Vol]. Despite adding more call longs (possibly for gamma hedging or spread legs), the gross short call book at 1,141,437 continues to dominate, maintaining FIIs as net call sellers. Put OI net improved from +574,665 to +666,083 (net change +91,418): Put Longs grew from 990,415 to 1,122,843 [Long Buildup - Low Vol] while Put Shorts grew from 415,750 to 456,760 [Long Buildup - Low Vol]. The architecture of net short calls (-404,278) combined with net long puts (+666,083) is a textbook synthetic short / protective collar — FIIs are positioned to profit maximally from a sustained decline and are also explicitly protected against a rally through their long put book. The Low Vol tags on all four legs suggest this is a spread-like, structured position rather than panic-driven flow.
- Synthesis — FII Dual-Leg Conviction Bear Architecture: Every data point in FII's book points in one direction today. A futures net of -307,109 (10.7:1 short-to-long), a Long PCR of 1.52 (net put-long dominance), net short calls of -404,278, and net long puts of +666,083 form the most internally consistent bearish architecture among all four participant groups. FIIs are simultaneously short via futures, capped on upside via short calls, and protected via long puts — this is a full-spectrum bearish structure, not a one-legged bet. Critically, they did not cover a single meaningful short contract today despite Nifty declining -1.64%, which indicates they are targeting a lower level and are not yet satisfied with the move. Compared to the prior session, the net futures position worsened by -8,824 and put net improved by +91,418, showing an accelerating rather than stable bearish posture. The only mild internal contradiction is the Low Vol tags on the options legs — suggesting FIIs are adding to this structure in a controlled, measured manner rather than in a panic or euphoric rush, which paradoxically makes the positioning more credible.
- Forward trigger: Watch whether FII futures net deepens beyond -315,000 in tomorrow's data — if it does, it signals a new leg of institutional short-adding and Nifty could target the 22,000 monthly PE support level where maximum put OI is clustered. Conversely, if FII futures net improves toward -295,000 (net short-covering of ~12,000 contracts), that would be the first early signal of short thesis exhaustion and a potential dead-cat bounce setup. The Long PCR at 1.52 is also a key watch: a further fall below 1.30 would confirm FIIs are unwinding their protective put hedge and shifting to a less defensive posture, which would reduce downside conviction.
DII Selectively Bullish — Covering Futures Shorts, Building Call Longs on Dip
- Futures net improved from +33,919 to +36,250 (net change +2,331 contracts). DIIs marginally shed 182 long contracts [Long Unwinding - High Vol] but more meaningfully covered 2,513 short contracts [Short Covering - Low Vol], resulting in a net long improvement of +2,331. The High Vol tag on the long unwinding is notable — it tells us the tiny long reduction of 182 contracts carried disproportionate volume, possibly reflecting rolling or expiry-related activity rather than conviction selling. The Low Vol tag on the short covering of 2,513 contracts means DIIs are quietly but deliberately reducing their short book without making noise — this is characteristic of insurance companies and mutual funds that accumulate on dips with patience. At 47,792 longs vs 11,542 shorts, the long-to-short ratio is 4.1:1, confirming DIIs remain structurally net long futures and today's decline has not shaken their conviction.
- DII Index Options PCR data is not separately reported in the participant breakdown; however, their options positioning data is available from the OI section. DIIs do not publish standalone Long PCR and Short PCR figures in this dataset, so a direct PCR comparison is not possible for this participant. What can be inferred is that DIIs' put long book (57,284 contracts) comfortably exceeds their put short book (900 contracts), implying a put net of +56,384 — a deeply hedged long equity posture that is consistent with their futures long stance. Similarly, their call long book (87,660) vastly exceeds their call short book (2,761), giving a call net of +84,899 — this is unusual because most bullish participants write puts rather than buy calls, suggesting DIIs are either adding convex upside exposure or hedging a specific event risk in both directions.
- Call OI net stands at +84,899 (Long 87,660 [Long Buildup - High Vol], Short 2,761 [Short Buildup - High Vol]). The High Vol tag on Call Longs is the standout signal here — DIIs added 23,761 call long contracts at high volume on a day when Nifty fell -1.64%, which is a classic dip-buy-with-upside-leverage move. Put OI net stands at +56,384 (Long 57,284 [Long Buildup - Avg Vol], Short 900 [Short Buildup - Avg Vol]). The small put short addition of +400 contracts at Avg Vol is negligible and likely premium income collection. The architecture of net long calls (+84,899) combined with net long puts (+56,384) creates a long straddle / strangle posture — DIIs are positioning for a high-volatility, high-magnitude move in either direction, though the net long futures bias of +36,250 tilts the overall stance toward an expectation that any large move will ultimately be upward.
- Synthesis — DII Dip-Buy Straddle Architecture: DIIs present a fascinating and internally coherent picture today. Their futures net improved to +36,250 (long-to-short ratio 4.1:1), they covered 2,513 short futures contracts quietly, and simultaneously bought 23,761 call longs at High Vol on a down day — all of which speak to a dip-buying, structurally bullish institutional posture. The combined net long calls (+84,899) and net long puts (+56,384) creates a long straddle-like architecture, meaning DIIs acknowledge the elevated VIX environment at 15.28 and are positioned to profit from a large move in either direction, while their futures long net confirms they believe the primary direction of that move is higher over the medium term. Compared to the prior session where their short book stood at 14,055, today's reduction to 11,542 (short covering of -2,513) shows active de-risking of the bearish component even as the market fell — a strong contrarian accumulation signal. This is in sharp contrast to FIIs who are adding to shorts; DIIs and FIIs are structurally opposed today, which is a classic institutional stand-off that historically resolves in favour of the participant with the larger domestic flow base (DIIs) over weekly time frames, but FIIs tend to dominate intraday and daily direction.
- Forward trigger: Watch whether DII futures net expands above 40,000 in tomorrow's data — a move above that threshold would confirm accelerating dip accumulation and would mark the highest futures net long position for DIIs in recent sessions, signalling strong domestic institutional conviction in a bottom. If instead the net retreats below 34,000 (i.e., longs are being unwound faster than shorts are being covered), it would suggest even DIIs are capitulating to the FII-led bearish pressure. The High Vol call long addition today at 87,660 total is also a key watch — if Call Longs exceed 100,000 tomorrow with sustained High Vol confirmation, it would confirm DIIs are aggressively positioning for a near-term bounce.
Pro Tactically Bearish — Aggressive Net Call Writing Flips Options Net Negative
- Futures net improved from +18,966 to +23,466 (net change +4,500 contracts), as Pros covered 4,978 short contracts [Short Covering - High Vol] while unwinding 478 long contracts [Long Unwinding - High Vol]. Both High Vol tags are critical here — the short covering of 4,978 contracts at high volume is a deliberate, conviction-driven reduction of directional shorts, not passive rollover. At 53,159 longs vs 29,693 shorts, the long-to-short ratio is 1.8:1, meaning Pros maintain a modest net long futures bias. However, this futures improvement is strongly contradicted by their options book, which flipped dramatically bearish today — making Pros the most internally complex participant to interpret.
- Long PCR held flat from 0.79 to 0.79 (+0.51%, essentially unchanged) while Short PCR dropped from 0.78 to 0.67 (-13.77%). The Long PCR of 0.79 means Pros hold modestly more call longs than put longs — a mild bullish lean in their long options book. However, the Short PCR collapse from 0.78 to 0.67 is the dominant signal: Pros are now writing significantly more calls than puts on their short side, meaning their short options book is call-heavy. A Short PCR of 0.67 (writing 0.67 puts for every 1 call written) is a bearish-options-writing posture — Pros are selling calls aggressively, capping upside, and are far less aggressive about writing puts. This Short PCR decline contradicts the mild bullish tilt in the futures book and creates a split-personality setup for Pros today.
- Call OI net flipped dramatically from +96,011 to -90,652 (net change -186,663). Call Longs expanded from 1,099,880 to 1,365,145 [Long Buildup - Low Vol] but Call Shorts exploded from 1,003,869 to 1,455,797 [Short Buildup - Low Vol] — a massive +451,928 short call addition versus only +265,265 long call addition. This is the defining move of the Pro book today: they added nearly half a million short call contracts in a single session, flipping their call net from positive to -90,652. Put OI net held positive at +104,152 (Long 1,083,333 [Long Buildup - Low Vol], Short 979,181 [Short Buildup - Low Vol]), with both sides expanding in near-equal proportion (+214,825 longs vs +196,197 shorts). The architecture — net short calls (-90,652) combined with net long puts (+104,152) — is a synthetic short / bear spread posture in options, which directly contradicts the net long futures position. Pros are clearly bifurcating their strategy: using futures to hedge or remain marginally long while using options to establish a distinctly bearish directional bet.
- Synthesis — Pro Split-Personality Bear Options / Long Futures Architecture: Pros present the most analytically complex picture today. Their futures net improved to +23,466 via high-conviction short covering, suggesting that on a pure futures basis they are modestly bullish or at least reducing directional shorts. Yet their options book tells the opposite story: they added 451,928 short call contracts (the single largest gross options move of any participant today), flipping their call net from +96,011 to -90,652 — a swing of -186,663. Combined with their net long puts of +104,152, the options architecture is a clear synthetic short or bear spread. The resolution of this apparent contradiction lies in a classic professional desk strategy: using futures to manage delta in the short term while using options to express medium-term directional conviction — in this case, capping any Nifty rally above the 23,000 CE resistance zone with aggressive short calls, while protecting against further downside via long puts. The Short PCR falling to 0.67 confirms the short-call dominance. Compared to the prior session where Pros had a positive call net of +96,011, today's complete flip to -90,652 is a step-change in positioning — this is not incremental; it represents a full reversal of options stance in a single session.
- Forward trigger: The critical watch for Pros is whether their Call OI net deepens further below -90,652 tomorrow — if it does (i.e., more short calls are added above current levels), it would confirm that Pros are establishing a systematic call-writing program that will continue to cap rallies. If instead the Call OI net recovers toward 0 (i.e., short calls are covered), it would signal that the call-writing was a single-day opportunistic trade on the VIX spike rather than a structural stance. Given today's India VIX at 15.28 (elevated), Pros may be harvesting elevated premium on short calls — so watch VIX: if it retreats below 14.00 tomorrow, expect partial short-call covering from Pros as the premium advantage diminishes.
Client Conflicted — Buying Calls and Futures on Dip, Absorbing Put Shorts Against Long Puts
- Futures net improved marginally from +245,400 to +247,393 (net change +1,993 contracts). Clients added 4,595 long contracts [Long Buildup - Avg Vol] and also added 2,602 short contracts [Short Buildup - Avg Vol] — both at Avg Vol, indicating routine retail and HNI activity rather than high-conviction institutional action. At 307,664 longs vs 60,271 shorts, the long-to-short ratio is 5.1:1, confirming Clients remain the most aggressively net long participant in futures across all four groups. This retail-led futures long buildup on a day Nifty fell -1.64% is consistent with the classic retail behavior of buying dips — Clients are the counter-party to FII shorts and have been absorbing selling pressure, making them the structural opponent of FII bears. This stand-off between Client longs and FII shorts is the defining tension of today's session.
- Long PCR declined sharply from 0.74 to 0.58 (-21.38%) and Short PCR declined from 1.07 to 0.87 (-18.82%). The Long PCR of 0.58 means Clients now hold significantly more call longs than put longs — a decisively bullish lean in their long options book, as they are buying calls at nearly 1.7:1 ratio over puts. The -21.38% decline in Long PCR is the single sharpest intraday PCR compression among all participants today, driven by Clients adding 1,184,767 call long contracts versus only 214,358 put long contracts. The Short PCR falling from 1.07 to 0.87 is also significant: Clients were previously writing more puts than calls (Short PCR > 1.0 = net premium selling on put side = mildly bullish bet), but today shifted toward writing more calls relative to puts. A Short PCR of 0.87 combined with the dominant call-long posture suggests Clients are in a directional call buying + incidental call writing mode — they are overwhelmingly expressing a bullish directional view via call longs.
- Call OI net stands at +410,031 (Long 4,193,869 [Long Buildup - Low Vol], Short 3,783,838 [Short Buildup - Low Vol]). The massive call long addition of +1,184,767 is by far the largest gross call long increase of any participant today. However, the Low Vol tag is a caution flag — this enormous volume of call long buying was done at below-average volume, suggesting it may represent retail option-buying at elevated VIX (15.28) premium levels, which carries risk of rapid time decay. Put OI net stands at -826,619 (Long 2,453,187 [Long Buildup - Low Vol], Short 3,279,806 [Short Buildup - Low Vol]). Clients are net short puts by 826,619 contracts — meaning they have written more puts than they hold long, a position that profits if Nifty stays above the strike level. The combination of net long calls (+410,031) and net short puts (-826,619) creates a synthetic long posture — Clients are positioned for Nifty to rise or at minimum not fall sharply, using both call buying and put writing to express this view. This is in direct and stark opposition to FIIs' synthetic short architecture.
- Synthesis — Client Retail Synthetic Long Against FII Institutional Short: Clients are the most aggressively bullish participant today by both futures (net +247,393, 5.1:1 long-to-short) and options (net long calls +410,031, net short puts -826,619). Their combined futures and options posture forms a textbook synthetic long — they are buying calls and writing puts simultaneously while holding a massive futures long, which maximises profit if Nifty rallies but creates compounding losses if the decline continues. The critical risk in the Client book is the net short put position of -826,619 contracts: if Nifty breaks the 22,000 monthly PE support, these put shorts become deeply in-the-money and Clients face forced covering (buying back puts at a loss) that would amplify selling pressure. The Low Vol tags on all Client options legs are a concern — high gross OI added at low volume suggests fragmented retail participation rather than coordinated institutional buying, making this book more likely to fold under sustained pressure. Contrasting Clients vs FIIs: FIIs hold a 10.7:1 short-to-long futures ratio with -307,109 net, while Clients hold a 5.1:1 long-to-short with +247,393 net — this is the market's central tension, and history suggests when FII shorts are at this extreme, the risk of a final flush that wipes out retail longs is elevated before any recovery.
- Forward trigger: The key watch for Clients is the 22,000 Nifty monthly PE support level: if Nifty breaks and closes below 22,000, Client put short positions (-826,619 net) will come under severe pressure, forcing covering that could accelerate the decline in a feedback loop. Conversely, if Nifty holds above 22,231 (today's close) and reclaims ground toward 22,500, the Client call long book of 4,193,869 will generate mark-to-market gains that encourage further dip-buying and could shift the overall PCR back toward 0.85+, signalling sentiment recovery. Watch tomorrow's Client futures net: if it surpasses +255,000, it confirms retail accumulation is intensifying; if it drops below 240,000, it signals retail capitulation has begun.
Bull vs Bear Strength by Participant
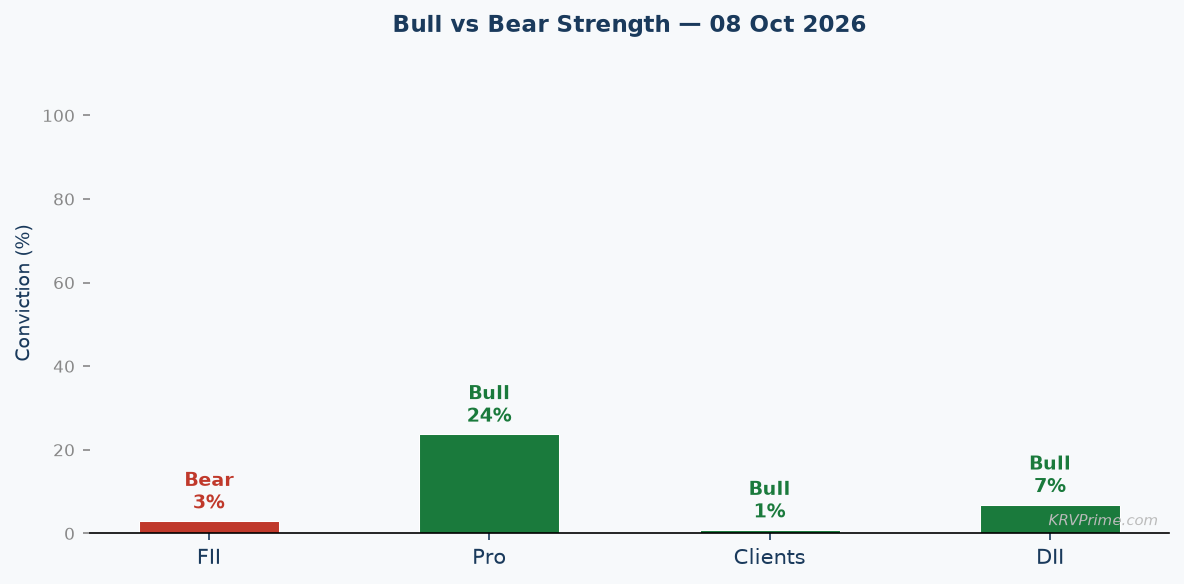
FII Strongly Bearish 88% ▼▼ | Clients Bullish / Synthetic Long 62% ▲ | Pro Tactically Bearish via Options 65% ▼ | DII Selectively Bullish / Dip Buying 58% ▲ |
Conclusion — Market Outlook for 09 Oct 2026
The structural picture across all four participants today is one of deep institutional bearishness led by FIIs, partially offset by retail and domestic institutional dip-buying. FIIs deepened their futures net short to -307,109 (10.7:1 short-to-long ratio), added 6,981 short contracts at Avg Vol conviction, and maintained a dual-leg options short architecture (net short calls -404,278, net long puts +666,083) — the most internally consistent and heavily capitalised bearish posture in the market. Pros reinforced this bearish theme through the options channel by adding a massive 451,928 short call contracts in a single session, flipping their call net from +96,011 to -90,652 and driving their Short PCR to 0.67 — a dramatic shift that suggests professional desks are aggressively writing calls to cap any Nifty upside above 23,000 CE resistance. Against this, DIIs improved their futures net to +36,250 via quiet short covering and added 23,761 call longs at High Vol — a genuine dip-buying signal — while Clients maintained a 5.1:1 futures long and a synthetic long options architecture. The market is therefore in a tug-of-war between FII/Pro institutional bears and DII/Client structural bulls, with the weight of institutional positioning currently favoring the bearish side.
The Overall PCR's collapse from 0.89 to 0.74 (-16.75%) on a day when total OI expanded by +5,290,162 contracts (+11.92%) is a deeply bearish signal: this is not PCR falling because puts are being unwound — it is PCR falling because calls are being added at a rate (+36.42%) nearly three times faster than puts (+13.57%), indicating that market participants are overwhelmingly writing or buying calls to express bearish or range-bound views. India VIX's surge from 13.88 to 15.28 (+10.01%) in a single session confirms that the market has entered an elevated fear zone — options premium is now expensive across the board, and the VIX spike on a -1.64% Nifty day suggests the market is pricing in further volatility rather than a mean-reversion bounce. Historically, when VIX crosses 15 alongside a PCR below 0.80, the probability of continued near-term downside is elevated. The 22,000 monthly PE support and 23,000 weekly CE resistance form the current OI-defined range within which the market is likely to oscillate, with the bearish bias pointing toward a test of 22,000 put support in the near term.
The bearish thesis would be invalidated if FII futures net improves materially toward -290,000 (a covering of approximately 17,000 short contracts), as that would signal institutional shorts beginning to take profit and reduce directional exposure. Additionally, if the Overall PCR recovers above 0.85 in tomorrow's session — driven by put buying rather than call unwinding — it would indicate that protective demand is rising and the market is pricing in a reversal. A VIX retreat below 13.50 would further confirm that fear is being priced out and the volatility-driven selling is exhausted. Until these thresholds are met, the dominant read is bearish with the immediate focus on whether Nifty can defend the 22,000 monthly PE support as the structural floor.
Scenario 1 — Bull case:
If FII futures net improves from -307,109 toward -290,000 (net short covering of ~17,000+ contracts) in tomorrow's session, combined with the Overall PCR recovering above 0.85 and India VIX retreating below 14.00, the bearish thesis weakens materially. DII further expanding their futures net long above 40,000 alongside continued High Vol call long accumulation would confirm domestic institutional dip-buying is absorbing FII selling pressure. A Client put short book of -826,619 remaining intact (i.e., no mass covering) would further signal the retail synthetic long is holding, creating a floor. In this scenario, Nifty could stabilise and attempt a recovery targeting the 22,500–22,600 zone, with the 23,000 CE resistance remaining the medium-term ceiling.
Scenario 2 — Bear case:
If FII futures net deepens further below -315,000 (adding another ~8,000+ short contracts) with Avg or High Vol confirmation, and the Overall PCR slides further toward 0.65 or below, the bearish second leg is confirmed. A VIX expansion above 17.00 would signal panic-phase entry, where option buyers on the put side monetise gains and Clients begin covering their net short put book of -826,619, creating forced buying of puts that paradoxically amplifies downside as dealers hedge. Pro short call positions capping at the 23,000 CE level ensure any technical bounce is sold aggressively. In this scenario, Nifty tests the 22,000 monthly PE support — a breach of 22,000 on a closing basis would trigger the next wave of selling toward the 21,000 weekly PE support level.
Key Resistance 23,000 (Nifty Weekly CE max OI) and 23,500 (Nifty Monthly CE max OI) — Pros added 451,928 short call contracts today creating a massive supply wall; FII net short call book of -404,278 further reinforces this as a ceiling. Any rally toward 23,000 will face aggressive institutional call writing from both FII and Pro desks. | Key Support 22,000 (Nifty Monthly PE max OI) and 21,000 (Nifty Weekly PE max OI) — FIIs hold net long puts of +666,083 contracts anchored around these levels; DII put longs of 57,284 and Client put longs of 2,453,187 are also concentrated here. A breach of 22,000 on closing basis would monetise FII long puts and trigger Client put-short covering, accelerating the decline. | Trigger to Watch Overall PCR crossing back above 0.85 (from today's 0.74) — this single threshold would confirm put demand is rising relative to call supply and that the bearish options flow is reversing. Simultaneously watch India VIX: a close below 14.00 would signal the fear premium is normalising. If both occur together alongside FII futures net improving above -295,000, the bearish thesis is invalidated and a tactical long entry becomes viable. |