
Market Participants Analysis dated 10.09.2026
KRVPrime — Daily Market Outlook
Key Market Signals — Data: 10 Sep 2026
NIFTY 50 23,477.80 ▲ +46.30 (+0.20%) | BANK NIFTY 56,471.95 ▲ +176.40 (+0.31%) | SENSEX 74,902.59 ▲ +138.36 (+0.19%) |
OVERALL PCR 0.78 ▲ +0.01 (+1.59%) PCR at 0.78 — marginally improving but still below 1.0, indicating call-heavy OI; mild put-side recovery in progress. | INDIA VIX 11.79 ▼ -0.13 (-1.05%) VIX at 11.79 and falling — deep complacency zone; low fear supports steady premium selling environment. | TOTAL OI CHANGE 49,419,238 ▲ +2,569,688 (+5.48%) Large OI expansion of +5.48% driven by options side; confirms fresh positioning, not rollover. |
FUTURES OI 873,096 ▲ +14,066 (+1.64%) Modest futures OI build at +1.64%; mixed directional signals as both longs and shorts added across participants. | CALL OI CHANGE 11,408,897 ▲ +1,162,048 (+11.34%) Call OI surged +11.34% — aggressive supply-side writing and long call accumulation creating resistance overhead. | PUT OI CHANGE 8,895,922 ▲ +1,031,772 (+13.12%) Put OI expanded +13.12%, outpacing calls — rising PCR signal with fresh protective and directional put positioning. |
Participant-wise Key Points
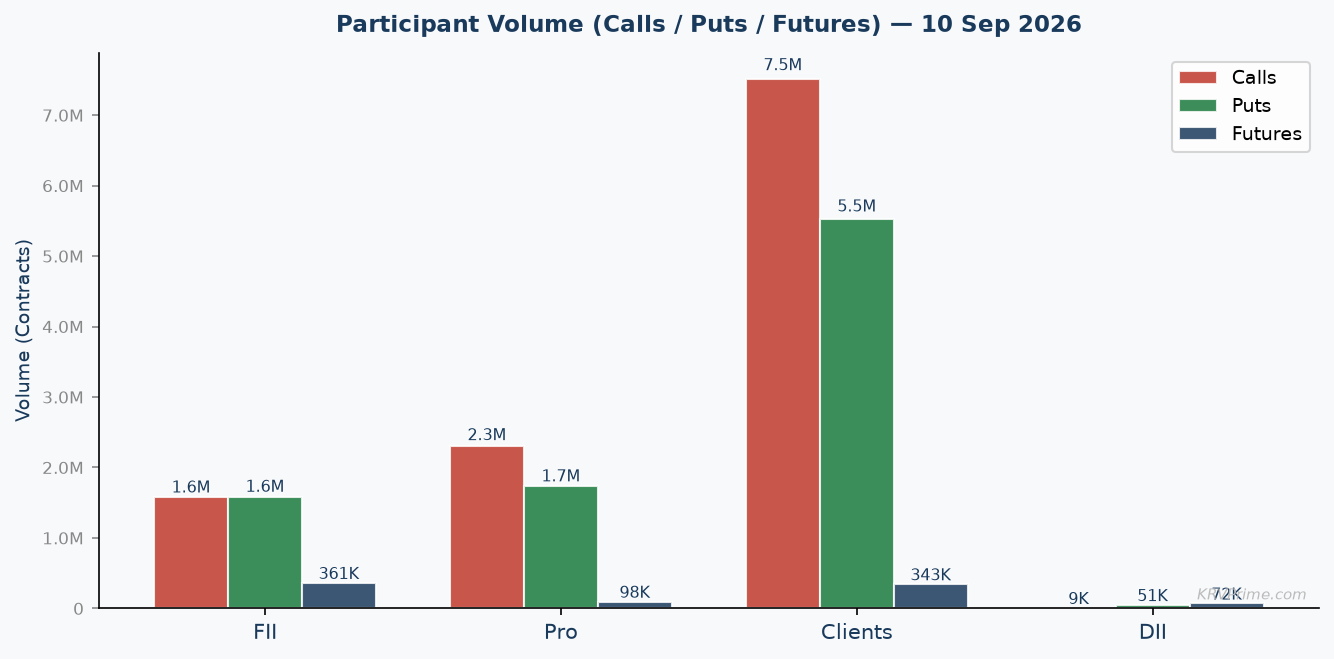
FII Bearish — Dual-Leg Short Buildup With Defensive Put Coverage
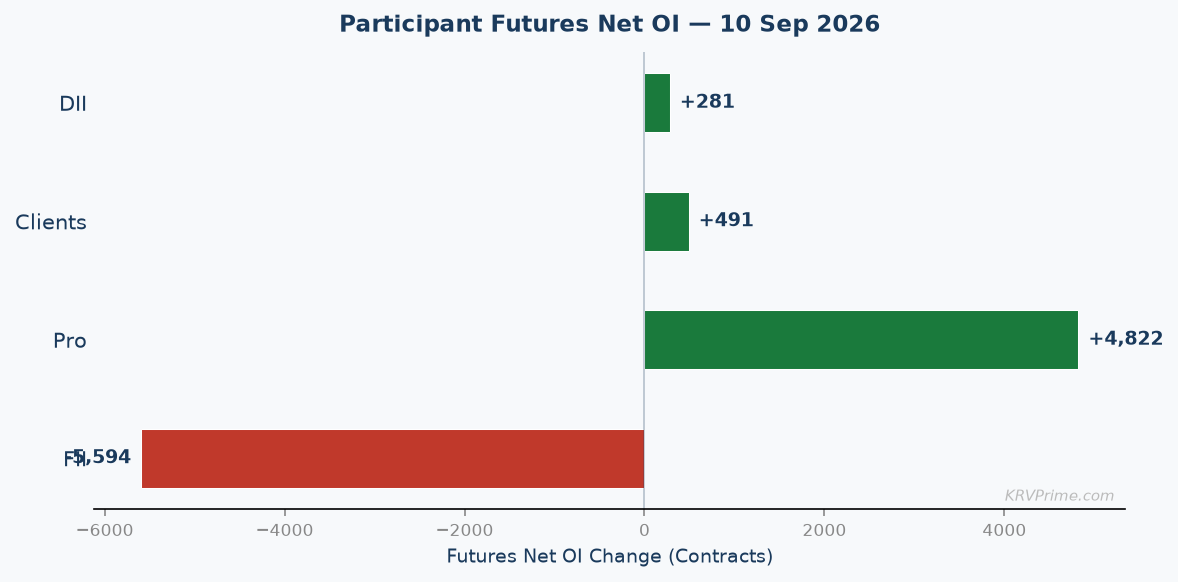
- Futures net deteriorated from -276,250 to -281,844 (net change -5,594 contracts). The Long side added 667 contracts (prev 39,027 → today 39,694, +1.71%) tagged [Long Buildup - Low Vol], while the Short side added a substantially larger 6,261 contracts (prev 315,277 → today 321,538, +1.99%) tagged [Short Buildup - Low Vol]. The Low Vol tag on both legs indicates that while both sides grew, neither was accompanied by outsized volume — this is a measured, deliberate extension of an existing short thesis rather than a panic-driven or high-conviction new entry. Crucially, the gross short-to-long ratio now stands at 321,538 ÷ 39,694 = 8.1:1, an enormous imbalance that leaves no ambiguity — this is not a hedging structure, it is an outright directional short of the highest order. FIIs have not only refused to cover into today's +0.20% Nifty gain but have actively deepened their net short by 5,594 contracts, confirming they view this rally as an opportunity to add to their bearish futures conviction.
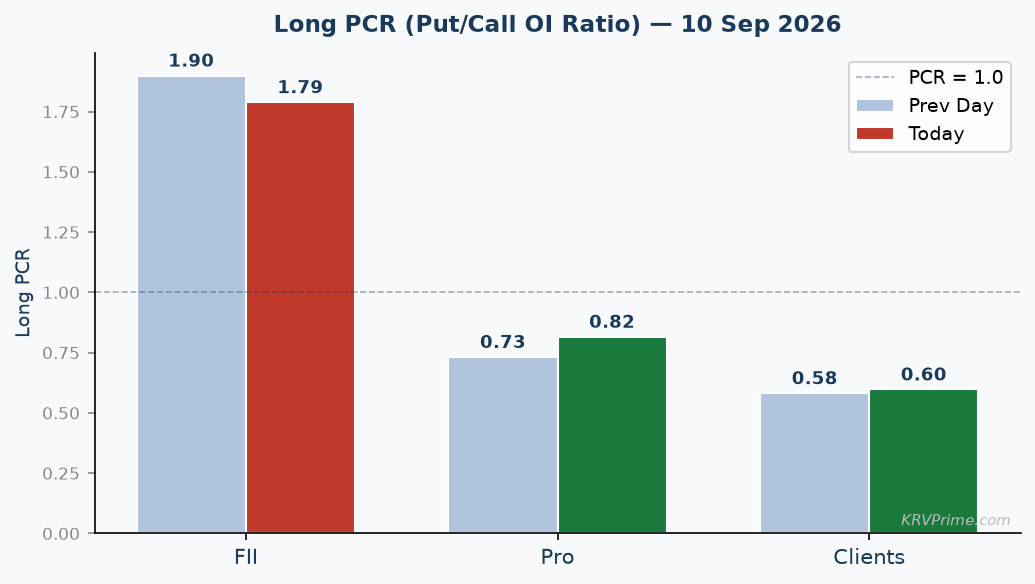
- FII Long PCR declined from 1.90 to 1.79 (change -5.81%) and Short PCR rose from 0.45 to 0.49 (change +7.69%). A Long PCR of 1.79 means FIIs currently hold 79% more put longs than call longs on the options long side — a deeply defensive or outright bearish options architecture where put ownership dominates. The decline in Long PCR from 1.90 to 1.79 suggests FIIs added call longs (+65,051) at a faster pace than put longs (+54,168), partially reducing the put-heavy skew but not reversing it. The Short PCR rising from 0.45 to 0.49 means FIIs are writing relatively more puts versus calls on the short side today, adding 51,656 put shorts versus 41,279 call shorts — this rising Short PCR can be read as premium collection on the put side (implying FIIs believe the downside is bounded in the very near term) while simultaneously writing calls to cap any upside move, consistent with a range-with-downward-bias outlook. The dominant signal remains the Long PCR of 1.79 — FII options longs are structurally put-heavy, reinforcing the futures short thesis.
- Call OI net moved from -342,643 to -318,871 (change +23,772), with Long calls adding 65,051 (prev 563,759 → today 628,810, [Long Buildup - Low Vol]) and Short calls adding 41,279 (prev 906,402 → today 947,681, [Short Buildup - Low Vol]). Put OI net held near steady at +662,764 (change +2,512), with Long puts adding 54,168 (prev 1,070,563 → today 1,124,731, [Long Buildup - Low Vol]) and Short puts adding 51,656 (prev 410,311 → today 461,967, [Short Buildup - Low Vol]). The net options architecture remains: net short calls (-318,871) combined with net long puts (+662,764) — this is a classic synthetic short or protective collar structure, where FIIs cap upside via short calls and profit from downside via long puts. The fact that Short calls remain at 947,681 versus Long calls at only 628,810 confirms call writing dominance overhead. Notably, the slight reduction in net call short from -342,643 to -318,871 came from call longs growing faster than call shorts today, but this does not change the overall bearish architecture — it may reflect tactical hedging of their own short call book.
- Synthesis — FII Dual-Leg Bearish Architecture: FIIs present the most internally consistent and directionally unambiguous positioning story in today's data. Their futures net stands at a dominant -281,844 (a gross short-to-long ratio of 8.1:1), their options long book is put-heavy with a Long PCR of 1.79, they hold net short calls of -318,871 and net long puts of +662,764 — every data point across all three legs (futures, calls, puts) points to the same conclusion: FIIs are positioned for a meaningful downside move or at minimum a capped, range-bound market. What is particularly notable is that FIIs deepened their futures short by 5,594 contracts on a day when Nifty was up +0.20% — they did not cover even modestly, treating the mild green close as an opportunity to add rather than retreat. The rising Short PCR (0.45 → 0.49) adds one mild nuance: short-side put writing has picked up, suggesting FIIs are collecting premium against sharp near-term downside as a tactical buffer, but this does not alter the primary structural short. Compared to the prior session, the net short has continued its incremental deepening trend, and there is no evidence of thesis rotation. The Low Vol confirmation tags on all legs indicate this is managed, systematic positioning rather than reactive trading.
- Forward: The critical futures threshold to watch is whether FII futures net deteriorates further below -285,000 in tomorrow's data — if the short book continues to grow at today's pace (approx -5,594/session), bears retain the upper hand and any intraday Nifty rally above 24,000 (CE OI Resistance) will face a wall of FII-sold calls at that strike. Conversely, if FII futures net improves (covers) toward -270,000 or better, it would be the first meaningful signal of a bearish-to-neutral thesis flip and could unleash a short-covering rally. Watch FII Long PCR — if it drops below 1.60, it indicates active put long reduction and a softening of the defensive stance.
DII Mildly Bullish — Moderating Futures Book With Persistent Put Protection
- DII futures net improved modestly from +14,611 to +14,892 (net change +281 contracts). However, both sides of the futures book shrank: Long futures fell 454 contracts (prev 43,738 → today 43,284, -1.04%) tagged [Long Unwinding - Avg Vol], and Short futures fell 735 contracts (prev 29,127 → today 28,392, -2.52%) tagged [Short Covering - Avg Vol]. The Avg Vol tags on both legs indicate this is routine institutional book trimming rather than high-conviction strategic repositioning. The net improvement of +281 is entirely a function of Short Covering (-735) outpacing Long Unwinding (-454) — DIIs removed more shorts than longs today, leaving their net long position marginally larger. The gross long-to-short ratio remains solidly in DII's favor at 43,284 ÷ 28,392 = 1.52:1, a modest but consistent net long bias that contrasts sharply with FII's 8.1:1 gross short dominance. DIIs appear to be in a quiet consolidation phase — neither aggressively building longs nor panicking out, but gently reducing the overall futures book size on both sides.
- DII does not report distinct Long PCR and Short PCR metrics in today's data set. However, inferring from the options OI changes: DII's Call OI net stands at +1,500 (Long 5,401 vs Short 3,901) and Put OI net at +50,538 (Long 50,538 vs Short 0) — the implied put-to-call ratio on the long side is approximately 50,538 ÷ 5,401 ≈ 9.4:1, an extraordinarily put-heavy options posture. This massive skew toward put longs with zero put short exposure confirms that DIIs are running a structural options hedge — they are not collecting put premium, they are buying and holding puts as outright downside protection for their underlying equity book. The DII call position is minimal and modestly net long (+1,500), suggesting token directional interest on the upside but no conviction call-writing activity. The dominant signal from options is the 50,538 net long put position — this is a large institutional hedge consistent with DIIs managing a significant underlying equity portfolio against tail-risk or near-term correction scenarios.
- Call OI: DII Long calls at 5,401 vs Short calls at 3,901 (net +1,500); Long calls added +200 contracts (prev 5,201 → today 5,401, [Long Buildup - High Vol]), Short calls added +134 (prev 3,767 → today 3,901, [Short Buildup - Low Vol]). The High Vol tag on call longs is notable — despite the small absolute number of contracts (+200), the High Vol signal means this was a deliberate, high-conviction addition. Put OI: DII Long puts at 50,538 vs Short puts at 0 (net +50,538); Long puts added +865 contracts (prev 49,673 → today 50,538, [Long Buildup - Low Vol]), and Short puts remain at 0 with [Short Flat - Avg Vol]. The combination of net long calls (+1,500) and net long puts (+50,538) creates a long strangle or protective long options posture — DIIs are long both upside optionality (calls) and downside protection (puts) with no short options exposure whatsoever. This is the profile of a participant that is hedging a large underlying equity book with a pure long options strategy, not generating income through writing. The zero short-put exposure is rare and emphatic: DIIs have absolutely no desire to sell downside protection at current levels.
- Synthesis — DII Structural Equity Hedge With Consolidating Futures: DIIs are operating in two distinct but complementary modes today. In futures, they are a quiet net long (+14,892) with a slowly consolidating book — Avg Vol unwinding on both sides suggests no urgency, just routine housekeeping as expiry approaches. In options, they are running an aggressive and one-sided long put protection strategy — 50,538 net long puts against zero short puts is an unusually clean hedge posture that leaves no ambiguity about their concern for downside in the underlying equity book they manage. The High Vol tag on the small call long addition (+200 contracts, [Long Buildup - High Vol]) adds a minor bullish nuance — DIIs see some value in upside optionality — but at 5,401 total call longs versus 50,538 put longs, the put-to-call skew of 9.4:1 dominates entirely. Compared to FIIs, DIIs are on the same side structurally (both hold large put long books), but differ in futures: FII is deeply net short futures (-281,844) while DII is modestly net long futures (+14,892). This divergence is classic — DIIs hold equity and hedge with puts; FIIs short futures and buy puts to express and protect an outright bearish view. DII positioning is holding steady relative to prior sessions, with no material change in direction.
- Forward: The key metric to watch for DII tomorrow is whether the put long book at 50,538 continues to grow — if DII put longs expand toward 55,000+, it signals increasing institutional concern and would reinforce the bear case. Conversely, if DII begins reducing put longs (net put long falling below 48,000), it would indicate reduced hedging demand and could signal institutional comfort at current levels, a mild bullish signal. Also watch DII futures net — a break above +16,000 would indicate fresh long futures conviction, supporting the bull case; a drop below +13,000 via continued long unwinding would be incrementally bearish for the institutional demand picture.
Pro Cautiously Bearish — Aggressive Call Writing With Rising Put Longs
- Pro futures net improved from +31,159 to +35,981 (net change +4,822 contracts). The Long side added a substantial 3,435 contracts (prev 63,306 → today 66,741, +5.43%) tagged [Long Buildup - Avg Vol], while the Short side reduced by 1,387 contracts (prev 32,147 → today 30,760, -4.31%) tagged [Short Covering - Low Vol]. The Avg Vol tag on long buildup indicates a moderately deliberate addition of long futures contracts, while the Low Vol short covering suggests the short reduction was thin and may be tactical rather than strategic. The gross long-to-short ratio stands at 66,741 ÷ 30,760 = 2.17:1 in favor of longs — Pros are net long futures with meaningful conviction and have actively improved this position today. This futures net long of +35,981 contrasts sharply with their options posture (discussed below) and creates an important internal divergence worth monitoring. The combination of long futures buildup and short covering today suggests Pros are directionally bullish on futures in the immediate term while using options to generate income and hedge range risk.
- Pro Long PCR rose from 0.73 to 0.82 (change +11.45%) and Short PCR rose from 0.63 to 0.69 (change +9.37%). A Long PCR of 0.82 means Pros hold 82% as many put longs as call longs — they are near-parity between call and put longs, with a slight call-long bias. The sharp +11.45% rise in Long PCR indicates Pros aggressively added put longs today (120,344 contracts) relative to call longs (35,719), pushing the put-to-call ratio higher and increasing the defensive flavor of their long options book. The Short PCR rising from 0.63 to 0.69 means Pros are writing relatively more puts versus calls on their short side today — this is significant because it implies Pros are net short more puts than calls in their writing book, potentially collecting premium against a move to the downside. However, at 0.69, it remains below 1.0, so call writing still dominates their short book in absolute terms. The simultaneous rise in both Long PCR and Short PCR is a complex, slightly contradictory signal: Pros are buying more puts (cautious/bearish) while also writing more puts (range-income/mildly bullish on support holding) — this creates a net-sold strangle-like structure.
- Call OI: Pro Long calls at 1,124,666 vs Short calls at 1,187,456 (net -62,790); a major shift from the prior net of +14,552. Long calls added 35,719 contracts (prev 1,088,947 → today 1,124,666, [Long Buildup - Low Vol]) while Short calls surged by 113,061 contracts (prev 1,074,395 → today 1,187,456, [Short Buildup - Low Vol]). This explosive +113,061 short call addition — nearly three times the long call addition — has flipped Pro's call book from a modest net long to a net short of -62,790 in a single session. Put OI: Pro Long puts at 917,176 vs Short puts at 815,976 (net +101,200); Long puts surged +120,344 (prev 796,832 → today 917,176, [Long Buildup - Low Vol]) while Short puts added 140,897 (prev 675,079 → today 815,976, [Short Buildup - Low Vol]). The net put position remains long but narrowed from +121,753 to +101,200 as short puts grew faster. The overall architecture is now: net short calls (-62,790) combined with net long puts (+101,200) — this is a bearish risk-reversal or collared short, where upside is capped via call writing and downside exposure is held via put longs. Combined with net long futures (+35,981), Pros appear to be running a covered call / collar on their futures longs — long the underlying via futures, writing calls to generate income against the long, and buying puts to protect the long. This is a classic range-capped long futures position.
- Synthesis — Pro Covered Collar Strategy With Bearish Options Lean: Pro traders are executing what appears to be a sophisticated covered collar strategy: net long futures (+35,981, adding +4,822 today), short calls to cap and monetise the upside (-62,790 net, adding 113,061 short calls today), and long puts to protect the downside (+101,200 net, adding 120,344 long puts today). The dramatic single-session call writing surge of +113,061 short calls is the dominant signal here — Pros are aggressively selling upside at the current market level, implying they view 24,000 (CE OI Resistance) as a ceiling they are willing to underwrite. The rising Long PCR (0.73 → 0.82, +11.45%) confirms the simultaneous put-protection buying was not incidental. One key internal tension exists: the futures long (+35,981) is bullish, while the call writing and put buying are both bearish signals — taken together, this is not contradiction but strategy: Pros are earning a premium on a long futures position while hedging it downside and capping upside. Compared to the prior session where Pros were modestly net long calls (+14,552), today's flip to -62,790 is a significant acceleration of the call-writing posture and suggests Pros are not expecting a meaningful breakout above current levels. The Low Vol tags on all legs suggest this was systematic book-building rather than reactive trading.
- Forward: The critical watch point for Pro is whether their short call book at 1,187,456 continues to grow tomorrow — if short calls expand beyond 1,250,000, it confirms Pros are aggressively capping the Nifty upside at 24,000 and the resistance thesis at that CE OI strike strengthens materially. Conversely, if Pros begin covering short calls (net call position improves toward -30,000 or better), it would signal their range view is breaking down and a potential upside acceleration becomes viable. Also watch the futures net — if Pro futures net drops below +30,000 via long unwinding, the collar strategy is being dismantled, which would be a bearish signal for the underlying market.
Client Actively Positioned — Bullish Futures With Heavy Two-Way Options Activity
- Client futures net moved from +230,480 to +230,971 (net change +491 contracts), a near-unchanged reading. The Long side added 3,385 contracts (prev 283,444 → today 286,829, +1.19%) tagged [Long Buildup - Low Vol], while the Short side added 2,894 contracts (prev 52,964 → today 55,858, +5.46%) tagged [Short Buildup - Avg Vol]. The contrast in volume tags is meaningful: Long buildup is tagged Low Vol (hesitant, thin conviction longs) while Short buildup is tagged Avg Vol (more deliberate short additions). The gross long-to-short ratio is 286,829 ÷ 55,858 = 5.13:1 — Clients remain massively net long futures relative to their short book. However, the Avg Vol tag on short buildup suggests some retail and proprietary client accounts are beginning to add short futures hedges as a tactical measure against the strong existing long book, creating a slight drag on the net. At +230,971, Clients are the largest net long futures participant by a significant margin, acting as the bullish counterweight to FII's massive net short of -281,844.
- Client Long PCR rose from 0.58 to 0.60 (change +2.68%) and Short PCR declined from 0.91 to 0.89 (change -1.96%). A Long PCR of 0.60 means Clients hold 60 put longs for every 100 call longs — they are firmly in a call-dominant long options posture, skewed toward upside participation. The modest rise in Long PCR (+2.68%) confirms that today's massive put long addition (+340,509 contracts) was even larger than the call long addition (+480,054) in proportional terms, gently nudging the ratio toward parity — but Clients remain call-biased by a meaningful margin. The Short PCR declining from 0.91 to 0.89 means Clients are writing slightly more calls relative to puts on the short side today — call writing is growing faster than put writing, which is a mildly bearish signal for the short book (selling calls = capping upside on a portion of positions). However, at 0.89, Short PCR remains close to 1.0, indicating near-parity between call and put writing on the short options side. The dominant signal is the Long PCR of 0.60 combined with the vast absolute scale of Client call longs (3,945,571) — Clients are the largest call-long participant in the market, driving significant upside directional exposure.
- Call OI: Client Long calls at 3,945,571 vs Short calls at 3,565,411 (net +380,160); Long calls surged by +480,054 (prev 3,465,517 → today 3,945,571, [Long Buildup - Low Vol]) while Short calls added +426,550 (prev 3,138,861 → today 3,565,411, [Short Buildup - Low Vol]). Both legs carry Low Vol tags despite the enormous absolute contract volumes — this reflects that Client category is the largest retail and proprietary segment, and these additions, while massive in contracts, are spread across a broad participant base and are proportionally normal relative to their typical volume. Put OI: Client Long puts at 2,355,516 vs Short puts at 3,170,018 (net -814,502); Long puts surged +340,509 (prev 2,015,007 → today 2,355,516, [Long Buildup - Low Vol]) while Short puts added +323,333 (prev 2,846,685 → today 3,170,018, [Short Buildup - Low Vol]). The net options architecture is: net long calls (+380,160) combined with net short puts (-814,502) — this is a synthetic long or bullish risk-reversal, where Clients own upside via call longs and underwrite downside via put shorts. This bullish options architecture perfectly complements their massive futures long position of +230,971. The sheer scale of Client put writing (3,170,018 short puts) suggests a large segment of the Client category is collecting put premium, betting that the 23,000 PE Support will not be breached.
- Synthesis — Client Dominant Synthetic Long Across Futures and Options: Clients are running the most uniformly bullish positioning structure of all four participant categories today. Their futures net of +230,971 (5.13:1 gross long ratio), combined with +380,160 net long calls and -814,502 net short puts, creates a triple-layered synthetic long — they are long the underlying via futures, long calls for leveraged upside, and short puts to earn premium while doubling down on downside support. This is the structural opposite of FII's dual-leg short: FII is short futures + short calls + long puts; Client is long futures + long calls + short puts. The two categories are in direct opposition, and with FII futures net at -281,844 and Client futures net at +230,971, the net futures balance across these two participants alone stands at approximately -50,873 — FIIs are currently winning the net futures tug-of-war by a narrowing margin. The massive put writing by Clients (3,170,018 short puts, +323,333 today) is particularly important: it concentrates significant risk at the 23,000 PE Support strike, as any break below that level would trigger forced short-put covering and amplify downside momentum. Compared to the prior session, Clients have accelerated their activity on both sides — +480,054 call longs and +340,509 put longs with +426,550 call shorts and +323,333 put shorts — reflecting high engagement but low per-trade conviction (Low Vol tags throughout).
- Forward: The key trigger for Client positioning is the 23,000 PE Support level — Client short put concentration near this strike means a breach of 23,000 would force covering of 3,170,018 short puts and create a negative gamma cascade. Watch whether Client short put OI continues to grow tomorrow — if it expands beyond 3,300,000, it confirms increasing bullish conviction on support holding, which also means the potential unwinding snap is growing larger. Conversely, if Client short puts begin reducing (falling toward 2,900,000 or below), it signals retail and proprietary accounts are defensive-covering their put short book, an early warning of expectation for a deeper market correction.
Bull vs Bear Strength by Participant
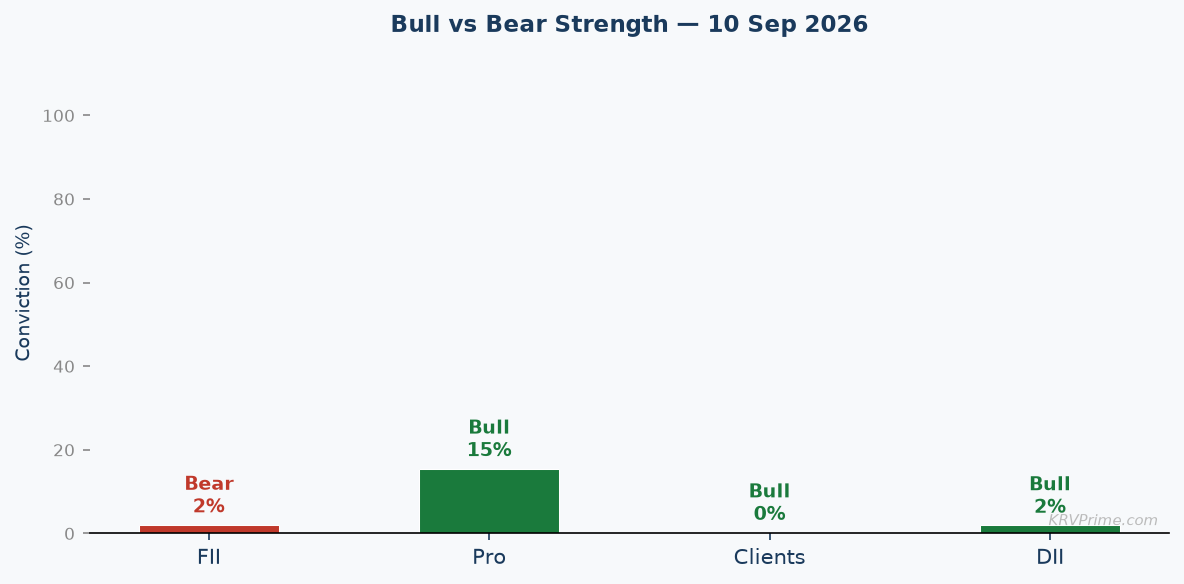
FII Strongly Bearish 85% ▼▼ | Client Bullish / Leveraged Long 70% ▲▲ | Pro Cautiously Bearish / Collared 60% ▼ | DII Mildly Bullish / Hedged 55% ▲ |
Conclusion — Market Outlook for Tomorrow (10 Sep 2026)
The collective participant positioning on 10 Sep 2026 reveals a market in a tug-of-war between a deeply entrenched FII short and an equally committed Client long, with Pros tilting toward the bear camp through aggressive call writing. FIIs carry the dominant directional signal: a futures net of -281,844 (8.1:1 gross short ratio), net short calls of -318,871, and net long puts of +662,764 represent an interlocking three-leg bearish structure that has been consistently deepened over recent sessions with no sign of thesis reversal. Clients, in direct opposition, hold futures net +230,971 (5.13:1 long ratio), +380,160 net long calls, and -814,502 net short puts — a synthetic long of enormous scale. Pro traders have broken decisively into the bearish options camp today, adding +113,061 short calls in a single session to create a -62,790 net short call position, effectively selling upside at current levels alongside FII. DIIs sit on the sidelines with a modest futures net long of +14,892 and a massive +50,538 net long put book — structurally neutral-to-defensive rather than aggressively directional. The net balance of power, when weighed by conviction strength (evidenced by volume tags and absolute contract size), leans toward the FII-Pro bearish camp holding the dominant options supply-side control, particularly at the 24,000 CE OI Resistance where call writing is concentrated.
The Overall PCR of 0.78 (prev 0.77, +1.59%) shows a mild incremental improvement in put-to-call ratio as put OI (+13.12%) grew faster than call OI (+11.34%) today — a modestly encouraging signal for the bull camp, as rising PCR typically reflects increasing hedging or put-buying activity that can later convert into buying fuel. However, at 0.78, PCR remains well below the neutral 1.00 threshold, confirming that the market is still structurally call-heavy and lacks the defensive put-floor buying typically associated with strong institutional bullish conviction. India VIX at 11.79 (down -1.05% from prev 11.92) remains in a deep complacency zone — the continued VIX compression even as total OI expands by +5.48% suggests participants are adding positions at suppressed volatility premiums, a condition that favors option writers (FII and Pro call writers) over option buyers. A VIX this low also means there is limited fear premium in the market, so any unexpected volatility spike — whether from macro news or a break of the 23,000 PE Support — could trigger rapid premium expansion and forced position covering. Total OI expanding by +2,569,688 contracts to 49,419,238 confirms this is a fresh-positioning session, not stale carry — the market is building new bets ahead of what both bulls and bears expect to be a decisive directional move.
The scenario that would change the current cautious-bearish thesis is a material improvement in FII futures net — specifically, if FII net shorts reduce toward -265,000 or better (a short covering of approximately 16,000+ contracts), it would signal institutional capitulation on the short side and could fuel a sharp upside move toward and potentially through the 24,000 CE OI Resistance. On the downside, if the 23,000 PE Support is breached on closing basis, Client short put holders (3,170,018 contracts) would face forced covering, creating a negative gamma feedback loop. The PCR crossing above 0.90 would add incremental bullish confirmation; a PCR deteriorating below 0.70 would confirm bears are taking control of the options market structure. VIX breaking above 13.50 would signal volatility regime shift and broadly supportive for put longs held by FII and DII.
Scenario 1 — Bull case:
If FII futures net improves toward -265,000 (short covering of ~16,000+ contracts) accompanied by a rise in Overall PCR above 0.90 and VIX sustaining below 11.50, the short-covering momentum could push Nifty toward the 24,000 CE OI Resistance. A break and close above 24,000 — which would require Pro and FII short calls at that strike to be covered — would trigger a negative-gamma squeeze for call writers and could accelerate the move toward 24,500+. Client synthetic long architecture (+380,160 call longs, +230,971 long futures) is already positioned to profit maximally in this scenario.
Scenario 2 — Bear case:
If FII continues to deepen futures net shorts below -290,000 and Pro short call OI expands beyond 1,250,000 contracts, the combined supply-side pressure at 24,000 and above becomes structurally overwhelming. A PCR deterioration below 0.72 combined with VIX breaking above 13.00 would confirm volatility expansion and defensive put-buying, supporting FII's +662,764 net long put book. A closing breach of the 23,000 PE OI Support level would force Client short put covering (3,170,018 contracts) and DII long puts (50,538) to be monetised, potentially accelerating a move toward 22,500 on heavy volume.
Key Resistance 24,000 (Nifty CE OI Resistance / 57,500 BankNifty / 75,000 Sensex Week) — FIIs hold 947,681 short calls and Pros hold 1,187,456 short calls at this zone; the combined call writing supply from these two institutional participants creates a formidable structural ceiling. Any rally into this zone will face aggressive call writer defence unless FII futures net improves materially first. | Key Support 23,000 (Nifty PE OI Support / 54,000 BankNifty / 74,000 Sensex Month) — FIIs hold 1,124,731 long puts, DIIs hold 50,538 long puts, and Clients hold 2,355,516 long puts concentrated near this strike zone, creating a formidable put-long demand cushion. However, Client short puts of 3,170,018 create a double-edged dynamic — a breach of 23,000 could trigger forced short-put covering, making this level a critical inflection point rather than a simple support. | Trigger to Watch FII futures net crossing -270,000 (short covering of ~11,844 contracts) OR Overall PCR rising above 0.90 — either event would confirm a shift in institutional supply-demand balance. Simultaneously, watch Total OI: if tomorrow's session brings another +5%+ OI expansion accompanied by PCR improvement, it confirms new money entering the bull side. If OI expands but PCR deteriorates below 0.72, it confirms fresh bear-side dominance. |