
Market Participants Analysis dated 15.09.2026
KRVPrime — Daily Market Outlook
Key Market Signals — Data: 15 Sep 2026
NIFTY 50 23,118.60 ▼ -279.50 (-1.19%) | BANK NIFTY 55,794.75 ▼ -811.80 (-1.43%) | SENSEX 74,003.82 ▼ -777.94 (-1.04%) |
OVERALL PCR 0.83 ▼ -0.17 (-16.83%) PCR collapsed from 1.00 to 0.83 — put unwinding heavily outpaced call unwinding, signalling deteriorating bullish sentiment | INDIA VIX 13.43 ▲ +1.14 (+9.34%) VIX surged 9.34% to 13.43 on a down day — fear re-entering market; elevated but not extreme | TOTAL OI CHANGE 45,251,264 ▼ -7,089,242 (-13.54%) Massive OI destruction of 7.09M contracts — expiry-linked or panic unwind; net bearish tone |
FUTURES OI 901,770 ▲ +25,848 (+2.95%) Futures OI rising on a down day = fresh short buildup adding directional conviction to the sell-off | CALL OI CHANGE 8,398,706 ▼ -3,009,845 (-26.38%) Call OI shed 26.38% — aggressive call long unwinding and short covering; supply structure weakening | PUT OI CHANGE 6,973,670 ▼ -4,415,885 (-38.77%) Put OI collapsed 38.77% — put longs monetised heavily on the down move; hedges cashed out |
Participant-wise Key Points
FII Strongly Bearish — Accelerating Dual-Leg Short Conviction
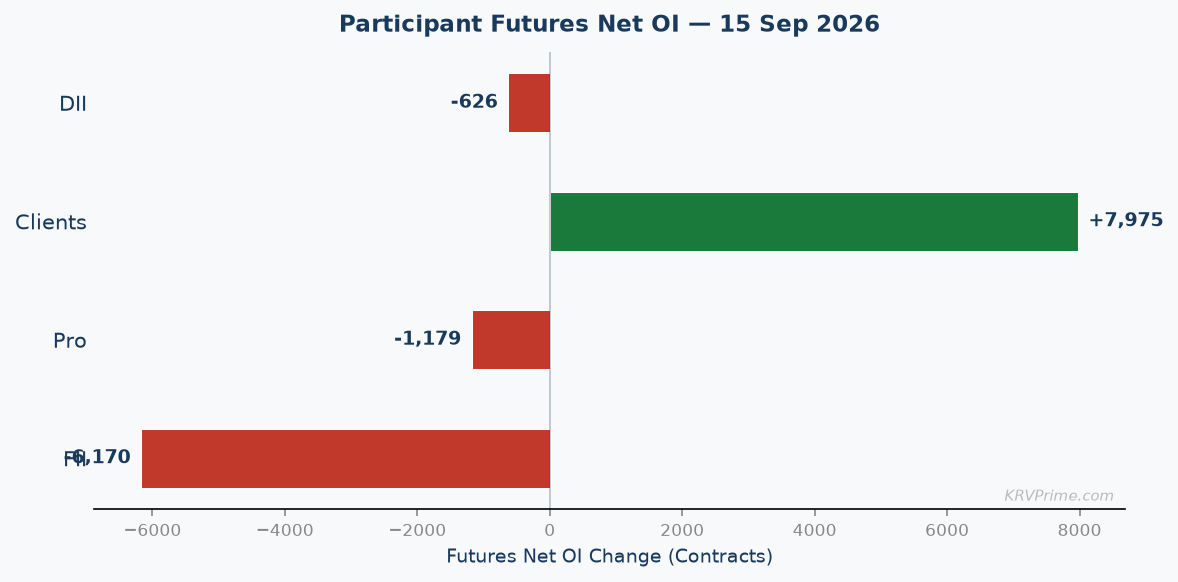
- Futures net deteriorated from -284,882 to -291,052 (net change -6,170 contracts). On the long side, FIIs added 5,006 contracts (prev 41,252 → today 46,258, +12.14%) tagged [Long Buildup - High Vol], while simultaneously adding 11,176 contracts on the short side (prev 326,134 → today 337,310, +3.43%) tagged [Short Buildup - High Vol]. Both legs carry High Vol tags, meaning both the long addition and the short addition were deliberate, high-conviction moves — not routine rollovers. The gross short-to-long ratio stands at a striking 7.29:1 (337,310 short vs 46,258 long), which is an unambiguous expression of outright directional bearishness; this is not a hedged book but a dominant short position that has deepened by a further 6,170 net contracts on today's decline, confirming FIIs are pressing their short thesis rather than covering into market weakness.
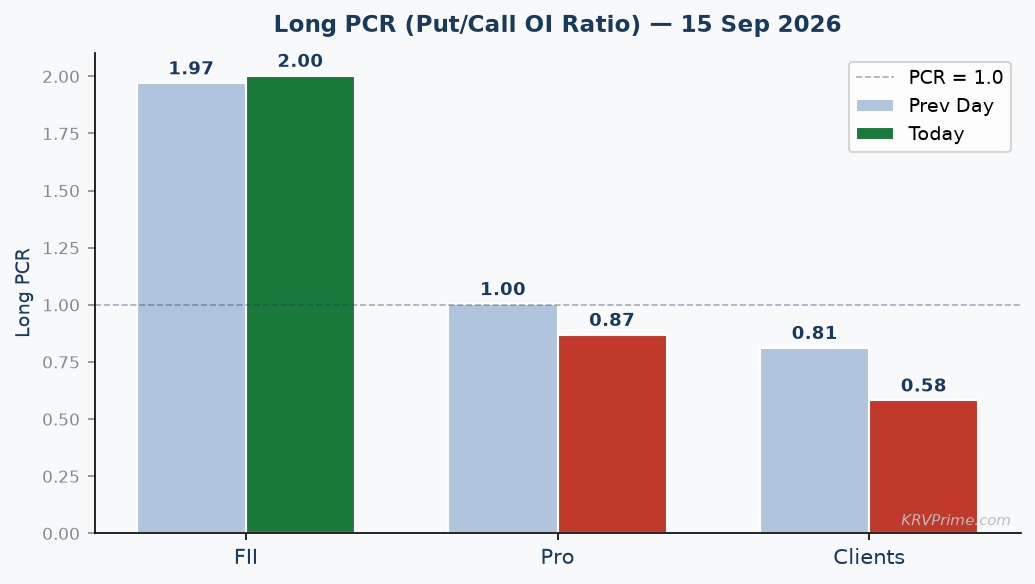
- Long PCR moved from 1.97 to 2.00 (+1.66%) and Short PCR collapsed from 0.69 to 0.45 (-34.32%). The Long PCR of 2.00 means FIIs hold exactly twice as many put longs as call longs in their options book — a deeply defensive posture that either protects a large equity long book or expresses a direct bearish directional view through options; the marginal rise from 1.97 to 2.00 shows this put-heavy tilt is not declining but gently reinforcing. The Short PCR crash from 0.69 to 0.45 is the most critical signal here — a Short PCR of 0.45 means FIIs are writing more than twice as many calls as puts on their short side, indicating they are aggressively capping upside by selling calls rather than monetising puts, a classic range-ceiling strategy layered on top of their futures shorts. The combination of a rising Long PCR (more put longs) and a collapsing Short PCR (more call writing relative to put writing) creates a coherent and internally consistent bearish framework — they are simultaneously buying downside protection and selling upside participation. This PCR configuration reinforces rather than contradicts the futures short book.
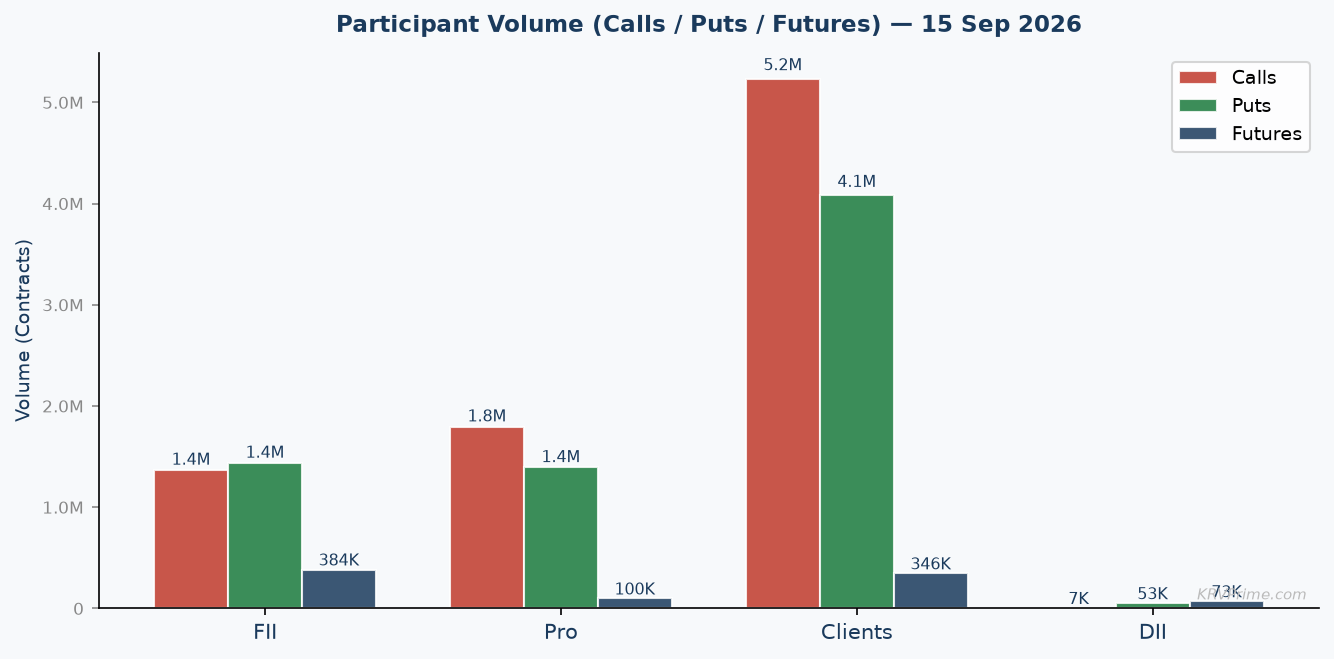
- Call OI net moved from -287,098 to -313,041 (Long 528,339 [Long Unwinding - High Vol], Short 841,380 [Short Covering - High Vol]; net change -25,943). Put OI net moved from +669,711 to +678,520 (Long 1,058,367 [Long Unwinding - High Vol], Short 379,847 [Short Covering - High Vol]; net change +8,809). On the call side, FIIs unwound 147,453 long call contracts and covered 121,510 short call contracts, with the unwinding outpacing the covering — the net call position worsened by 25,943 contracts, meaning FIIs became even more net-short calls despite both legs contracting. On the put side, FIIs unwound 273,239 long put contracts and covered 282,048 short put contracts, with covering slightly outpacing unwinding — net put position improved marginally by 8,809 contracts. The overall architecture remains a net short calls + net long puts = synthetic short / protective collar structure, confirming that options positioning is fully aligned with the futures short book. The High Vol tag on all four options legs confirms these are deliberate, active decisions made with full market awareness of today's sell-off.
- Synthesis — FII Dual-Leg Conviction Bearish Acceleration: FIIs today present the most internally consistent and conviction-heavy bearish architecture across all four participants. Every data point — futures net of -291,052 (deteriorating by 6,170), gross short-to-long ratio of 7.29:1, Long PCR rising to 2.00, Short PCR collapsing to 0.45, net short calls at -313,041, and net long puts at +678,520 — points in precisely the same direction: FIIs believe the market has further downside and they are pressing that view with increasing aggressiveness. Rather than covering into today's -1.19% Nifty decline, they added fresh shorts, which is a particularly strong signal — short-sellers who do not cover on a move in their favour are expressing confidence that the move is not yet complete. The High Vol confirmation tags on all major legs eliminate the possibility that this is mechanical or expiry-related positioning; these are active, high-conviction decisions. Compared to the prior session where net was -284,882, today's deepening to -291,052 represents an acceleration of the bearish thesis, not a pause or reversal. The strategy is best described as a multi-leg synthetic short with put-financed upside capping — futures short as the core position, long puts as tail risk monetisation, and short calls as premium income while capping any recovery.
- Forward: Watch whether FII futures net crosses -295,000 in tomorrow's data — if gross shorts push through 340,000 contracts with the High Vol tag intact, it confirms a new leg of institutional selling is underway and Nifty's 23,000 PE support (monthly OI level) will come under direct test. Conversely, if FII futures net improves back above -285,000 (i.e. short-covering begins), that would be the first signal of thesis exhaustion and could spark a sharp short-covering rally. The key PCR trigger to monitor is whether overall PCR recovers back above 0.90 — a failure to recover would validate FII's bearish read.
DII Mildly Bearish — Defensive Unwind with Reduced Put Coverage
- Futures net deteriorated marginally from +14,348 to +13,722 (net change -626 contracts). On the long side, DIIs reduced by 503 contracts (prev 43,743 → today 43,240, -1.15%) tagged [Long Unwinding - High Vol], while adding 123 contracts on the short side (prev 29,395 → today 29,518, +0.42%) tagged [Short Buildup - High Vol]. Despite the small absolute numbers, the High Vol tag on the long unwinding is significant — it indicates that even the modest 503-contract reduction in longs was a deliberate, conviction-driven decision rather than mechanical roll activity. The gross long-to-short ratio remains modestly positive at 1.46:1 (43,240 long vs 29,518 short), meaning DIIs are still net long futures but are gradually eroding that position; the marginal addition to shorts alongside long reduction shows a gentle shift toward caution without a wholesale position reversal.
- DII options data does not carry a published Long PCR or Short PCR for this session, so no direct PCR comparison is available. However, from the raw options OI, we can derive that DII holds 53,470 put longs versus 5,101 call longs, implying an effective long-side put-to-call ratio of approximately 10.48:1 — an extremely defensive posture that is characteristic of institutional bodies using index puts as portfolio insurance rather than pure speculation. On the short side, DII holds 1,710 call shorts and zero put shorts, meaning their entire short-options book consists of uncovered call writing, which is consistent with a range-capping overlay on a mildly bullish futures book. The absence of any short puts is notable — DIIs are not writing puts for income, which would be the natural complement to a long futures position; instead they are exclusively long puts and short calls, reinforcing the defensive read.
- Call OI net improved from +2,051 to +3,391 (Long 5,101 [Long Unwinding - High Vol], Short 1,710 [Short Covering - Low Vol]; net change +1,340). Put OI net deteriorated from +56,824 to +53,470 (Long 53,470 [Long Unwinding - Low Vol], Short 0 [Short Flat - High Vol]; net change -3,354). On the call side, DIIs reduced long calls by 300 contracts but reduced short calls by a larger 1,640 contracts, resulting in a net improvement of +1,340 — despite both legs contracting, the faster covering of short calls improved their net call position. On the put side, the Low Vol tag on the long put unwinding of 3,354 contracts suggests this was not a high-conviction exit but rather a routine reduction of existing protection, potentially monetising some of the day's decline. The overarching options architecture remains net long calls + net long puts = long strangle / long volatility though at much reduced scale, which is an unusual mix but explainable as DIIs holding residual call longs for upside participation while using a large put long book as portfolio insurance — an institutionally conservative strategy.
- Synthesis — DII Cautious Defensive Unwind on Expiry Proximity: DIIs today are in a slow, controlled retreat mode rather than any aggressive repositioning. Their futures net of +13,722 is still positive but has eroded from +14,348, reflecting a mild loss of conviction in longs rather than a directional flip. The High Vol tag on long futures unwinding suggests even this modest reduction was deliberate, meaning DIIs are consciously lightening up on index futures exposure — possibly as a pre-expiry risk management action. Their options book tells a similar story: put long unwinding of 3,354 contracts with a Low Vol tag suggests selective monetisation of gains from the put book after today's decline, while the faster covering of short calls (Low Vol) suggests they are not eager to maintain call-writing positions in a rising VIX environment (VIX at 13.43, +9.34%). Comparing to FIIs, DIIs are directionally mildly aligned — both are becoming marginally more bearish — but DIIs lack the conviction depth and gross position size of FIIs; DII's 43,240 long futures still significantly outnumber their 29,518 shorts, whereas FIIs are running a 7.29:1 short-dominant book. DIIs appear to be hedging against the market's weakness rather than expressing a directional view.
- Forward: Watch DII put OI position tomorrow — if put longs stabilise above 50,000 contracts with a recovery to High Vol confirmation, it signals DIIs are re-establishing protective coverage and expect further volatility. If put longs continue to erode below 50,000 with Low Vol tags, it would indicate DIIs believe the worst of the selling is over and they are releasing hedges, which would be a mildly bullish contrarian signal. The key level to monitor is whether Nifty holds the 23,000 monthly PE support — DII behaviour around that level will reveal whether they are accumulating long futures or adding to the short book.
Pro Bearish Flip — Net Short Calls for First Time with Expanding Put Longs
- Futures net deteriorated from +39,046 to +37,867 (net change -1,179 contracts). On the long side, Pros added 2,125 contracts (prev 66,613 → today 68,738, +3.19%) tagged [Long Buildup - High Vol], while also adding 3,304 contracts on the short side (prev 27,567 → today 30,871, +11.99%) tagged [Short Buildup - High Vol]. Both legs saw High Vol buildup, meaning Pros are simultaneously building longs and shorts in futures — a classic straddle-like futures approach where they add exposure on both sides, but the short addition of +3,304 outpaced the long addition of +2,125, causing the net to deteriorate by 1,179 contracts. The gross long-to-short ratio stands at 2.23:1 (68,738 long vs 30,871 short), which is still net bullish in structure but the faster growth on the short side signals Pros are hedging their long book more aggressively or beginning to shift bias — the net positive futures position is now incrementally weaker than yesterday's +39,046.
- Long PCR collapsed from 1.00 to 0.87 (-13.43%) and Short PCR collapsed from 1.03 to 0.70 (-32.23%). The Long PCR drop from 1.00 to 0.87 is highly significant — Pros moved from a perfectly balanced call-long/put-long book to a position where they hold 13% more call longs than put longs, signalling a reduction in defensive put accumulation on the long side; this is the opposite of what we would expect from a bearish participant adding downside protection, and creates a notable internal contradiction with their net futures deterioration. The Short PCR collapse from 1.03 to 0.70 is even more dramatic — Pros shifted from writing roughly equal puts and calls to writing 43% more calls than puts on the short side, meaning they are now primarily selling calls rather than puts, which is consistent with a view that the market's upside is capped. Reading both PCR signals together: Pros reduced their put-long protection (falling Long PCR) while simultaneously increasing their call-writing activity (falling Short PCR) — the dominant signal is that Pros believe the market will not recover sharply and are positioning to capture premium from call selling in a capped environment.
- Call OI net flipped from +55,386 to -125,118 (Long 833,958 [Long Unwinding - High Vol], Short 959,076 [Short Covering - High Vol]; net change -180,504). Put OI net improved from +26,585 to +55,491 (Long 725,089 [Long Unwinding - High Vol], Short 669,598 [Short Covering - High Vol]; net change +28,906). The call side is the most dramatic development in today's entire dataset — Pros flipped their call OI net from +55,386 to -125,118, a swing of 180,504 contracts, as call long unwinding of 341,182 contracts far outpaced short call covering of 160,678 contracts. Simultaneously, put short covering of 484,127 contracts outpaced put long unwinding of 455,221 contracts by 28,906 contracts, improving their net put position. The resulting architecture is now net short calls at -125,118 + net long puts at +55,491 = a nascent synthetic short structure — the same directional architecture as FIIs, though smaller in scale. This is a meaningful structural flip from yesterday's net long calls position and confirms Pros are actively repositioning for a continuation of the bearish trend.
- Synthesis — Pro Structural Flip to Synthetic Short via Options Rebalancing: Pros executed the most dramatic intraday repositioning of any participant today. The flip of their call OI net from +55,386 to -125,118 — a 180,504-contract swing — is the single largest directional options move in today's dataset, and it occurred with High Vol tags on all four options legs, confirming this was entirely deliberate. Combined with improving put net from +26,585 to +55,491, Pros now carry a net short calls + net long puts options structure that mirrors FII's synthetic short framework, even as their futures book remains nominally net long at +37,867. This creates a strategic layering effect: the futures long acts as a hedge against the short options (limiting gamma risk on the call shorts) while the net options position expresses the true directional view — bearish. The Short PCR collapsing to 0.70 confirms the call-writing acceleration. Critically, Pros' Long PCR falling to 0.87 shows they are not accumulating put longs at the same pace as they are selling calls — meaning their downside protection is not keeping pace with their upside-selling activity, implying either confidence that the market will remain suppressed or an asymmetric risk strategy. Compared to yesterday, this is a clear acceleration of bearishness and represents a substantive thesis change, not incremental adjustment.
- Forward trigger: The key watch is whether Pros' call OI net deepens further below -125,118 in tomorrow's data — if it moves toward -200,000 with another High Vol confirmation, it would signal Pros are committed to a full synthetic short strategy and are likely anticipating a test of 23,000 Nifty monthly PE support. Alternatively, if Pros begin covering their call shorts and the net recovers back toward -50,000 or better, it would suggest the call-writing was opportunistic and tied to today's volatility spike rather than a sustained directional view. Monitor overall PCR — if it fails to recover above 0.90 tomorrow, Pros' call-writing thesis remains valid.
Client Net Long Futures but Aggressively Unwinding Options Hedges — Cautiously Bullish
- Futures net improved from +231,488 to +239,463 (net change +7,975 contracts). On the long side, Clients added 6,296 contracts (prev 286,353 → today 292,649, +2.20%) tagged [Long Buildup - High Vol], while reducing short exposure by 1,679 contracts (prev 54,865 → today 53,186, -3.06%) tagged [Short Covering - Avg Vol]. The High Vol tag on the long buildup confirms the 6,296-contract addition was a deliberate, conviction-driven increase in long futures exposure — Clients are buying dips rather than selling into the decline. The Avg Vol tag on the short covering is notable — it means the 1,679-contract short reduction was routine rather than panic-driven, suggesting Clients are calmly reducing shorts rather than desperately covering. The gross long-to-short ratio stands at 5.50:1 (292,649 long vs 53,186 short), the highest among all participants, confirming Clients are structurally the most net-bullish participant in futures — a stark contrast to FIIs running a 7.29:1 short-to-long ratio.
- Long PCR collapsed from 0.81 to 0.58 (-28.29%) and Short PCR fell from 1.07 to 1.02 (-5.16%). The Long PCR crash from 0.81 to 0.58 is the most dramatic Long PCR move among all participants today — it means Clients now hold 42% more call longs than put longs, a decisively bullish tilt that reflects aggressive unwinding of put protection on a down day; Clients are reducing their downside hedges as the market falls, which is consistent with a dip-buying mentality. The Short PCR declining from 1.07 to 1.02 shows Clients are slightly reducing their net-put-writing advantage on the short side — at 1.02, they are still writing marginally more puts than calls, which implies they are selling puts (collecting premium, accepting downside risk) while their long futures book absorbs the exposure. The dominant signal from both PCR readings is unambiguously bullish: Clients are reducing downside protection (falling Long PCR), adding to long futures (net +7,975), and maintaining put-writing (Short PCR still above 1.00) — a coherent contrarian bullish strategy that directly contradicts FII and Pro directional bias.
- Call OI net improved from +229,662 to +434,768 (Long 2,831,955 [Long Unwinding - High Vol], Short 2,397,187 [Short Covering - High Vol]; net change +205,106). Put OI net deteriorated from -753,121 to -787,481 (Long 1,649,909 [Long Unwinding - High Vol], Short 2,437,390 [Short Covering - High Vol]; net change -34,360). On the call side, call short covering of 1,221,094 contracts far outpaced call long unwinding of 1,015,988 contracts, improving the net call position by 205,106 contracts — Clients are the dominant participants buying back short calls on this down day, reducing their short-call exposure while retaining more call longs. On the put side, put long unwinding of 1,476,128 contracts outpaced put short covering of 1,441,768 contracts, marginally worsening the already-negative net put position by 34,360 contracts — Clients are shedding put protection faster than they are covering short puts, maintaining their net put-short structure. The architecture is net long calls at +434,768 + net short puts at -787,481 = synthetic long / risk reversal — the most bullish options architecture possible, fully corroborating the long futures position. This directly and sharply contrasts with FIIs (synthetic short) and Pros (emerging synthetic short), setting up the classic institutional-vs-retail divergence.
- Synthesis — Client Contrarian Dip-Buyer with Risk Reversal Architecture: Clients today are executing a textbook contrarian dip-buying strategy across both futures and options. Their futures net improved by +7,975 contracts to +239,463 on a day when Nifty fell -1.19% — they are buyers into weakness, not sellers. Their Long PCR collapsed to 0.58, showing they aggressively reduced put protection precisely when the market fell, which is either extreme confidence or retail-level overconfidence depending on how the market resolves. Their options architecture of net long calls +434,768 and net short puts -787,481 creates a synthetic long / risk reversal — maximum bullish optionality with no downside cushion from puts. Contrasting directly with FIIs: FIIs carry a 7.29:1 futures short-to-long ratio and net long puts of +678,520, while Clients carry a 5.50:1 futures long-to-short ratio and net short puts of -787,481 — these two participants are on precisely opposite sides of the market. Historically, institutional participants (FIIs) tend to have more informational edge than retail clients, so Client bullishness in the face of FII deepening shorts is a risk factor worth monitoring. However, the High Vol tags on Client call long retention and futures building suggest this is not accidental positioning but deliberate dip-buying conviction.
- Forward: The critical trigger for the Client bull case is whether Nifty holds the 23,100 weekly PE support level (OI support) — if the market stabilises above this level tomorrow with Client futures net holding above 235,000, it validates the dip-buying thesis and could trigger a short-covering rally as FII and Pro shorts face pressure. However, if Nifty breaks below 23,000 monthly PE support with Client futures net declining (long unwinding beginning), it would signal even the most bullish participant is capitulating and would strongly accelerate the downside move. Watch overall PCR — a recovery above 0.90 would confirm Client's bullish bet is gaining traction across the broader market.
Bull vs Bear Strength by Participant
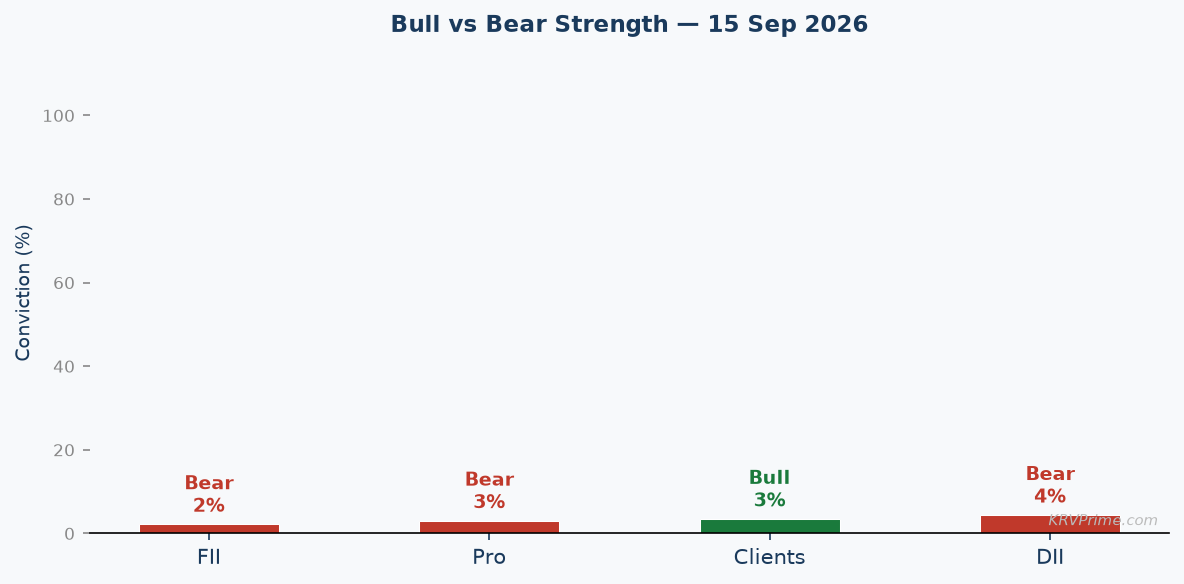
FII Strongly Bearish — Deepening Short 88% ▼▼ | Clients Contrarian Bullish — Dip Buying 70% ▲▲ | Pro Bearish Flip — Synthetic Short 72% ▼ | DII Mildly Bearish — Defensive Unwind 58% ▼ |
Conclusion — Market Outlook for Tomorrow (15 Sep 2026)
The collective participant positioning on 15 Sep 2026 tells an overwhelmingly bearish structural story. FIIs — the dominant informed participant — deepened their futures net short to -291,052 (from -284,882) with a gross short-to-long ratio of 7.29:1, simultaneously reinforcing a net short calls (-313,041) and net long puts (+678,520) options architecture tagged High Vol on all legs. Pros executed the most dramatic repositioning of the session, flipping their call OI net from +55,386 to -125,118 — a 180,504-contract swing — and now mirror FII's synthetic short structure. DIIs, while still nominally net long futures at +13,722, are in a slow retreat, reducing longs and modestly adding shorts. Only Clients stand as the contrarian counterweight, adding +7,975 net futures contracts and running a risk-reversal options structure (net long calls +434,768, net short puts -787,481); their willingness to buy into a -1.19% Nifty decline with High Vol confirmation is notable, but they are positioned against two of the three other major institutional participants, and the weight of institutional positioning remains decisively bearish.
The overall PCR's collapse from 1.00 to 0.83 (-16.83%) is a critical sentiment deterioration signal — a PCR below 0.90 is typically associated with a market that has shifted from balanced to call-heavy (relatively), meaning put protection was removed faster than call hedges, which paradoxically indicates market participants believe the downside move has played out. However, this reading is complicated by the fact that Futures OI simultaneously rose +2.95% to 901,770 contracts on a down day — new shorts being added while PCR fell suggests fresh bearish bets being placed without put protection, which is a different and more ominous interpretation. India VIX surging +9.34% to 13.43 on the same session confirms that option premiums expanded, and the High Vol tags across all major participants validate that today's repositioning was made with full awareness of elevated implied volatility. The combination of rising Futures OI, falling PCR, and rising VIX on a down day is a classic short buildup with fear re-entry configuration, typically associated with continuation of the bearish move rather than an imminent reversal.
The bearish thesis would be invalidated if overall PCR recovers above 0.95 tomorrow with FII futures net improving back toward -280,000 (i.e., meaningful short-covering begins). The key structural support from OI positioning is at 23,100 (weekly PE max OI / OI Support) and 23,000 (monthly PE max OI / OI Support) — a daily close below 23,000 with expanding Futures OI would represent a decisive breakdown of the institutional put-writing floor and would likely trigger accelerated selling. Conversely, if Clients' contrarian long position attracts momentum buyers and Nifty stabilises, the massive put OI destruction today (-38.77% to 6,973,670) means the downside cushion has been significantly reduced — any sharp bounce would have less put-based dampening and could overshoot to the upside toward the 23,300 weekly CE resistance level.
Scenario 1 — Bull case:
If FII futures net improves back above -280,000 (short-covering of at least 10,000 contracts) with overall PCR recovering above 0.95, the bearish thesis loses its dominant institutional anchor. A VIX pullback below 12.50 would confirm fear is receding. Clients' existing synthetic long (net long calls +434,768, net short puts -787,481) would amplify the upside as delta hedging flows turn positive. Nifty target in this scenario is a recovery toward 23,300 (weekly CE OI resistance), with 23,100 weekly OI support acting as the base for the bounce.
Scenario 2 — Bear case:
If FII gross shorts push beyond 340,000 contracts and Pros continue deepening their call net short below -150,000, the combined institutional synthetic short will exert sustained downward pressure. A PCR declining below 0.75 would signal further put protection removal without recovery, and a VIX sustained above 14.00 would confirm elevated market stress. In this scenario, Nifty tests 23,000 (monthly PE OI support) — a break and close below 23,000 with rising Futures OI would expose BankNifty's 54,000 monthly PE support as the next institutional battleground. Client long unwinding at that point would be the confirming signal of full capitulation.
Key Resistance 23,300 (Nifty weekly CE max OI) — FIIs are net short calls with 841,380 gross short call contracts and Pros just flipped to net short calls at -125,118; the combined call-writing pressure from both participants makes the 23,300 strike a significant supply ceiling. Any intraday rally toward this level will face the full force of two institutional participants' call-writing books. | Key Support 23,000 (Nifty monthly PE max OI) and 23,100 (weekly PE max OI) — FIIs hold 1,058,367 long put contracts (net long puts +678,520) and DIIs maintain 53,470 long put contracts, providing a dual-institutional put long cushion at these strikes. However, today's massive put OI destruction of -38.77% means the cushion is significantly thinner than yesterday. A break below 23,000 with Futures OI expansion would signal institutional put-floor abandonment. | Trigger to Watch Overall PCR crossing back above 0.90 with FII futures net improving toward -280,000 — this dual confirmation (PCR recovery + FII short-covering) is the minimum threshold required to flip tomorrow's bias from bearish to neutral. In the absence of this, the rising Futures OI (901,770, +2.95%) on a down day remains the dominant signal, sustaining the short-buildup / bearish-continuation thesis. Also watch India VIX — a sustained move above 14.50 would indicate options premiums are pricing in a larger move than today's -1.19% decline implies. |