
Market Participants Analysis dated 17.09.2026
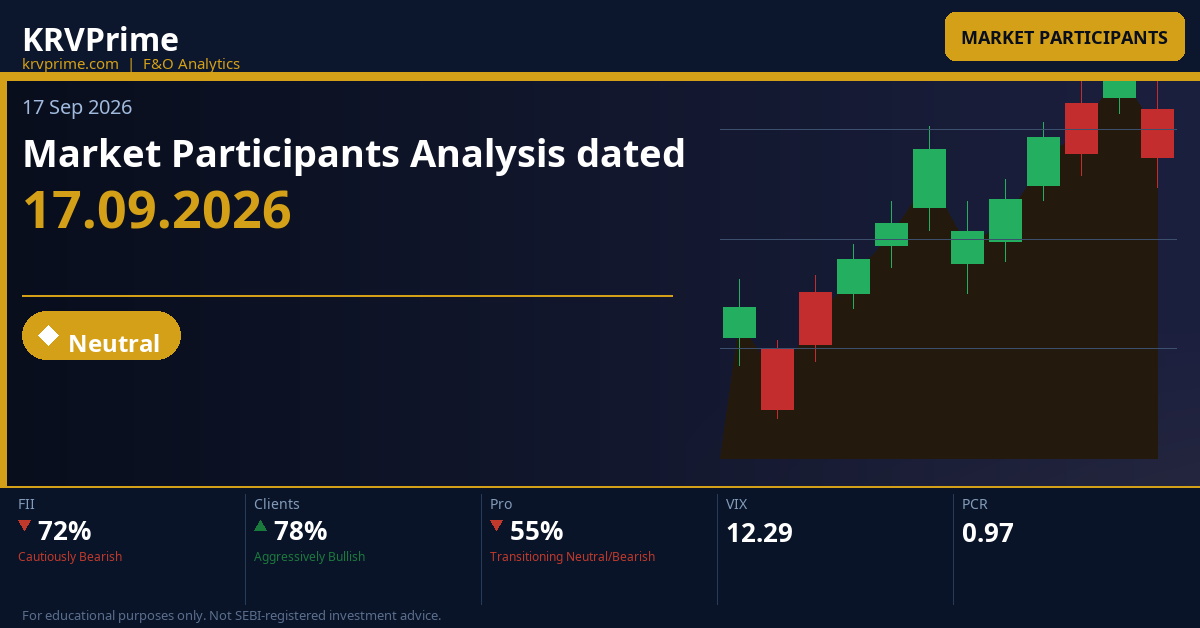
KRVPrime — Daily Market Outlook
Key Market Signals — Data: 17 Sep 2026
NIFTY 50 23,270.60 ▲ +53.00 (+0.23%) | BANK NIFTY 56,055.75 ▼ -236.70 (-0.42%) | SENSEX 74,314.59 ▼ -21.86 (-0.03%) |
OVERALL PCR 0.97 ▲ +0.02 (+1.99%) PCR rising toward 1.0 — puts gaining vs calls, slight tilt toward defensive hedging; market not yet tilted bearish. | INDIA VIX 12.29 ▼ -0.88 (-6.66%) VIX at 12.29 — sharp drop into low-fear zone; complacency risk but short-term supportive of range-bound premium compression. | TOTAL OI CHANGE 50,434,394 ▲ +2,610,644 (+5.46%) Large OI expansion of 5.46% — broad options activity building on both sides; direction contested, not committed. |
FUTURES OI 902,926 ▲ +2,644 (+0.29%) Futures OI nearly flat at +0.29% — minimal net directional commitment in futures; participants preferring options over futures. | CALL OI CHANGE 10,217,722 ▲ +1,137,307 (+12.52%) Call OI surging +12.52% — significant supply being written or bought at upper strikes; resistance reinforced. | PUT OI CHANGE 9,881,382 ▲ +1,270,891 (+14.76%) Put OI expanding even faster than calls at +14.76% — defensive hedging and support-buying both accelerating. |
Participant-wise Key Points
FII Cautiously Bearish — Short Buildup in Futures, Expanding Put Longs with Reduced Hedge Ratio
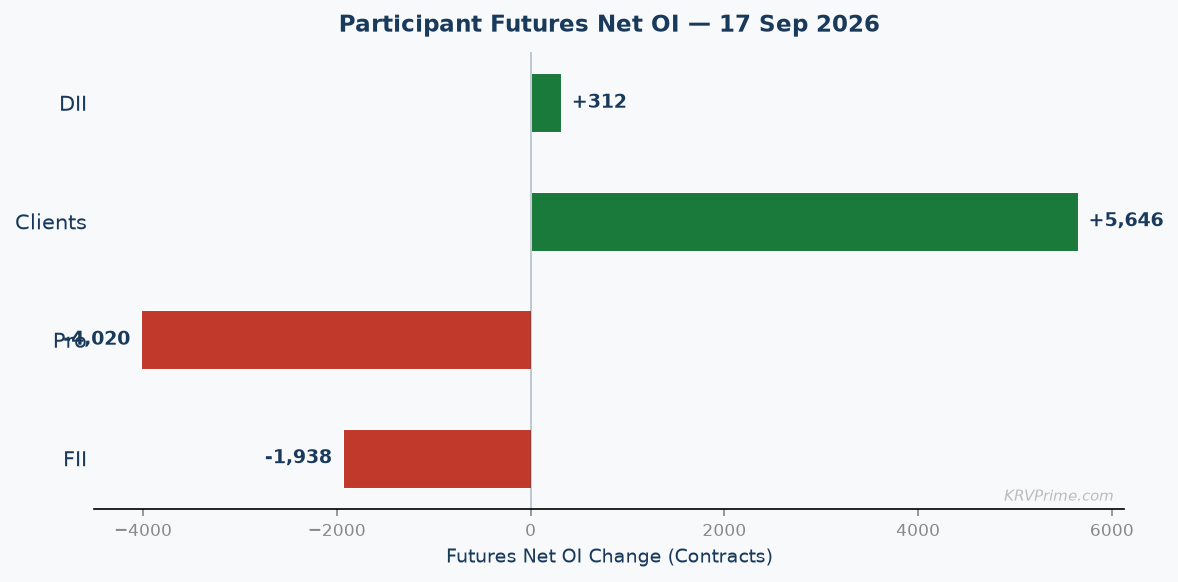
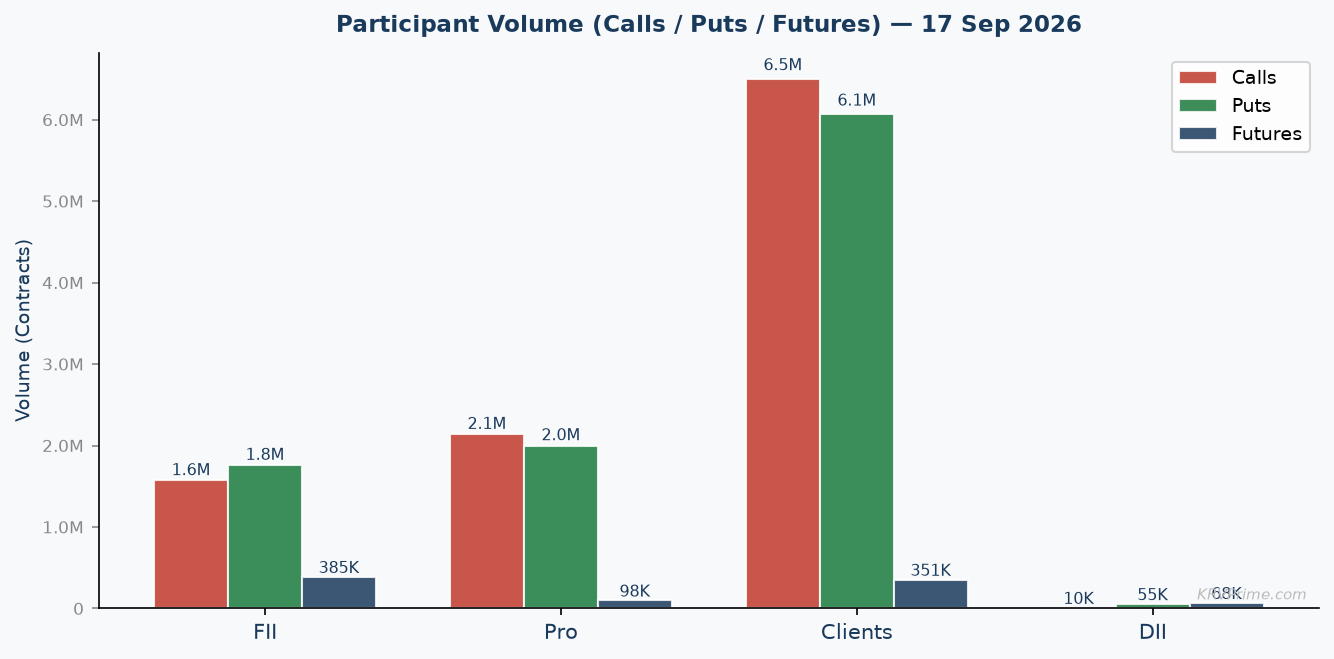
- Futures net deteriorated from -288,103 to -290,041 (net change -1,938 contracts). On the long side, FIIs added a modest 102 contracts (prev 47,446 → today 47,548, +0.21%) tagged [Long Buildup - Low Vol], while on the short side they added 2,040 contracts (prev 335,549 → today 337,589, +0.61%) tagged [Short Buildup - Low Vol]. Both tags carry a Low Vol qualifier, meaning neither the long addition nor the short addition came with strong volume conviction — these are incremental, hesitant moves rather than bold directional bets. The gross short-to-long ratio stands at 337,589 ÷ 47,548 = 7.10:1, which is an overwhelmingly dominant short book — FIIs are not hedging a long equity position here; this is a standalone directional short in futures of clear conviction regardless of the low-volume day. The -1,938 net change, while small, confirms FIIs continue to extend their short bias rather than cover, even as Nifty closed modestly positive at +0.23% — a refusal to cover on a green day is itself a bearish signal.
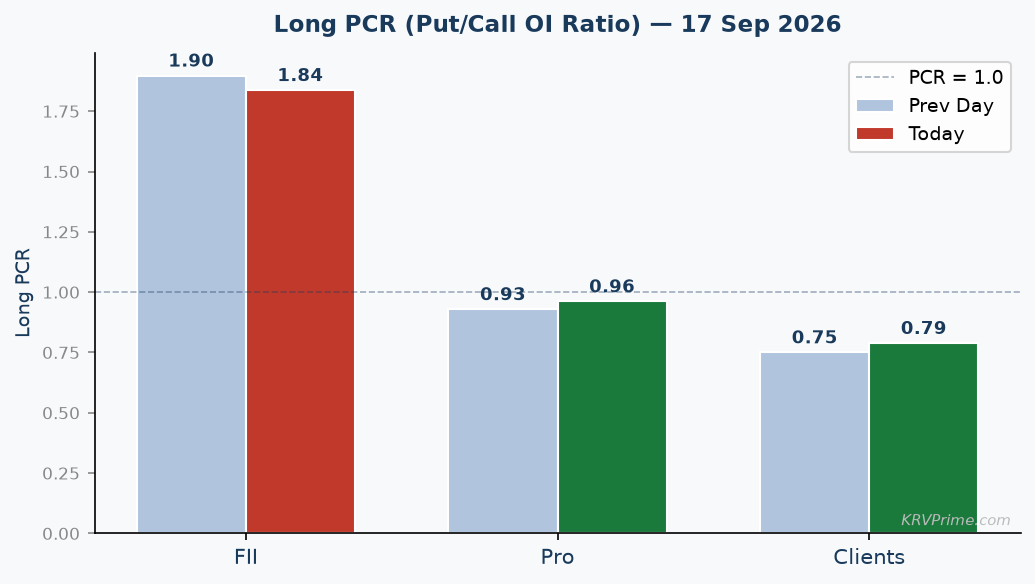
- FII Long PCR fell from 1.90 to 1.84 (change -3.17%) and Short PCR fell from 0.63 to 0.62 (change -1.45%). A Long PCR of 1.84 means FIIs hold 84% more put longs than call longs — this is a deeply defensive or directionally bearish options posture, signalling that every rupee committed to call longs is dwarfed by put-long exposure. However, the decline from 1.90 to 1.84 is notable: FIIs are proportionally growing their call-long book faster than their put-long book today, which introduces a small marginal softening in their bearish options tilt. The Short PCR fell from 0.63 to 0.62, meaning FIIs are writing more calls than puts on the short side — a Short PCR below 1.0 and declining means they are progressively tilting their short options book toward call writing (capping upside) rather than put writing. This short-call dominance is consistent with a market-cap or ceiling thesis, reinforcing the futures short: FIIs appear to believe Nifty has limited upside from here.
- Call OI net changed from -288,206 to -282,892 (net change +5,314, a mild improvement). Long Call OI rose from 598,953 to 645,825 (chg +46,872, +7.83%, tagged [Long Buildup - Low Vol]) while Short Call OI rose from 887,159 to 928,717 (chg +41,558, +4.68%, tagged [Short Buildup - Low Vol]). Put OI net improved from +580,162 to +612,710 (net change +32,548). Long Put OI rose from 1,136,529 to 1,186,632 (chg +50,103, +4.41%, tagged [Long Buildup - Low Vol]) while Short Put OI rose from 556,367 to 573,922 (chg +17,555, +3.16%, tagged [Short Buildup - Low Vol]). FIIs remain net short calls (short 928,717 vs long 645,825) and net long puts (long 1,186,632 vs short 573,922) — a textbook synthetic short or protective collar architecture. The Low Vol tag on all four legs indicates these additions were made without aggressive volume, yet the direction is unambiguously consistent: sell the ceiling, buy the floor protection — a dual-leg expression of controlled downside conviction.
- Synthesis — FII Cautious Bearish Architecture — Incremental Short Extension on a Green Day: FIIs present the most internally consistent directional story today, and the key interpretive point is that their bearish positioning deepened on a day when Nifty rose +0.23%. Their futures net moved further into negative territory at -290,041 (from -288,103), their Long PCR remains at a deeply defensive 1.84 despite minor softening, and their options architecture of net short calls (-282,892) combined with net long puts (+612,710) creates a classic synthetic short that is larger than yesterday's. The Low Vol tags on every single leg are the key nuance: FIIs are not pounding the short desk today — they are making measured, incremental additions that suggest portfolio-level rebalancing rather than panic-driven directional bets. The refusal to cover any meaningful futures shorts on a +0.23% green Nifty day, combined with a 7.10:1 gross short-to-long ratio, indicates FIIs believe the upside move is shallow and unconvincing. Compared to the prior session, FIIs have held their bearish thesis steady and marginally extended it — there is no evidence of capitulation or thesis change.
- Forward: Watch FII futures net tomorrow — if it crosses back above -285,000 (implying net short-covering of more than ~5,000 contracts), it would be the first meaningful signal that FII short conviction is softening and could trigger a squeeze rally in Nifty. Conversely, if FII futures net deteriorates further below -295,000 and their Long PCR climbs back toward 1.90+, the bearish architecture would be reinforcing and the 23,000 NIFTY Monthly PE Support would come under increasing relevance as a downside target zone. The specific OI threshold to watch on the put side is whether FII Long Put OI breaches 1,200,000 contracts — a move through that level would indicate deliberate, scaled-up downside hedging rather than routine rebalancing.
DII Mildly Bullish — Net Long Futures, Expanding Put Longs as Hedge
- Futures net improved from +12,546 to +12,858 (net change +312 contracts). On the long side, DIIs added 65 contracts (prev 40,557 → today 40,622, +0.16%) tagged [Long Buildup - Low Vol], while on the short side they covered 247 contracts (prev 28,011 → today 27,764, -0.88%) tagged [Short Covering - Low Vol]. The net result of simultaneous low-volume long buildup and short covering is a modestly expanding net long of +12,858 — a constructive signal, even if neither leg was executed with high conviction. The gross long-to-short ratio is 40,622 ÷ 27,764 = 1.46:1, meaning DIIs hold approximately 46% more long futures than short futures, which is a controlled bullish lean rather than an outright aggressive long. DII behavior today stands in clear contrast to FII behavior: where FIIs extended their net short, DIIs quietly extended their net long, maintaining the characteristic DII-vs-FII divergence that often acts as a stabilizing force in the market.
- DII PCR data is not reported in the provided data set — no Long PCR or Short PCR values are available for DII. However, directional inference can be drawn from their options positioning: DII Long Put OI significantly exceeds their Long Call OI (see Bullet 3), which implies a high implicit put-to-call long ratio, consistent with an institution that holds long equity exposure and is hedging it with puts rather than speculating directionally with calls. The absence of a formal PCR figure does not dilute this read — the raw OI numbers tell the same story. DII's approach appears to be classic long equity + long put hedge, a posture consistent with their futures net long of +12,858.
- Call OI net: Long 6,939 vs Short 2,690, net +4,249 (prev net +3,576, chg +673). Long Calls rose from 5,539 to 6,939 (chg +1,400, +25.28%, tagged [Long Buildup - High Vol]) — this is the only High Vol tag for DII today, marking it as a deliberate, conviction-weighted call purchase. Short Calls rose from 1,963 to 2,690 (chg +727, +37.04%, tagged [Short Buildup - Low Vol]), meaning some call writing occurred but at lower volume confidence. Put OI net: Long 54,885 vs Short 50, net +54,835 (prev net +50,325, chg +4,510). Long Puts rose from 50,325 to 54,885 (chg +4,560, +9.06%, tagged [Long Buildup - Low Vol]), while a negligible short put position of 50 contracts was opened for the first time (prev 0). The architecture is net long calls + overwhelmingly net long puts — not a synthetic long or short, but rather a long straddle bias or a hedged long equity posture where DIIs are buying upside optionality (calls) while simultaneously purchasing downside protection (puts) at much larger scale.
- Synthesis — DII Hedged Long — Quiet Accumulation with Put-Heavy Protection: DIIs present a coherent and stable bullish-but-hedged narrative today. Their futures net long of +12,858 confirms a directional bullish bias, the short covering of 247 contracts on the futures short side indicates no new bearish futures bets, and the High Vol tag on call long buildup (+1,400 contracts, +25.28%) signals that when DIIs did take a high-conviction position today, it was on the bullish options side. The massive put long book of 54,885 contracts (versus only 50 contracts short put) shows that DIIs are not naked-long — they are insuring their equity and futures longs with puts, which is prudent risk management. Comparing to FIIs: DIIs are the institutional counterweight today — while FIIs hold a 7.10:1 short-to-long futures ratio and are net short both calls and puts, DIIs maintain a net long futures + net long options structure that leans constructive. The overall DII picture is one of controlled optimism with significant tail-risk hedging in place — they appear positioned for a range-bound or modestly bullish outcome while protecting against sharp downside.
- Forward: The key watch for DIIs tomorrow is whether their futures net long breaches +14,000 contracts — a move above that threshold, particularly if accompanied by further short covering on the futures short side (below 27,000 contracts), would indicate DIIs are scaling up their bullish conviction and could provide a meaningful demand cushion for Nifty near the 23,000 Monthly PE Support zone. If instead DII Long Put OI accelerates above 60,000 contracts while their futures long stagnates or declines, it would signal that DIIs are shifting from bullish positioning to defensive hedging, which would be a cautionary flag for the overall market despite their current constructive posture.
Pro Cautiously Neutral — Long Unwind in Futures, Massive Options Buildup Both Sides
- Futures net deteriorated from +42,255 to +38,235 (net change -4,020 contracts). On the long side, Pros unwound 4,025 contracts (prev 72,202 → today 68,177, -5.57%) tagged [Long Unwinding - Low Vol] — a meaningful directional reduction but executed without aggressive volume, suggesting measured profit-taking or risk reduction. On the short side, Pros covered a negligible 5 contracts (prev 29,947 → today 29,942, -0.02%) tagged [Short Covering - Avg Vol]. The net result is a futures position that remains net long at +38,235 but has shrunk by over -4,020 contracts in a single session — Pros are reducing bullish futures exposure. The gross long-to-short ratio is 68,177 ÷ 29,942 = 2.28:1, meaning Pros still hold more than twice as many long futures as short futures, maintaining a directional long bias even as they trim. Compared to FIIs (7.10:1 short-to-long) and DIIs (1.46:1 long-to-short), Pros sit as a moderate net long with declining conviction — a position that could flip neutral quickly if the unwinding continues.
- Pro Long PCR improved from 0.93 to 0.96 (change +3.51%) and Short PCR fell from 0.94 to 0.91 (change -2.88%). A Long PCR of 0.96 means Pros hold nearly equal put longs and call longs — essentially a balanced long options book with a very slight put tilt, neither strongly bearish nor bullish in options directionality. The rise from 0.93 to 0.96 indicates Pros added proportionally more put longs than call longs today, a marginal shift toward defensiveness consistent with their futures long unwind. The Short PCR falling from 0.94 to 0.91 means Pros wrote more calls than puts on their short options book today — a declining Short PCR implies increasing call writing relative to put writing, which is a mild ceiling/cap view. The combination of a rising Long PCR (adding more put protection) and a falling Short PCR (writing more calls) suggests Pros are transitioning toward a range-bound or mildly capped view for Nifty — they trimmed futures longs, added put protection, and wrote calls at upper levels.
- Call OI net changed from -13,701 to -11,755 (net change +1,946, a mild improvement toward neutral). Long Calls rose from 924,260 to 1,062,451 (chg +138,191, +14.95%, tagged [Long Buildup - Low Vol]) while Short Calls rose from 937,961 to 1,074,206 (chg +136,245, +14.53%, tagged [Short Buildup - Low Vol]). Put OI net dramatically improved from -19,854 to +44,633 (net change +64,487, a major swing to net long puts). Long Puts rose from 858,812 to 1,021,913 (chg +163,101, +18.99%, tagged [Long Buildup - Low Vol]) while Short Puts rose from 878,666 to 977,280 (chg +98,614, +11.22%, tagged [Short Buildup - Low Vol]). Critically, Pro put long growth (+163,101 contracts, +18.99%) massively outpaced put short growth (+98,614 contracts, +11.22%), flipping the put OI net from -19,854 to +44,633 — this is a structural shift from net put short to net put long. The resulting architecture is net short calls (-11,755) + net long puts (+44,633) = a synthetic short or collar architecture emerging today, which is a notable shift from yesterday's roughly neutral options stance.
- Synthesis — Pro Transitional Shift — From Net Long to Synthetic Short Options Architecture: Pros have made the most significant structural shift of any participant today. Yesterday they were mildly net short calls and mildly net short puts (roughly neutral); today they have flipped their put OI net from -19,854 to +44,633 — a +64,487 contract swing — while simultaneously trimming futures longs by -4,020 contracts. This combination of futures long reduction + put long buildup + net short call book is a transition from a bullish directional stance to a hedged or mildly bearish risk posture. However, all four option legs carry Low Vol tags, meaning none of these moves were executed with high volume conviction — Pros appear to be repositioning cautiously rather than aggressively fleeing their longs. Their Long PCR of 0.96 (nearly balanced) and Short PCR of 0.91 (slightly more calls written than puts) further confirm this transitional, range-biased posture. The largest single data point here is the +163,101 Long Put addition — the largest absolute put-long addition of any participant today on a percentage basis (+18.99%) — which suggests Pros are pricing in downside risk that wasn't on the table yesterday.
- Forward: The critical Pro-specific trigger to watch tomorrow is the Put OI net — if it continues to expand beyond +60,000 contracts (from today's +44,633), it would confirm a deliberate bearish pivot by the largest and most sophisticated domestic trading participant. Simultaneously, watch the futures net: if Pro futures long drops below +30,000 contracts tomorrow (from today's +38,235), combining with a growing net-long-put options book, the synthetic short architecture would be complete and directionally aligned with FII positioning, creating a dual-institutional headwind for Nifty. If instead Pro futures net recovers toward +42,000+ with declining put longs, the today's shift would be reclassified as intraday positioning noise rather than a trend reversal signal.
Client Bullish Futures / Hedged — Aggressive Long Futures, Heavy Put Buying as Tail Hedge
- Futures net improved from +233,302 to +238,948 (net change +5,646 contracts). On the long side, Clients added 5,180 contracts (prev 289,936 → today 295,116, +1.79%) tagged [Long Buildup - Avg Vol] — the only Avg Vol futures tag among all participants today, indicating this long buildup was made with moderate, measured conviction, not a fringe or hesitant move. On the short side, Clients covered 466 contracts (prev 56,634 → today 56,168, -0.82%) tagged [Short Covering - Low Vol]. The simultaneous long addition and short covering pushed the net further bullish to +238,948. The gross long-to-short ratio is 295,116 ÷ 56,168 = 5.25:1 — Clients hold more than five times as many long futures as short futures, a dominant and directionally unambiguous bullish futures posture. Clients are the single largest net-long futures participant today, standing in stark contrast to FIIs who are the largest net-short at -290,041; this FII vs Client divergence is the defining structural tension in the market today.
- Client Long PCR improved from 0.75 to 0.79 (change +5.14%) and Short PCR improved from 1.06 to 1.09 (change +3.24%). A Long PCR of 0.79 means Clients hold 79 put longs for every 100 call longs — they are predominantly call-long on the options long side, which is consistent with their bullish futures posture (they are buying calls for upside participation). However, the rise from 0.75 to 0.79 signals that Clients incrementally added more put protection today than call longs — a small but meaningful hedge addition. The Short PCR rising from 1.06 to 1.09 is a key signal: a Short PCR above 1.0 means Clients are writing more puts than calls on the short side, which is a bullish income strategy — selling puts implies a belief that the downside will be limited. A rising Short PCR reinforces this: Clients are increasingly confident in writing put premium as income, consistent with their largest-among-all-participants net futures long. The combined picture is call-heavy long options + put-writing short options = a synthetic long or bullish risk reversal architecture on the options side, fully aligned with their futures book.
- Call OI net changed from +298,330 to +290,398 (net change -7,932, a mild reduction). Long Calls rose from 3,011,455 to 3,393,646 (chg +382,191, +12.69%, tagged [Long Buildup - Low Vol]) while Short Calls rose from 2,713,125 to 3,103,248 (chg +390,123, +14.38%, tagged [Short Buildup - Low Vol]). The slightly faster short-call growth (+14.38%) vs long-call growth (+12.69%) marginally reduced the call net but left Clients still net long calls (+290,398). Put OI net deteriorated from -610,634 to -712,178 (net change -101,544 — the largest single net change of any participant in any segment today). Long Puts rose from 2,259,579 to 2,677,261 (chg +417,682, +18.48%, tagged [Long Buildup - Low Vol]) while Short Puts rose from 2,870,213 to 3,389,439 (chg +519,226, +18.09%, tagged [Short Buildup - Low Vol]). Despite massive put long additions of +417,682 contracts, the even larger put short additions of +519,226 contracts deepened the net put short to -712,178 — Clients are the dominant put sellers in the market. This is the largest gross put short position (3,389,439 contracts) of any participant in any options segment today, and its expansion confirms Clients are aggressively writing puts — a high-risk, bullish-skewed income strategy.
- Synthesis — Client Aggressive Bullish Futures + Dominant Put Writing Architecture: Clients today present the most aggressively bullish positioning of all four participants, and they are doing so at scale. Their futures net long of +238,948 (the largest of any participant) is reinforced by a Short PCR of 1.09 (writing more puts than calls, bullish income bet), a net long call book of +290,398, and a massively dominant net put short of -712,178 that deepened by -101,544 contracts in a single session. This is a synthetic long + short put strangle architecture — Clients are essentially positioned for Nifty to stay at or above current levels, collecting put premium while holding long futures and long calls for upside participation. The critical risk in this architecture is a sharp downside move: if Nifty breaks toward the 23,000 Monthly PE Support, Clients' massive put short book (3,389,439 short puts) would face severe mark-to-market losses, potentially forcing panic covering that accelerates any decline. The contrast with FIIs is stark: Clients are bullish futures + bullish options; FIIs are bearish futures + bearish options — this is the market's core structural battle today. Historically, retail clients (the dominant component of the 'Client' category) tend to be wrong at extremes, and their record futures net long combined with record put shorts at a time when FIIs and Pros are both adding defensive structures is a contra-indicator worth monitoring carefully.
- Forward: The specific trigger to watch for Clients tomorrow is their Short Put OI — if it breaches 3,500,000 contracts (from today's 3,389,439), it would signal further put-selling commitment and near-term bullish confidence. However, the immediate risk monitor is whether Nifty holds above the 23,000 Monthly PE Support: a daily close below 23,000 would put Client's massive put short book into stress and could trigger a self-reinforcing unwind (put covering = buying puts = pushing IV and Nifty lower). On the upside, if Client Long Put OI contracts (meaning they are reducing their tail hedge) while their futures net long grows above 245,000 contracts, it would confirm maximum bullish conviction and set the stage for a momentum push toward the 24,000 Monthly CE Resistance.
Bull vs Bear Strength by Participant
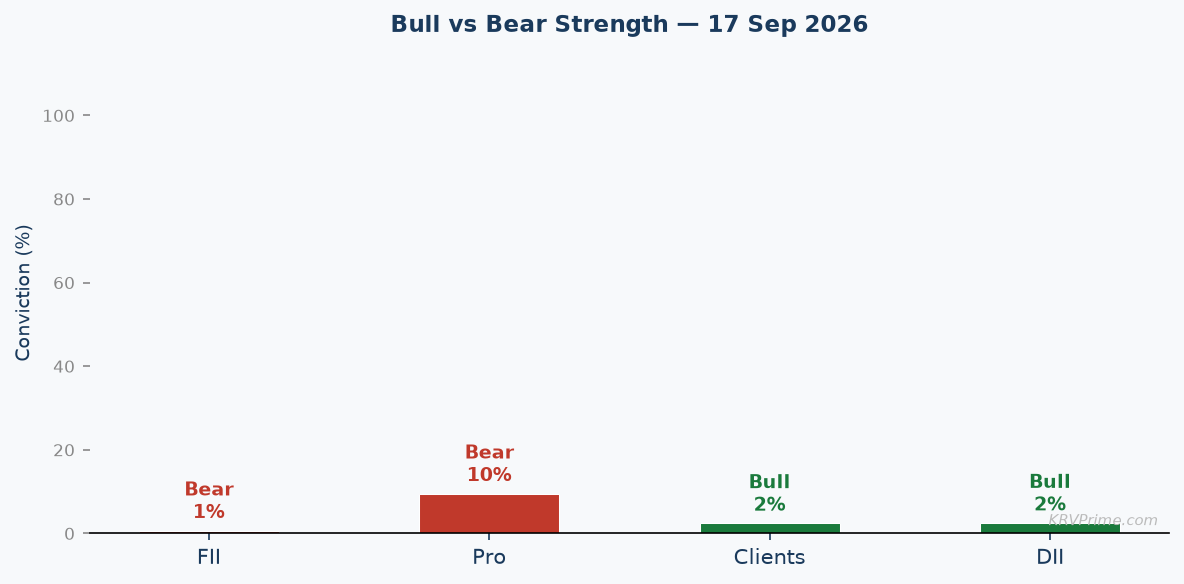
FII Cautiously Bearish 72% ▼▼ | Clients Aggressively Bullish 78% ▲▲ | Pro Transitioning Neutral/Bearish 55% ▼ | DII Mildly Bullish / Hedged 58% ▲ |
Conclusion — Market Outlook for Tomorrow (18 Sep 2026)
The market on 17 Sep 2026 closed in a state of deep structural tension. FIIs extended their net short futures to -290,041 (gross short-to-long ratio of 7.10:1) and maintain a 1.84 Long PCR with a net long put book of +612,710 — a committed bearish architecture. Simultaneously, Clients hold the largest net long futures position at +238,948 (5.25:1 long-to-short ratio) and are the market's dominant put sellers with a net put short of -712,178 contracts — an aggressively bullish architecture. Pros made a critical structural shift today, flipping their put OI net from -19,854 to +44,633 while trimming futures longs by -4,020 contracts, moving toward a synthetic short aligned with FII. DIIs remain constructively long at a net futures position of +12,858 with a high-conviction call-long addition tagged High Vol, but their massive put long book of 54,885 contracts shows they are hedged. The net reading is a market where institutional smart money (FII + Pro) is defensively positioned or bearish, while domestic participants (DII + Clients) are bullish — this divergence rarely resolves without a directional catalyst.
The Overall PCR rose from 0.95 to 0.97 (+1.99%), edging toward parity — a reading near 1.0 suggests puts and calls are accumulating at roughly equal pace, confirming market indecision rather than directional conviction. India VIX collapsed from 13.17 to 12.29 (-6.66%), entering a low-fear zone that historically supports premium compression and range-bound price action in the near term. However, a VIX at 12.29 with massive OI expansion of +5.46% in total positions is unusual — low volatility expectations combined with aggressive OI build suggests participants are writing premium (selling options) rather than buying protection, which leaves the market vulnerable to a VIX spike if a catalyst emerges. Put OI expanded +14.76% versus Call OI at +12.52%, with the PCR ticking up — the marginal tilt remains toward defensive hedging even as the VIX says fear is absent.
The bearish thesis would be confirmed if FII futures net deteriorates below -295,000 contracts, Pro futures net drops below +30,000 (deepening the synthetic short), and the Overall PCR exceeds 1.05 (puts dominating calls). The key structural support from an OI perspective is the 23,000 NIFTY Monthly PE Support — a daily close below this level would activate Client put-short stress. The bullish thesis survives if Clients' Short PCR holds above 1.05 (continued put-writing confidence), Overall PCR stays below 1.0, and VIX remains under 13.0 — in that environment, the premium-compression regime continues and Nifty grinds toward the 24,000 Monthly CE Resistance and the 24,500 Weekly CE Resistance. Tomorrow's opening session OI data is the single most important input — watch whether FIIs use any early strength to add to shorts or cover them.
Scenario 1 — Bull case:
If FII futures net improves (short-covering) from -290,041 toward -280,000 or better, and the Overall PCR declines toward 0.92-0.95 (calls accumulating faster than puts indicating bullish flow), and India VIX holds below 12.00 sustaining the low-fear premium-selling environment, then Clients' dominant put-short book would benefit and Nifty could push toward the 24,000 NIFTY Monthly CE Resistance. A Pro futures net recovery back above +42,000 would further confirm this scenario. The trigger is any FII net futures improvement above -285,000 in tomorrow's data.
Scenario 2 — Bear case:
If FII futures net deteriorates further below -295,000 contracts, Pro put OI net expands above +60,000 (confirming their synthetic short pivot), and the Overall PCR climbs above 1.05 on accelerating put buying, then the combined FII + Pro bearish architecture would overwhelm Client bullish positioning. A VIX spike back above 14.00 would be the amplifying catalyst, as it would mark-to-market losses on Client's massive put short book of 3,389,439 contracts, forcing covering that accelerates the move lower. The 23,000 NIFTY Monthly PE Support and the 54,000 BANKNIFTY Monthly PE Support become the key OI-defined downside anchors in this scenario.
Key Resistance NIFTY 24,000 (Monthly CE max OI) / 24,500 (Weekly CE max OI) — FIIs are net short calls with 928,717 short call contracts and Pros now net short calls at -11,755; both participants are writing calls at upper strikes, creating layered supply. Client short calls of 3,103,248 further reinforce this ceiling. | Key Support NIFTY 23,000 (Monthly PE max OI) / 22,000 (Weekly PE max OI) — FIIs hold 1,186,632 long put contracts and DIIs hold 54,885 long put contracts anchored near support strikes; Pros' newly built long put book of 1,021,913 adds further demand for puts at lower levels. These three participants collectively own massive put longs that would gain value on any decline toward 23,000, providing incentive to defend or monetise at this zone. | Trigger to Watch Overall PCR crossing above 1.05 (from today's 0.97) would signal put-buying acceleration overwhelming call supply — this is the quantitative threshold that would confirm institutional hedging has converted to directional bearish flow. Simultaneously, watch India VIX: a move back above 13.17 (yesterday's level) would confirm volatility re-expansion and mark-to-market pressure on the dominant Client put-short book, potentially forcing a sharp covering rally or accelerated decline depending on the direction of the VIX trigger. |