
Market Participants Analysis dated 19.08.2026
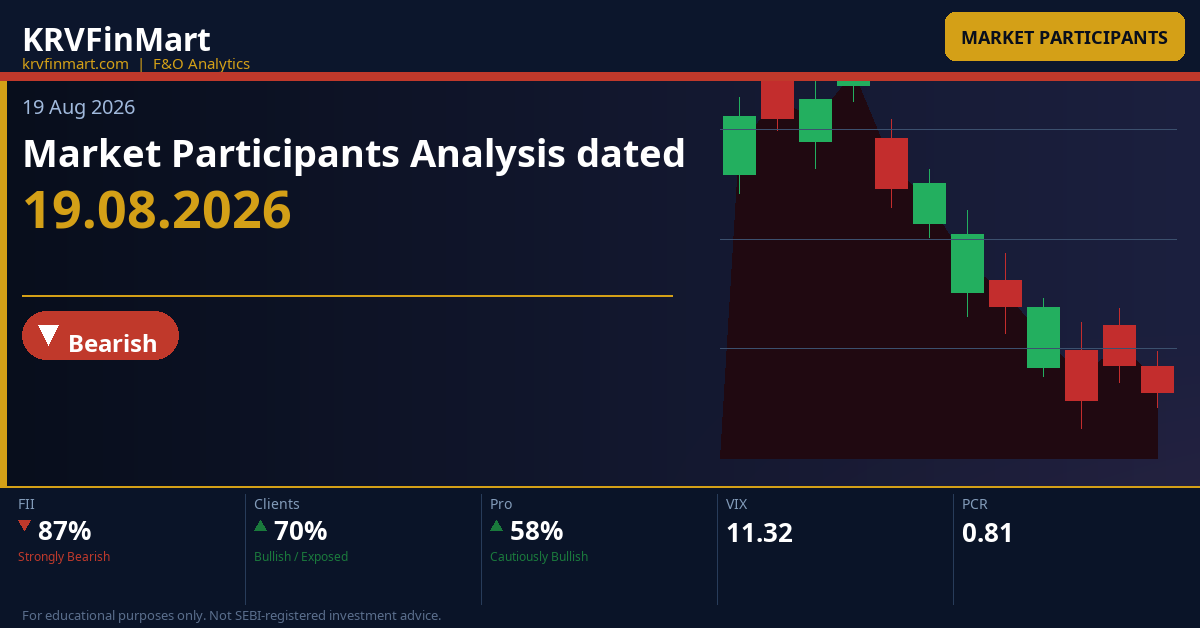
KRVFinMart — Daily Market Outlook
Key Market Signals — Data: 19 Aug 2026
NIFTY 50 24,078.30 ▼ -76.60 (-0.32%) | BANK NIFTY 57,239.75 ▼ -22.65 (-0.04%) | SENSEX 76,909.68 ▼ -325.78 (-0.42%) |
OVERALL PCR 0.81 ▼ -0.09 (-9.56%) PCR dropped sharply to 0.81 — below the neutral 1.0 threshold, signalling call-side dominance and a cautiously bearish options market tone. | INDIA VIX 11.32 ▼ -0.07 (-0.57%) VIX eased marginally to 11.32, remaining in a low-fear zone — complacency territory that historically precedes sharp directional moves. | TOTAL OI CHANGE 48,362,750 ▲ +3,275,540 (+7.26%) Large OI expansion of +7.26% on a down-close indicates fresh short build, not short-covering — a bearish OI-price divergence signal. |
FUTURES OI 696,508 ▲ +19,554 (+2.89%) Futures OI rising alongside market decline points to fresh short addition — confirming directional bearish intent in the derivatives market. | CALL OI CHANGE 9,856,116 ▲ +2,124,813 (+27.48%) Massive call OI expansion of +27.48% — the dominant driver of total OI build today, reflecting aggressive call writing and buying at resistance zones. | PUT OI CHANGE 8,021,209 ▲ +1,064,198 (+15.30%) Put OI grew +15.30% but lagged call OI growth, driving PCR sharply lower — net options sentiment leaning toward supply-side dominance. |
Participant-wise Key Points


FII Strongly Bearish — Dual-Leg Conviction Short with Structural Put Hedge
- Futures net deteriorated from -194,158 to -209,807 (net change -15,649 contracts), a significant one-session worsening. The Long side shrank from 25,502 to 24,870 contracts [Long Unwinding - High Vol], while the Short side surged from 219,660 to 234,677 contracts [Short Buildup - High Vol]. Both the High Vol tag on the long unwinding and the High Vol tag on the short buildup are critical — they confirm these are deliberate, high-conviction repositioning events, not mechanical roll or noise. The gross short-to-long ratio now stands at 9.43:1 (234,677 short vs 24,870 long), an extreme imbalance that leaves no ambiguity: FIIs are running an outright directional short position in index futures with growing conviction, and today's simultaneous long reduction and short addition on high volume means this is an aggressive, active escalation of their bearish thesis rather than a passive hold.
- Long PCR dropped from 2.09 to 1.86 (change -10.96%) and Short PCR rose from 0.49 to 0.53 (change +7.27%). A Long PCR of 1.86 still means FIIs hold 86% more put longs than call longs in absolute contract terms — this remains a deeply defensive and/or directionally bearish options posture, despite the 10.96% decline in the ratio. The decline in Long PCR is not a bullish signal; it reflects that FIIs added more call longs (98,716 new call longs) relative to put longs (79,831 new put longs) today, which may represent limited upside participation hedges rather than a structural shift. The Short PCR rising from 0.49 to 0.53 means FIIs are writing proportionally more puts versus calls on the short side — this could appear contradictory, but in context it likely represents premium income generation via put writing in the lower strikes while maintaining the core short book, a classic 'short futures + short OTM puts' structure to reduce the cost of the short carry. The dominant signal today remains bearish: rising futures short, declining but still high Long PCR, and a Short PCR still below 1.0 confirming more call writes than put writes.
- Call OI net stands at -313,586 (Long 551,764 [Long Buildup - Low Vol], Short 865,350 [Short Buildup - Low Vol]). Put OI net stands at +571,624 (Long 1,026,054 [Long Buildup - Low Vol], Short 454,430 [Short Buildup - Low Vol]). The Low Vol tags on all four options legs are notable — while the absolute changes are large in contracts (98,716 new call longs, 180,641 new call shorts, 79,831 new put longs, 119,287 new put shorts), the Low Vol tag implies this build happened on below-average implied volume or participation relative to OI norms, suggesting these were steady accumulation adds rather than panic or high-urgency positioning. The architecture is unmistakable: net short calls (-313,586) combined with net long puts (+571,624) forms a classic protective collar / synthetic short overlay — FIIs are capping potential upside (by writing calls) while actively protecting against or profiting from a downside move (via put longs). This options architecture perfectly confirms and amplifies the directional short futures position.
- Synthesis — FII Dual-Leg Bearish Architecture: FIIs present the most internally consistent and highest-conviction directional story across all participants on 19 Aug 2026. Every data point aligns: futures net deepened to -209,807 (gross short 234,677 at a 9.43:1 ratio), Long PCR remains high at 1.86 (net long put dominance), net call OI is -313,586 (writing calls to cap upside), and net put OI is +571,624 (long puts for downside protection or profit). This is a textbook triple-leg bearish architecture — short futures + short calls + long puts — which is the most expensive and therefore the highest-conviction bearish structure available in F&O. FIIs did not merely hold their existing short; they actively escalated it on High Vol confirmation in futures while expanding the options overlay on a down-close day, suggesting they view today's mild -0.32% Nifty decline as only the beginning of a larger move lower. Compared to the previous session (futures net was -194,158), today's net of -209,807 represents a -8.06% worsening in a single session — this is acceleration, not consolidation. The only mild internal complexity is the rising Short PCR (more put writes on the short side), which reduces the net bearishness of the short-options book slightly, but this is overwhelmed by the massive net long put position of +571,624.
- Forward: The critical FII trigger to watch is whether their futures net crosses -220,000 in tomorrow's data — a further deterioration beyond that level would signal the third consecutive session of short escalation and would be the strongest possible confirmation of a structural bearish breakdown thesis. If instead the futures net improves back toward -200,000 (i.e. short-covering of roughly 10,000 contracts), it would be the first sign FIIs are questioning the thesis, and combined with a PCR recovery above 0.90, could generate a sharp relief rally. Watch the 24,000 OI support level (Nifty weekly and monthly PE max OI) — a sustained breach of this level on expanding FII futures short OI would be the confirmation trigger for the bear case.
DII Mildly Bearish — Reducing Long Exposure Across Futures and Puts
- Futures net declined from +31,073 to +27,569 (net change -3,504 contracts), marking a meaningful reduction in DII's net long futures position. The Long side fell from 50,874 to 47,420 contracts [Long Unwinding - Avg Vol], while the Short side barely moved, rising from 19,801 to 19,851 contracts [Short Buildup - High Vol]. The contrast in volume tags is telling: the long reduction came on Avg Vol (routine, not panic-driven), while the trivial short addition of just 50 contracts carried a High Vol tag — suggesting that the short side was deliberately monitored and held with conviction even at a minimal level, while the long side was routinely trimmed. The gross long-to-short ratio is now 2.39:1 (47,420 long vs 19,851 short), down from the previous session's 2.57:1 — DIIs remain net long futures but are quietly reducing that long exposure, which in the context of FII aggressive shorting is a meaningful alignment signal: even the typically bullish DII camp is stepping back.
- DII does not have separate Long PCR and Short PCR data available for index options in this dataset, as their options positions are near-negligible in scale compared to FII, Pro, and Clients. The Call OI position is completely flat at Long 7,340 / Short 70 with zero change [Long Flat - Low Vol on both], and the Put OI Long fell from 47,308 to 44,204 [Long Unwinding - High Vol] while Short held at 100 [Short Flat - High Vol]. The High Vol tag on the put long unwinding is significant — DIIs reduced their put protection book by -3,104 contracts on high volume, implying this was a deliberate decision to reduce downside hedging rather than a passive roll-off. This is a nuanced signal: if DIIs believe a major downside move is imminent, they would be adding puts, not removing them — the put reduction may suggest they expect range-bound or limited downside rather than a sharp fall, even as they trim futures longs.
- Call OI net stands at +7,270 (Long 7,340 [Long Flat - Low Vol], Short 70 [Short Flat - Low Vol]). Put OI net stands at +44,104 (Long 44,204 [Long Unwinding - High Vol], Short 100 [Short Flat - High Vol]). The call position is entirely static — zero change on both legs, with Low Vol confirmation, meaning DIIs have made no new options decisions on the call side today whatsoever. The put side tells the more interesting story: net put longs of +44,104 still represent a meaningful protective book, but the active reduction of -3,104 put longs on High Vol signals intentional de-risking. The overall options architecture for DII is net long puts with flat calls — a simple downside hedge rather than a complex strategy, and today's action was to partially unwind that hedge, which when combined with futures long reduction creates a clear picture of risk-off positioning rather than active bearish speculation.
- Synthesis — DII Cautious Retreat from Long Positioning: DIIs are not making a bold directional call today — they are quietly and systematically reducing risk on both the futures side (-3,504 net futures change) and the put options side (-3,104 put long reduction). The futures net of +27,569 is still bullish in absolute terms (net long), but the trend of reduction across two consecutive data points is noteworthy when viewed against FII's aggressive short escalation. DIIs are effectively 'lightening up' — they are not shorting the market, they are not adding new longs, and they are partially removing their put protection — a posture consistent with an institution that expects a low-volatility grind with limited near-term conviction in either direction, rather than a participant positioning for a sharp directional move. Compared to FII (who are running a 9.43:1 short-to-long ratio in futures), the DII 2.39:1 long-to-short ratio represents the clearest inter-participant divergence on the long/short futures dimension — DIIs are still on the opposite side of the FII trade, just with diminishing conviction. The High Vol tag on DII's put long unwinding is the most actionable signal: it means smart institutional money is not paying up for downside protection at these levels.
- Forward: The DII watch metric for tomorrow is whether futures net falls below +25,000 — a further reduction from today's +27,569 would signal the third phase of DII long reduction and would begin to align DII directionally with FII bearishness, which historically precedes accelerated downside. If instead DII rebuilds futures longs above +30,000 tomorrow (reversing today's unwind), that would be the first contrarian bullish signal from a typically counter-FII participant. Monitor the put OI long level — if DII puts recover above 47,308 (the previous session level), it would signal renewed concern about downside that the market currently appears to be discounting.
Pro Cautiously Bullish — Covering Shorts, Building Longs, Net Options Turning Positive
- Futures net improved dramatically from -10,711 to -3,170 (net change +7,541 contracts), the largest single-session futures net improvement of any participant today. The Long side rose from 35,523 to 38,025 contracts [Long Buildup - High Vol], while the Short side fell from 46,234 to 41,195 contracts [Short Covering - Avg Vol]. The High Vol tag on the long buildup confirms this was a deliberate, high-conviction addition of new long positions, while the Avg Vol tag on short covering indicates the short reduction was routine rather than panic-driven. The gross ratio has improved materially — the short-to-long ratio is now 1.08:1 (41,195 short vs 38,025 long), barely above parity and down from the previous session's 1.30:1 — Pros are on the verge of flipping their futures book net long, and today's high-conviction long buildup suggests they see value on the long side or are fading the FII short position as overdone.
- Long PCR dropped from 0.94 to 0.81 (change -13.99%) and Short PCR dropped from 0.81 to 0.74 (change -8.97%). A Long PCR of 0.81 means Pros hold 19% more call longs than put longs in absolute terms — they are leaning calls on the long side, a mild bullish lean compared to the deep put-heavy posture of FIIs. The decline in Long PCR (from 0.94 to 0.81) signals that Pros added proportionally more call longs (281,627 new call longs vs 128,922 new put longs) today — this is a meaningfully bullish tilt in their options long book. The Short PCR declining from 0.81 to 0.74 means Pros are now writing proportionally more calls than puts on the short side — this can be interpreted as a call spread strategy or range-capping behavior, though in the context of the rising futures long it is more likely that the call writes are covered calls against new long positions rather than naked bearish bets. The combination of rising call longs and declining Long PCR reinforces that Pros are making a cautiously bullish directional play today.
- Call OI net turned positive to +33,355 (Long 1,036,616 [Long Buildup - Low Vol], Short 1,003,261 [Short Buildup - Low Vol]). Put OI net stands at +97,090 (Long 841,394 [Long Buildup - Low Vol], Short 744,304 [Short Buildup - Low Vol]). Both legs on both sides carry Low Vol tags — the large absolute additions (281,627 call longs, 177,026 call shorts, 128,922 put longs, 70,945 put shorts) occurred on below-average volume conviction, meaning these are steady accumulation trades rather than high-urgency conviction bets. The critical shift is the call OI net flipping from -71,246 to +33,355 — Pros went from net short calls (bearish/capping) to net long calls (bullish/directional) in a single session, a +104,601 swing that is the largest single-session options net shift across all participants today. Combined with the net long puts (+97,090), Pros are now running net long calls AND net long puts — a long strangle or long straddle architecture that profits from a large directional move in either direction, though the futures long bias tilts this toward a bullish breakout bet.
- Synthesis — Pro Bullish Repositioning with Volatility Play Overlay: Pros are executing the most dynamic and arguably the most strategically interesting repositioning of the session. In futures, they improved their net by +7,541 contracts from -10,711 to -3,170, on the back of High Vol long buildup — this is the clearest bullish directional signal in the futures market today from any non-retail participant. In options, the call OI net swung by +104,601 from -71,246 to +33,355 (now net long calls), while put OI net expanded to +97,090 (net long puts). This creates a long strangle architecture overlaid on a near-neutral futures book — a strategy that profits maximally if Nifty makes a large move from current levels of 24,078.30, either sharply higher or sharply lower. The low VIX environment at 11.32 makes buying strangles relatively cheap, which explains why Pros may be using this structure now. Critically, Pros are positioned in direct opposition to FIIs in the futures market (Pros buying/covering while FIIs are aggressively shorting), making this the most important inter-participant divergence to monitor — one of these two sophisticated participant groups will be wrong, and the resolution will likely define the next 3-5 day directional move. Today's acceleration of the Pro long buildup (compared to previous session's -10,711 net) confirms this is not a hesitant hedge but an active thesis.
- Forward: The defining Pro trigger for tomorrow is whether their futures net crosses into positive territory (above 0) — given today's -3,170 net and the momentum of the +7,541 improvement, a flip to net long futures by Pros would be a landmark bullish signal that historically precedes sharp upside moves in the near term. If instead Pros reverse and their futures net deteriorates back toward -8,000 or worse, it would signal capitulation of the Pro long thesis and remove the most important bullish counterweight to FII bearishness. Watch the 24,500 CE resistance level (Nifty weekly/monthly CE max OI) — if Pros begin reducing their net long call position there, it would suggest they are using that as a strangle anchor rather than a directional breakout target.
Client Bullish on Futures, Hedged via Puts — Retail Net Long with Growing Short-Side Caution
- Futures net improved from +173,796 to +185,408 (net change +11,612 contracts), the largest absolute futures net improvement today by any participant and a strong continuation of Client bullish futures positioning. The Long side rose from 226,578 to 237,939 contracts [Long Buildup - High Vol], while the Short side marginally eased from 52,782 to 52,531 contracts [Short Covering - Avg Vol]. The High Vol tag on the long buildup is decisive — retail/Client participants are not passively holding; they are actively and with high conviction adding to long futures positions even on a day when Nifty fell -0.32% and FIIs aggressively shorted. The gross long-to-short ratio stands at 4.53:1 (237,939 long vs 52,531 short), up from the previous session's 4.29:1 — Clients are the most aggressively net long participant in the futures market by a wide margin, and today's data shows they are doubling down rather than retreating. This is textbook retail 'buy the dip' behavior in the futures segment, and it places Clients in direct confrontation with FII shorts.
- Long PCR dropped from 0.67 to 0.63 (change -5.82%) and Short PCR dropped from 1.05 to 0.92 (change -12.38%). A Long PCR of 0.63 means Clients hold 37% more call longs than put longs — they are leaning strongly toward calls on the long side, a bullish directional bet through options. The decline from 0.67 to 0.63 confirms that today's call long addition (682,063 new call longs) dwarfed the put long addition (326,449 new put longs), deepening the call-heavy tilt. The Short PCR declining from 1.05 to 0.92 is the more nuanced signal — the previous Short PCR above 1.0 meant Clients were writing more puts than calls on the short side (a bullish-of-short-side behavior), but today's decline to 0.92 means they have shifted to writing slightly more calls than puts on the short side (704,740 new call shorts vs 341,868 new put shorts) — this could reflect increased call writing as a premium income trade against their long futures book (covered calls), or it may signal the first tentative hedging of the call-heavy portfolio by writing upside calls. Either way, the Long PCR of 0.63 and the futures net of +185,408 confirm Clients remain the most unambiguously bullish participant in the market today.
- Call OI net stands at +272,961 (Long 3,332,338 [Long Buildup - Low Vol], Short 3,059,377 [Short Buildup - Low Vol]). Put OI net stands at -712,819 (Long 2,098,952 [Long Buildup - Low Vol], Short 2,811,771 [Short Buildup - Low Vol]). Clients are the single largest participant by gross options OI across all legs — their call long book of 3,332,338 and put short book of 2,811,771 are the dominant positions in the market and the primary driver of the overall market PCR declining to 0.81. The net call long of +272,961 combined with the net put short of -712,819 creates a synthetic long / bull spread architecture — maximum profit if the market rises, maximum pain if the market falls sharply (due to the massive short put exposure). The Low Vol tags on all four options legs suggest this is a gradual, distributed accumulation rather than a single high-urgency block trade, consistent with a large retail base entering in tranches rather than institutions making decisive single-session moves.
- Synthesis — Client Aggressive Synthetic Long with Covered Call Overlay: Clients are running the most aggressively bullish net positioning across all participants, but their architecture contains a structural vulnerability. The combination of futures net +185,408, net long calls +272,961, and net short puts -712,819 creates a triple-bullish overlay — all three legs profit if Nifty rises and all three suffer simultaneously if Nifty falls sharply. The net short put position of -712,819 is the most dangerous element: at current market levels near 24,078, a sustained breakdown below the 24,000 PE support level would trigger accelerating losses on the short put book, potentially forcing aggressive unwinding that compounds the downside move. Compared to FII (bearish across all legs) and Pro (long strangle — hedged either way), Clients are the most exposed to a unidirectional bearish event. The divergence between Clients (futures net +185,408, bullish) and FIIs (futures net -209,807, bearish) is the defining tension of today's market structure — a classic 'retail vs institution' standoff that historically resolves in favor of the institutional (FII) side, though the Pro repositioning toward longs introduces meaningful uncertainty. Today's session saw Clients add 11,612 net futures longs on High Vol even as the market fell — this buy-the-dip conviction is the core bullish argument, but the simultaneous massive short put book means the downside tail risk is asymmetric.
- Forward: The critical Client trigger to monitor is the 24,000 PE support level — if Nifty closes below 24,000 tomorrow on expanding OI, the Client net short put book of -712,819 will face mark-to-market pressure that could force rapid put short covering, which in turn would cause implied volatility to spike from the current 11.32 VIX level and potentially accelerate the downside move. Conversely, if Nifty holds above 24,000 and the overall PCR recovers above 0.90 (from today's 0.81), it would validate the Client long thesis and could trigger upside momentum as short-sellers (particularly FIIs) begin to cover. Watch tomorrow's Client futures net — if it expands beyond 190,000, it signals sustained retail conviction that could eventually force a short squeeze on FII positions.
Bull vs Bear Strength by Participant

FII Strongly Bearish 87% ▼▼ | Clients Bullish / Exposed 70% ▲▲ | Pro Cautiously Bullish 58% ▲ | DII Mildly Bearish 55% ▼ |
Conclusion — Market Outlook for Tomorrow (19 Aug 2026)

The collective F&O positioning on 19 Aug 2026 presents a structurally bearish picture driven by FII conviction, partially offset by a notable Pro repositioning toward longs. FIIs deepened their futures short book to a net of -209,807 contracts (9.43:1 gross short-to-long ratio) on High Vol confirmation across both legs — this is the most powerful directional signal in today's data. DIIs, traditionally a counter-FII bullish anchor, further trimmed their futures net long from +31,073 to +27,569 and reduced their put protection book by -3,104 contracts on High Vol — a subtle but meaningful reduction of their bullish conviction. Clients remain aggressively net long at +185,408 futures (adding +11,612 on High Vol), but their -712,819 net short put position creates a structural vulnerability at the 24,000 support zone that could amplify any downside move. Pros are the most interesting swing factor: they improved their futures net by +7,541 to -3,170 and flipped from net short calls to net long calls (+33,355), suggesting sophisticated participants are beginning to fade the FII bearish thesis — but with Low Vol options confirmation, their conviction is not yet at full force.
The overall PCR's sharp decline from 0.90 to 0.81 (-9.56%) — driven by Call OI expanding +27.48% versus Put OI growing only +15.30% — is an unambiguous bearish options sentiment signal. A PCR of 0.81 sits well below the neutral 1.0 threshold, indicating the market is pricing in more call supply (resistance building) than put demand (protective buying) at current levels. India VIX at 11.32 (down -0.57% from 11.39) remains in a historically low-fear zone — while directionally VIX is calm, a complacency-level VIX is a classic setup for a volatility expansion event, particularly when FII shorts are at elevated gross levels of 234,677 contracts. Total OI expanded by +7.26% to 48,362,750 on a declining market — a textbook bearish OI-price confirmation that new shorts are being built, not old longs being covered. The convergence of falling PCR, low but complacent VIX, and OI expansion on a down day collectively supports a bearish bias for the near term.
The bull case requires two simultaneous developments: FII futures net must improve toward -195,000 or better (short-covering of at least 15,000 contracts), AND the overall PCR must recover above 0.90. If Pros complete their flip to net long futures (currently at -3,170) and VIX stays anchored below 12.00, the Client long book could prove prescient and a sharp short-covering rally targeting the 24,500 CE resistance is possible. The bear case is validated if FII net worsens beyond -220,000, the PCR continues declining below 0.75, and Nifty breaches the critical 24,000 PE support level — in that scenario, Client short puts at 24,000 and below face forced covering, VIX would spike, and the cascade dynamic favors a swift move toward the next structural support.
Scenario 1 — Bull case:
If FII futures net improves from -209,807 toward -195,000 (net short-covering of ~15,000 contracts) in tomorrow's data, and the overall PCR recovers above 0.90 from today's 0.81, it would signal that FII bearish conviction is waning. A simultaneous flip of Pro futures net into positive territory (from today's -3,170) would confirm a coordinated institutional swing toward bullish positioning. Under this scenario, Client long futures (net +185,408) and Pro long calls would fuel a momentum move targeting the 24,500 CE OI resistance level, with VIX likely compressing further below 11.00 confirming the low-fear upside environment.
Scenario 2 — Bear case:
If FII futures net worsens beyond -220,000 (an additional ~10,000 short addition from today's 234,677 gross short), and the overall PCR slides further below 0.75, the structural short dominance will become overwhelming. A sustained breach of the 24,000 PE OI support level on expanding total OI would trigger forced covering of Client's -712,819 net short put book, causing a VIX spike above 13.00-14.00 from the current complacency level of 11.32. DII reducing futures longs below +25,000 would remove the last meaningful institutional bullish counterweight, and the downside cascade would target the next significant put concentration zone below 24,000.
Key Resistance Nifty 24,500 (weekly and monthly CE max OI) — FIIs are writing calls here (part of their -313,586 net short call book) while Clients hold the largest gross call long exposure at 3,332,338 contracts. This dual-sided activity at 24,500 creates the market's primary supply ceiling; a sustained close above 24,500 on declining call OI would signal a genuine breakout. | Key Support Nifty 24,000 (weekly and monthly PE max OI) — FIIs hold 1,026,054 put longs concentrated around this zone (+79,831 added today), and Clients hold a massive -712,819 net short put position that becomes deeply stressed below this level. BankNifty 57,000 (monthly PE max OI) provides parallel support with DII and FII put positioning anchored there. | Trigger to Watch Overall PCR crossing back above 0.90 (from today's 0.81) in tomorrow's data would be the primary bullish trigger — it would indicate put buying is recovering relative to call selling, reversing today's bearish options flow. Failure to recover PCR above 0.90, combined with FII futures net worsening beyond -215,000, would confirm the bear case and make 24,000 the immediate battleground. |