
Market Participants Analysis dated 21.09.2026
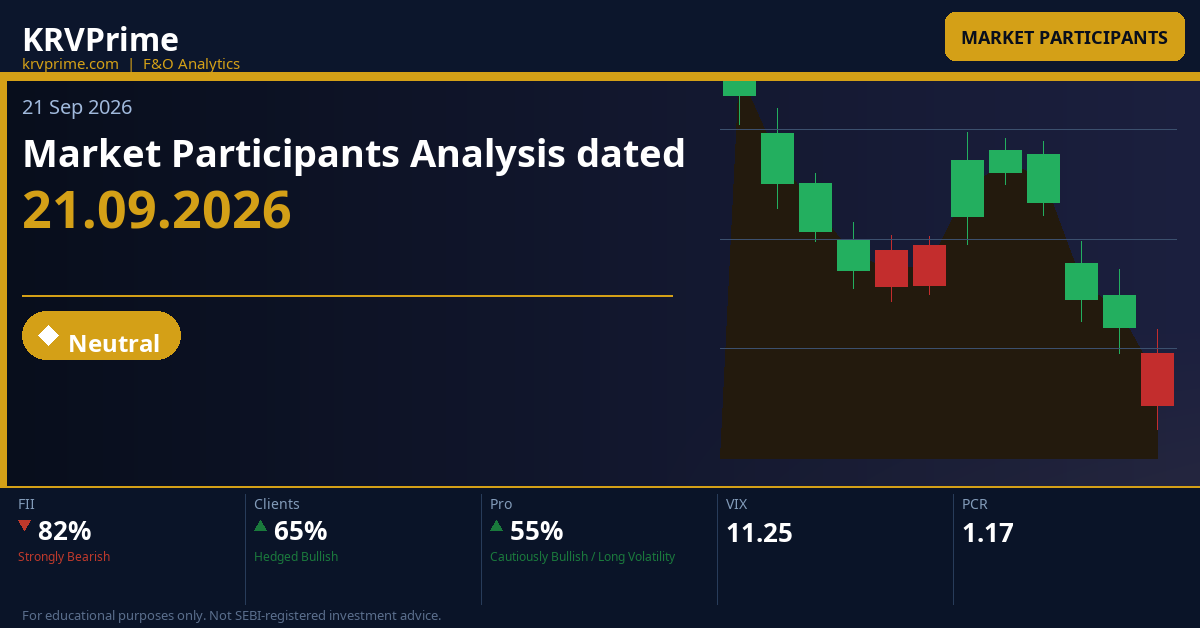
KRVPrime — Daily Market Outlook
Key Market Signals — Data: 21 Sep 2026
NIFTY 50 23,414.30 ▲ +67.90 (+0.29%) | BANK NIFTY 56,470.65 ▲ +111.95 (+0.20%) | SENSEX 74,858.99 ▲ +564.03 (+0.76%) |
OVERALL PCR 1.17 ▲ +0.13 (+11.94%) PCR 1.17 (prev 1.04) — sharp jump signals put OI expansion dominating; moderately bullish accumulation of put support. | INDIA VIX 11.25 ▼ -0.13 (-1.21%) VIX at 11.25 and falling — ultra-low fear zone; premium sellers comfortable, tail-risk hedging light. | TOTAL OI CHANGE 55,554,690 ▲ +2,871,584 (+5.45%) Significant total OI build of +2.87M contracts; new money entering the market, not short covering. |
FUTURES OI 899,696 ▼ -3,762 (-0.42%) Futures OI marginally lower by -3,762 contracts — slight position squaring in futures; options driving today's OI build. | CALL OI CHANGE 11,383,756 ▲ +552,951 (+5.11%) Call OI expanded +5.11% — fresh call writing and buying at resistance; upside capped by supply build at 23500 CE. | PUT OI CHANGE 13,278,274 ▲ +1,992,505 (+17.66%) Put OI surged +17.66% — dominant theme of the session; support accumulation and downside hedging activity across all participants. |
Participant-wise Key Points
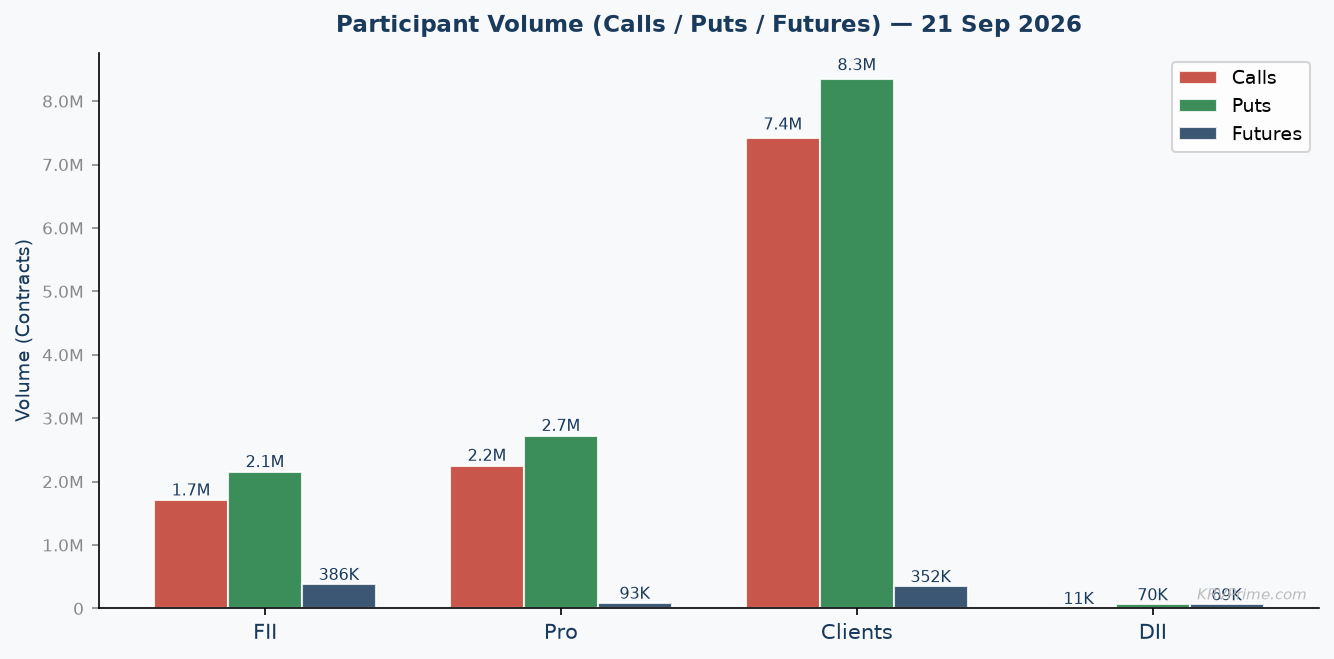
FII Cautiously Bearish — Futures Short Buildup with Defensive Options Expansion
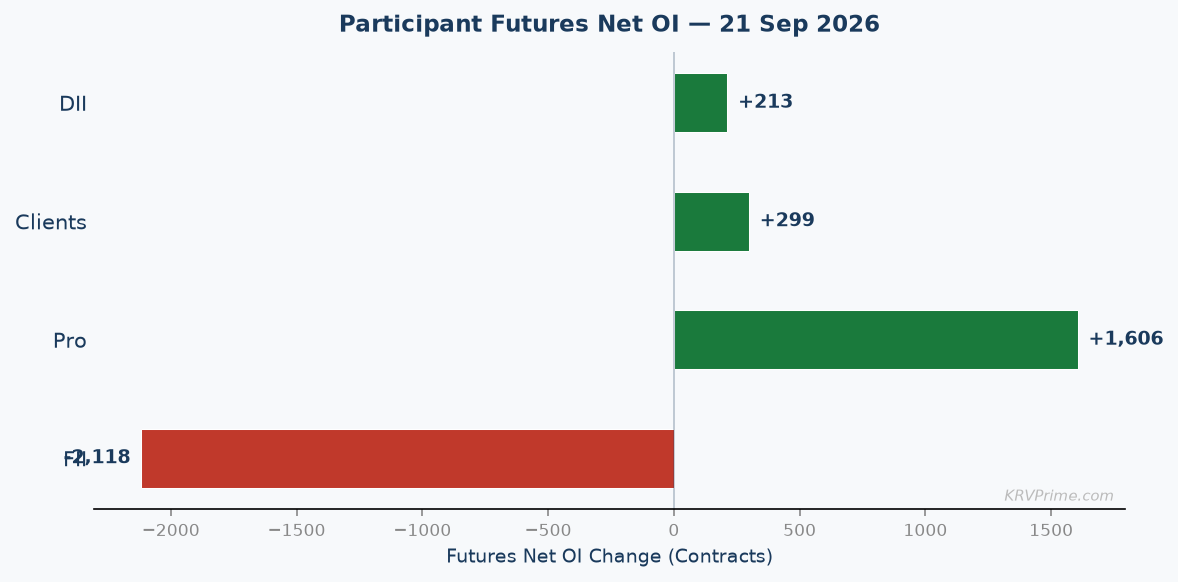
- Futures net deteriorated from -288,428 to -290,546 (net change -2,118 contracts). The Long side fell from 48,406 to 47,731 contracts [Long Unwinding - Avg Vol], reflecting routine but deliberate reduction of long exposure, while the Short side rose from 336,834 to 338,277 contracts [Short Buildup - Avg Vol]. The gross short-to-long ratio now stands at a formidable 7.09:1 (338,277 shorts vs 47,731 longs) — this is not a hedging ratio; at 7:1, this is an outright directional short position of high conviction. The Avg Vol tag on both legs confirms this was routine position management rather than a panic-driven or forced event, meaning FIIs are deliberately and methodically deepening their net short in futures even as Nifty closed +0.29% higher — a refusal to capitulate that speaks to sustained macro-level bearish conviction.
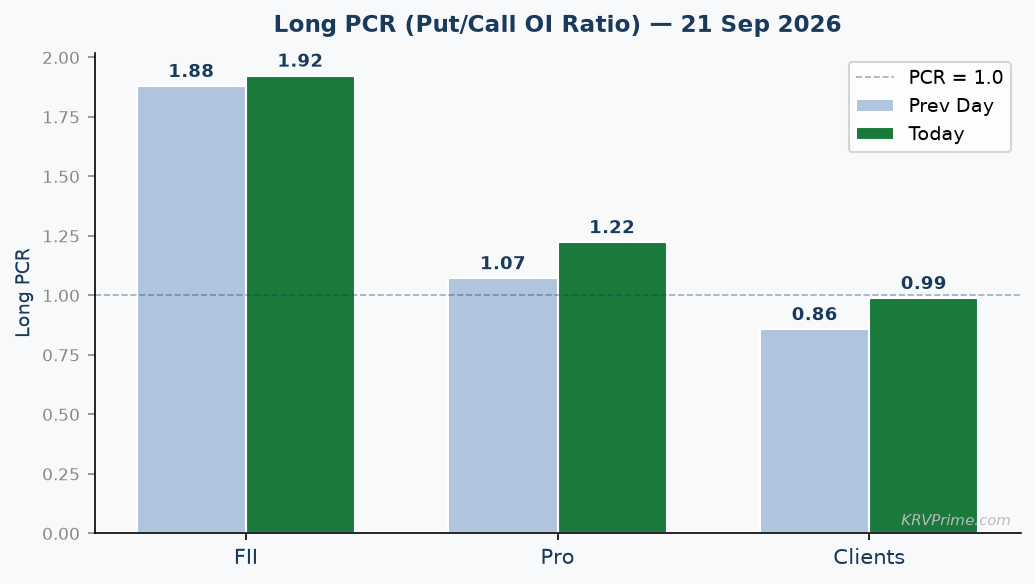
- FII Long PCR rose from 1.88 to 1.92 (+2.31%) and Short PCR rose from 0.70 to 0.77 (+10.47%). A Long PCR of 1.92 means FIIs hold nearly 92% more put longs than call longs in their options book — this is a deeply defensive, near-structural hedge posture indicating either protection of a large equity long book or a direct bearish directional bet through options. The sharp jump in Short PCR from 0.70 to 0.77 (+10.47%) is equally significant: FIIs are now writing proportionally more puts than calls on the short side, which at face value appears bullish (receiving premium on downside strikes), but when viewed alongside the Long PCR of 1.92, it suggests they are financing their expensive put-long hedge by selling closer puts — a classic put spread or ratio spread architecture. The dominant signal today is the Long PCR expansion to 1.92, which directly reinforces the futures short book: FIIs are not just short futures, they are also long downside through options.
- Call OI net improved from -268,402 to -256,356 (net change +12,046 contracts). Long calls rose from 690,977 to 724,548 [Long Buildup - Low Vol] and short calls rose from 959,379 to 980,904 [Short Buildup - Low Vol]. Put OI net expanded from +630,453 to +638,430 (net change +7,977 contracts): put longs surged from 1,299,085 to 1,393,670 [Long Buildup - Low Vol] and put shorts rose from 668,632 to 755,240 [Short Buildup - Low Vol]. The Low Vol tags on all four legs indicate these are measured, not urgent, additions — FIIs are building their options book methodically. The architecture — net short calls (-256,356) combined with net long puts (+638,430) — is a classic synthetic short / protective collar: call writing caps any rally reward while put longs provide direct downside payoff. This options architecture is 100% consistent with and complementary to the futures short book.
- Synthesis — FII Dual-Leg Bearish Conviction Architecture: FIIs present the most internally consistent and multi-layered bearish positioning of all participants today. Their futures net of -290,546 with a 7.09:1 short-to-long ratio, a Long PCR of 1.92 (nearly 2x more put longs than call longs), net short calls at -256,356, and net long puts at +638,430 collectively describe a deliberate, multi-instrument short strategy that spans futures and both legs of the options market. The combined architecture — futures short + short calls + long puts — is a triple-leg synthetic short that maximises downside participation while collecting call premium to partially offset the cost of put longs. Critically, FIIs added to this position on a day when Nifty rose +0.29% and the overall PCR jumped to 1.17 (a moderately bullish reading) — their refusal to cover on positive price action and a rising PCR tells us their thesis is driven by structural macro conviction, not short-term price movement. The Low Vol tags across options legs suggest this is patient, strategic accumulation rather than reactive hedging, which is the most dangerous form of institutional short — it does not get shaken out by minor rallies.
- Forward: Watch whether FII futures net breaks below -295,000 contracts in tomorrow's session — if the gross short side expands beyond 340,000 with the long side continuing to erode, it would confirm an accelerating bearish conviction cycle and materially increase downside pressure on Nifty near the 23,400 PE support level. Conversely, if FII futures net improves toward -285,000 or better (i.e., short covering of 5,000+ contracts) alongside a drop in their Long PCR below 1.85, the bearish thesis would be challenged and a short-covering-driven rally toward 23,500 CE resistance becomes viable. The critical confirmation signal for tomorrow is whether FII put longs (currently 1,393,670) continue to expand — any further acceleration above 1,420,000 confirms they are positioning for an imminent downside move.
DII Defensively Bullish — Aggressive Put Long Build with Stable Futures Long
- Futures net improved from +12,967 to +13,180 (net change +213 contracts). The Long side added modestly from 40,741 to 40,954 contracts [Long Buildup - Low Vol], while the Short side held completely flat at 27,774 contracts [Short Flat - Low Vol] — unchanged by a single contract. The gross long-to-short ratio stands at 1.48:1 (40,954 longs vs 27,774 shorts), a moderately bullish directional tilt in futures. The Low Vol tags on both legs indicate this is a routine, passive maintenance of existing positions rather than an aggressive directional push — DIIs are holding their futures long book steady, neither adding conviction nor reducing exposure, which in itself is a signal of quiet confidence in the current market level.
- DII options PCR data is not separately reported in the provided dataset, so a direct Long PCR / Short PCR computation is not available for this participant. However, directional inference can be drawn from the raw options OI changes: DII call OI long additions of +698 contracts and put OI long additions of +12,075 contracts imply a heavily put-skewed options long book, with an implied put-to-call long ratio of approximately 17.4:1 — a reading of extraordinary defensive skew. This indicates DIIs are aggressively accumulating downside protection relative to their call exposure, despite holding a net long futures position, which is consistent with an institution that is bullish on underlying holdings but deeply concerned about near-term downside risk, potentially driven by regulatory or macro event awareness.
- Call OI net expanded from +5,619 to +6,117 (net change +498 contracts). Long calls rose from 8,009 to 8,707 [Long Buildup - Low Vol] and short calls rose from 2,390 to 2,590 [Short Buildup - Avg Vol]. Put OI net surged from +57,285 to +69,560 (net change +12,275 contracts): put longs jumped from 57,485 to 69,560 [Long Buildup - High Vol] while put shorts were completely eliminated from 200 to 0 [Short Covering - Low Vol]. The High Vol tag on put long buildup is the standout signal of the DII block — it indicates a high-conviction, deliberate surge in put long positions, the largest percentage OI change (+21.01%) of any single DII leg. The elimination of all put shorts (short covering to zero) combined with the high-conviction put long build creates a pure net long put position of 69,560 contracts — an unambiguous downside protection posture.
- Synthesis — DII Asymmetric Hedge Acceleration: DIIs present a fascinating and internally coherent split-personality positioning today: net long futures (+13,180, a bullish futures stance) combined with a massive and accelerating put long book (+69,560 net, High Vol confirmed). This is a classic long equity / long put protective structure — DIIs appear to be protecting a substantial underlying equity portfolio through aggressively adding put options while maintaining their directional futures long. The High Vol confirmation on put longs is critical: it tells us this is not routine hedging but a deliberate, high-urgency increase in downside protection, suggesting DIIs may have advance awareness of an event risk (index rebalancing, macro data, or earnings cluster) that warrants rapid hedge escalation. The complete elimination of put shorts (from 200 to 0) reinforces this — DIIs are not willing to be naked short any puts right now, preferring clean long protection. Compared to FIIs who are synthetically short, DIIs are long-with-hedge — a fundamentally different and less outright bearish stance, even though both are building put books today.
- Forward: The key trigger to watch for DII tomorrow is whether their put long book (currently 69,560 contracts) continues to expand above 80,000 — if it does with another High Vol confirmation tag, it would signal that the downside hedge acceleration is becoming structural rather than event-driven, and would be a strong warning sign for the 23,400 PE support level. If instead DII put longs plateau or begin to unwind below 65,000, it would suggest the hedge was event-specific and has been fulfilled, removing a significant source of put OI pressure and potentially allowing Nifty to rally toward 23,500. Watch DII futures net simultaneously — any reduction below +12,000 (futures long reduction) combined with put long expansion would be the most bearish DII signal possible.
Pro Cautiously Bullish — Short Covering in Futures, Aggressive Put Long Buildup
- Futures net improved from +34,041 to +35,647 (net change +1,606 contracts). The Long side eased slightly from 64,601 to 64,099 [Long Unwinding - Low Vol] while the Short side fell sharply from 30,560 to 28,452 [Short Covering - Low Vol]. The net improvement was entirely driven by short covering of -2,108 contracts on the short side, not by new long additions — the gross long-to-short ratio now stands at 2.25:1 (64,099 longs vs 28,452 shorts). The Low Vol tag on both legs indicates this short covering was measured rather than panic-driven, suggesting Pros are deliberately reducing their futures short book as a risk management step, possibly in response to the rising PCR and stable Nifty close — a quiet but meaningful shift toward a less hedged, more directionally bullish futures stance.
- Pro Long PCR rose from 1.07 to 1.22 (+14.14%) and Short PCR rose from 1.00 to 1.19 (+18.87%). A Long PCR jump from 1.07 to 1.22 means Pros have moved from a near-balanced options book to holding 22% more put longs than call longs — a meaningful shift toward downside protection in a single session. The Short PCR surge from 1.00 to 1.19 (+18.87%) is equally significant: Pros are now writing 19% more puts than calls on their short side, meaning they are actively selling puts — a bullish-leaning income strategy that profits when the market holds at or above current levels. The combination of rising Long PCR (buying puts for protection) and rising Short PCR (selling puts for income) suggests Pros are executing a put ratio strategy: long puts at a lower strike and short puts at a higher strike, collecting net premium while retaining partial downside exposure. The dominant signal is the 18.87% Short PCR surge, confirming Pros believe the downside at 23,400 is unlikely to be breached near-term.
- Call OI net expanded from +29,767 to +67,612 (net change +37,845 contracts). Long calls surged from 1,111,636 to 1,157,470 [Long Buildup - Avg Vol] and short calls added from 1,081,869 to 1,089,858 [Short Buildup - Avg Vol]. Put OI net expanded from +108,858 to +119,751 (net change +10,893 contracts): put longs surged from 1,192,066 to 1,416,784 [Long Buildup - Avg Vol] and put shorts also surged from 1,083,208 to 1,297,033 [Short Buildup - Avg Vol]. The massive put activity — +224,718 put longs and +213,825 put shorts in a single session — describes a put strangle or put spread book being actively constructed. The near-symmetrical size of put long and put short additions (224,718 vs 213,825) combined with Avg Vol tags on all four legs confirms this is deliberate, planned options strategy construction by Pros, not reactive hedging. The net long calls (+67,612) combined with net long puts (+119,751) suggests a long straddle / long volatility stance in options even as VIX is low — Pros may be positioning for a near-term volatility event.
- Synthesis — Pro Tactical Long Volatility with Bullish Futures Lean: Pros present a nuanced, multi-layered positioning today that blends a mildly bullish futures stance with an aggressive volatility expansion bet in options. Their futures net improvement to +35,647 (driven by -2,108 short covering) signals a reducing short conviction in directional terms, while simultaneously their options book — with net long calls of +67,612 and net long puts of +119,751 — describes a long straddle or delta-neutral volatility long strategy. This is internally coherent: Pros are saying 'we don't know which direction breaks, but we believe a move is coming, and we are reducing our futures short so we are not caught on the wrong side.' The Avg Vol tags across all options legs confirm this is deliberate strategy construction, not reactive noise. The rising Short PCR (1.00 → 1.19) adds a wrinkle — within this volatility long, Pros are also selling some puts (likely at lower strikes) to finance the straddle, creating a net premium-reduced long volatility position. Compared to FIIs (outright synthetic short) and DIIs (long with hedge), Pros are the most tactically sophisticated participant today, positioning for event-driven movement rather than a directional bet.
- Forward: The critical trigger for Pro positioning tomorrow is whether their Call OI net (currently +67,612) continues to expand above +80,000 — if call long additions accelerate while Short PCR holds above 1.15, it would confirm Pros are pivoting more decisively bullish and their long volatility bet is resolving upward. Conversely, if their put long book (currently 1,416,784) begins to unwind sharply while futures short covering accelerates (net rising above +40,000), it would signal that Pros are collapsing their straddle in favour of a direct bullish call, which would be a strong bull trigger for Nifty above 23,500 CE resistance. Watch the Pro Short PCR reading in tomorrow's session — a further rise above 1.25 (implying even more put writing on the short side) combined with futures net improvement would be the clearest confirmation of a bullish Pro pivot.
Client Hedged Bullish — Futures Net Long with Massive Put Protection Build
- Futures net improved marginally from +241,420 to +241,719 (net change +299 contracts). The Long side fell from 297,981 to 297,064 [Long Unwinding - Avg Vol] and the Short side fell from 56,561 to 55,345 [Short Covering - Avg Vol] — both sides reduced simultaneously, with the short side reducing slightly more (-1,216) than the long side (-917), resulting in a net improvement of +299. The gross long-to-short ratio is 5.37:1 (297,064 longs vs 55,345 shorts), the highest of all participants, confirming Clients are the most structurally net-long participant in futures by a significant margin. The Avg Vol tags on both legs confirm routine position management — Clients are not panicking or aggressively adding, but their dominant net long of 241,719 contracts is the backbone of bullish futures positioning in the market today and directly contrasts with FII's net short of -290,546.
- Client Long PCR rose from 0.86 to 0.99 (+15.20%) and Short PCR rose from 1.15 to 1.27 (+9.85%). The Long PCR jump from 0.86 to 0.99 is the most significant directional shift in this metric for Clients today — they have moved from holding fewer put longs than call longs (0.86) to an almost exactly balanced 1:1 put-to-call long ratio (0.99). This represents a major defensive pivot within a single session: Clients are rapidly adding put longs relative to call longs, suggesting a growing need to hedge their massive futures long book. The Short PCR of 1.27 (up from 1.15) tells us Clients are also writing proportionally more puts than calls on the short side — a bullish income strategy where they collect put premium, betting the market will not fall through the 23,400 PE support. Together, rising Long PCR (hedging) and rising Short PCR (selling puts for income) signal a layered bullish hedge: long the market in futures, buying puts for protection, and selling puts at lower strikes to fund the hedge.
- Call OI net contracted from +233,015 to +182,627 (net change -50,388 contracts). Long calls surged from 3,604,780 to 3,801,153 [Long Buildup - Avg Vol] but short calls surged even more from 3,371,765 to 3,618,526 [Short Buildup - Avg Vol] — net call OI declined because short call additions (+246,761) outpaced long call additions (+196,373). Put OI net worsened from -796,597 to -827,741 (net change -31,144 contracts): put longs surged from 3,094,248 to 3,759,123 [Long Buildup - Avg Vol] while put shorts surged even more from 3,890,845 to 4,586,864 [Short Buildup - Avg Vol]. The architecture is complex: net short calls (-182,627 net ... wait — net call = +182,627, net put = -827,741). Clients are net long calls (+182,627) and net short puts (-827,741) — this is a synthetic long architecture: long calls express upside participation while net short puts (writing put options) generate income and express a view that the market will not fall below key support at 23,400. This is the classic retail/HNI strategy of a bull who is writing puts at support to earn premium.
- Synthesis — Client Synthetic Long with Protective Overlay: Clients present the most bullish futures stance in the market with a net of +241,719 contracts and a 5.37:1 long-to-short ratio, which is a structurally dominant long position. Their options architecture — net long calls (+182,627) and net short puts (-827,741) — forms a synthetic long position that doubles down on the bullish futures bet through options: call longs provide leveraged upside participation while put writing at support generates income and implicitly bets on the 23,400 level holding. However, the sharp rise in Long PCR from 0.86 to 0.99 reveals that Clients are simultaneously buying puts at an accelerating rate — a divergence within their own book where the net short put position is growing (from put writing) but so is the protective put long book (from hedging). This means Clients are running a ratio put book: writing more puts than they own, which is profitable if the market stays flat or rises but becomes dangerous if Nifty breaks below 23,400 PE support and put writers are forced to cover. This is the highest-risk participant architecture today — the very high put short book of 4,586,864 contracts is an extreme exposure that would become a forced buying event on the way down. Compared to FIIs (synthetic short) and Clients (synthetic long), these two are in direct opposition, with the PCR of 1.17 and expanding put OI suggesting the Clients' put-writing strategy is currently winning.
- Forward: The critical risk trigger for Clients tomorrow is whether Nifty holds above 23,400 (PE support / max put OI strike) — their net short put book of -827,741 contracts is entirely dependent on the market not breaking this level decisively. If Nifty breaches 23,400 on significant volume and FII futures net deteriorates beyond -295,000, Client put shorts will face accelerating mark-to-market losses and forced short-covering, creating a gamma-driven cascade that could amplify the downside move sharply. Conversely, if Nifty holds above 23,400 and Client Long PCR stabilises below 1.00 (indicating the defensive put buying has peaked), their put writing income strategy will be confirmed profitable and Nifty should find strong dip-buying support from Client short-put delta-hedging activity near 23,400–23,415. Watch Client put short OI tomorrow — any reduction below 4,400,000 would signal defensive unwinding and loss-taking, which is a red flag for near-term support.
Bull vs Bear Strength by Participant
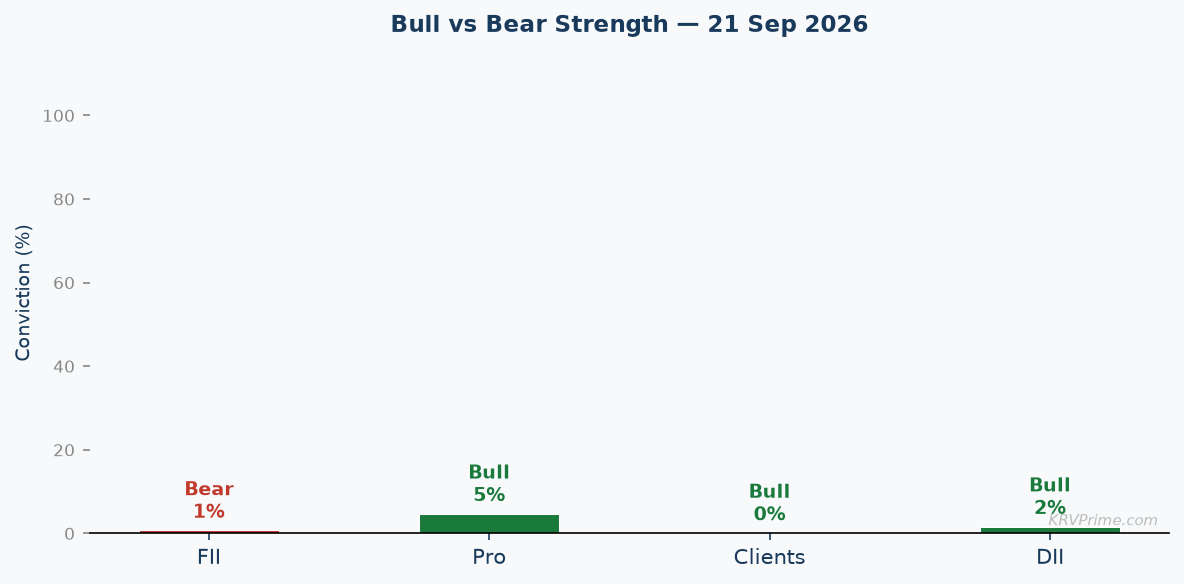
FII Strongly Bearish 82% ▼▼ | Clients Hedged Bullish 65% ▲ | Pro Cautiously Bullish / Long Volatility 55% ▲▶ | DII Defensively Bullish / Hedged 58% ▲▼ |
Conclusion — Market Outlook for Tomorrow (22 Sep 2026)
The structural picture for tomorrow is one of direct and high-stakes opposition between FII shorts and Client longs. FII futures net of -290,546 (7.09:1 short-to-long ratio) with a complementary synthetic short options architecture (net short calls -256,356, net long puts +638,430) represents the most formidable institutional bearish position in today's data. Against this, Client futures net of +241,719 (5.37:1 long-to-short ratio) backed by a synthetic long options book (net long calls +182,627, net short puts -827,741) provides the dominant counterweight. DIIs are adding to their put long book at high conviction (+12,275 net puts, High Vol tag) while maintaining their futures long of +13,180 — a defensive-bullish posture that adds to support at 23,400 without adding directional momentum. Pros are covering futures shorts (net +35,647) and building a long volatility position (long straddle architecture), signalling that sophisticated intermediaries expect a near-term move but are not yet committing to a direction. The overall balance of these four forces produces a range-bound, tension-filled market where the key battleground is the 23,400–23,500 band.
The overall PCR surging from 1.04 to 1.17 (+11.94%) is a significant one-session jump driven almost entirely by the put OI explosion of +1,992,505 contracts (+17.66%). A PCR of 1.17 in absolute terms is moderately bullish — it signals more put protection and put writing activity than call activity, which historically supports the market by creating natural buy-on-dip demand from put writers. However, the composition of today's put build matters: FIIs added 94,585 put longs (bearish directional bets), DIIs added 12,075 put longs at High Vol (defensive hedging), and Clients added 664,875 put longs (protective overlay on their long book) — meaning the PCR is rising partly due to genuine bearish directional positioning by FIIs and partly due to defensive hedging by longs. India VIX falling to 11.25 (-1.21%) in this environment confirms that the market is not pricing in imminent panic — it is a quiet, deliberate OI-building session. The low VIX makes option premium cheap for both call writers at resistance (23,500 CE) and put buyers seeking cheap downside protection, which explains the high volume of activity without a large directional price move in Nifty (+0.29%).
The bearish thesis would be confirmed if FII futures net deteriorates beyond -295,000 contracts tomorrow while Nifty fails to hold 23,400 (PE max OI / weekly support). In that scenario, Client put shorts (4,586,864 contracts) become the source of forced covering and gamma amplification, and DII's High Vol put long book begins monetising, accelerating the downside. The bull thesis would be validated if FII Short PCR continues rising (indicating they are financing shorts with put writing rather than deepening directional conviction), Client Long PCR stabilises below 1.00, and Nifty reclaims and holds above 23,500 CE resistance — at which point the call writers at 23,500 would face covering pressure that could propel a momentum rally toward 24,000 (monthly CE resistance).
Scenario 1 — Bull case:
If FII futures net improves from -290,546 toward -280,000 (short covering of ~10,000+ contracts) and the overall PCR sustains above 1.20 with put long additions continuing to outpace put short additions, the market's downside support floor at 23,400 would hold firmly. Client put writing at 23,400 creates natural delta-hedging demand on any dip, and a VIX drop below 11.00 would add confidence. A decisive Nifty close above 23,500 (CE max OI resistance — weekly) backed by FII net short reduction would trigger call writer short-covering and could propel a move toward 24,000 (monthly CE resistance).
Scenario 2 — Bear case:
If FII futures net deepens beyond -295,000 and FII put longs accelerate above 1,420,000 contracts while Nifty trades below 23,400 (PE max OI support — weekly), Client net short puts (4,586,864 contracts) begin to bleed and forced short-covering in puts amplifies the downside move through negative gamma. A VIX spike above 12.50 in this scenario would confirm fear re-entry and accelerate the sell-off. Monthly PE support at 23,000 becomes the next meaningful OI-based floor if 23,400 gives way, with BankNifty's 56,000 PE support providing the corresponding index floor.
Key Resistance 23,500 (Nifty Weekly CE max OI resistance) — FIIs are net short calls with 980,904 short call contracts and Clients have added 246,761 short calls in today's session alone. The density of call writing at this strike from multiple large participants creates a formidable supply ceiling; any attempt to breach 23,500 will require FII short covering of material size. | Key Support 23,400 (Nifty Weekly PE max OI support) — This level is anchored by DII High Vol put longs (69,560 net contracts), FII aggressive put longs (1,393,670 gross), and Client put writing (4,586,864 gross short puts) that creates forced delta-hedge buying on any dip to this strike. The 56,000 BankNifty monthly PE and 74,500 Sensex weekly/monthly PE are the corresponding support anchors across indices. | Trigger to Watch Overall PCR crossing 1.25 on the upside or falling below 1.10 on the downside — A PCR rise above 1.25 would confirm put support is structurally accumulating and the bearish FII narrative is being absorbed, bullish for holding 23,400. A PCR drop below 1.10 combined with VIX rising above 12.00 would signal that put longs are being monetised (put holders selling), removing the floor and validating the FII short thesis for a move below 23,400. |