
Market Participants Analysis dated 22.09.2026
KRVPrime — Daily Market Outlook
Key Market Signals — Data: 22 Sep 2026
NIFTY 50 23,329.00 ▼ -85.30 (-0.36%) | BANK NIFTY 56,215.55 ▼ -255.10 (-0.45%) | SENSEX 74,529.08 ▼ -329.91 (-0.44%) |
OVERALL PCR 0.93 ▼ -0.24 (-20.51%) PCR collapsed from 1.17 to 0.93 — below 1.00 signals put writers retreating faster than call writers; bearish short-term sentiment. | INDIA VIX 11.00 ▼ -0.25 (-2.22%) VIX eased to 11.00 — complacency zone; low fear but collapse in PCR warns against reading this as bullish confirmation. | TOTAL OI CHANGE 46,564,660 ▼ -8,990,030 (-16.18%) Massive OI unwind of over 8.99 million contracts — consistent with a weekly/monthly expiry roll-off and structural position liquidation. |
FUTURES OI 904,798 ▲ +5,102 (+0.57%) Futures OI marginally higher — participants are holding or slightly building futures exposure even as options collapse. | CALL OI CHANGE 7,979,071 ▼ -3,404,685 (-29.91%) Call OI shed nearly 3.4 million contracts — massive expiry-driven call unwind; resistance zones losing structural support. | PUT OI CHANGE 7,454,888 ▼ -5,823,386 (-43.86%) Put OI fell by 43.86% — far steeper than call unwind; PCR collapse is put-led, stripping away support floor beneath the market. |
Participant-wise Key Points
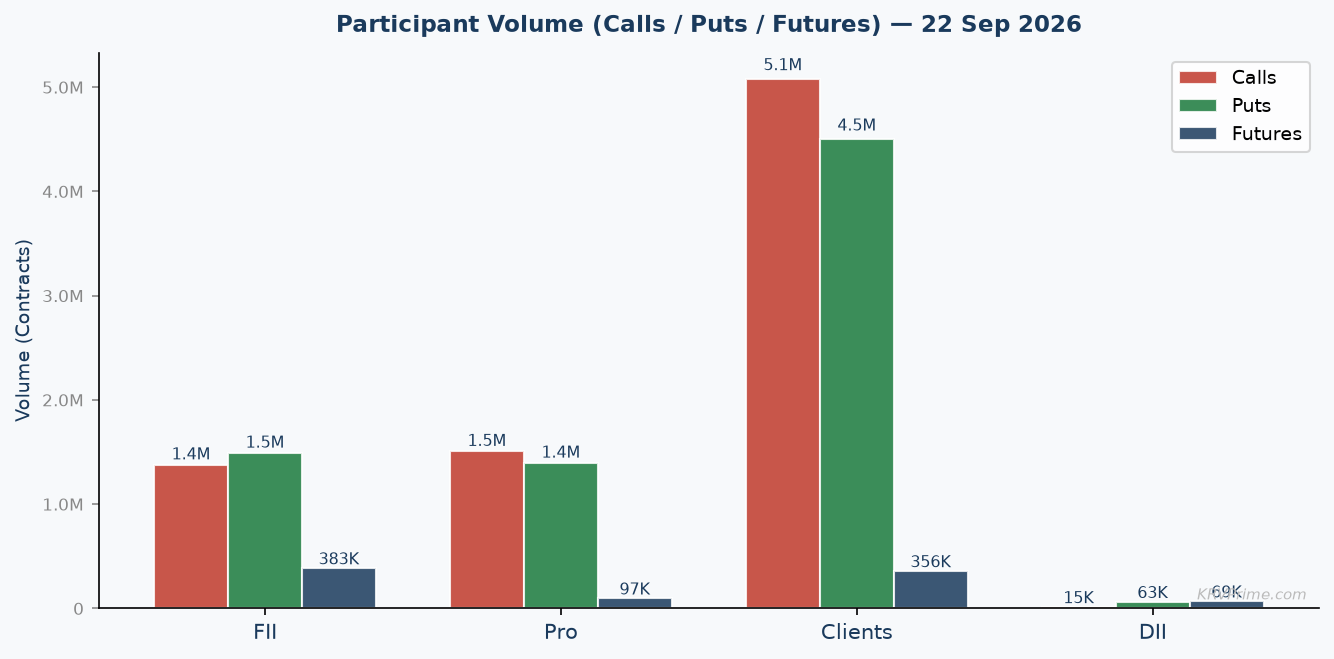
FII Bearish — Deepening Futures Short with Post-Expiry Options Reset
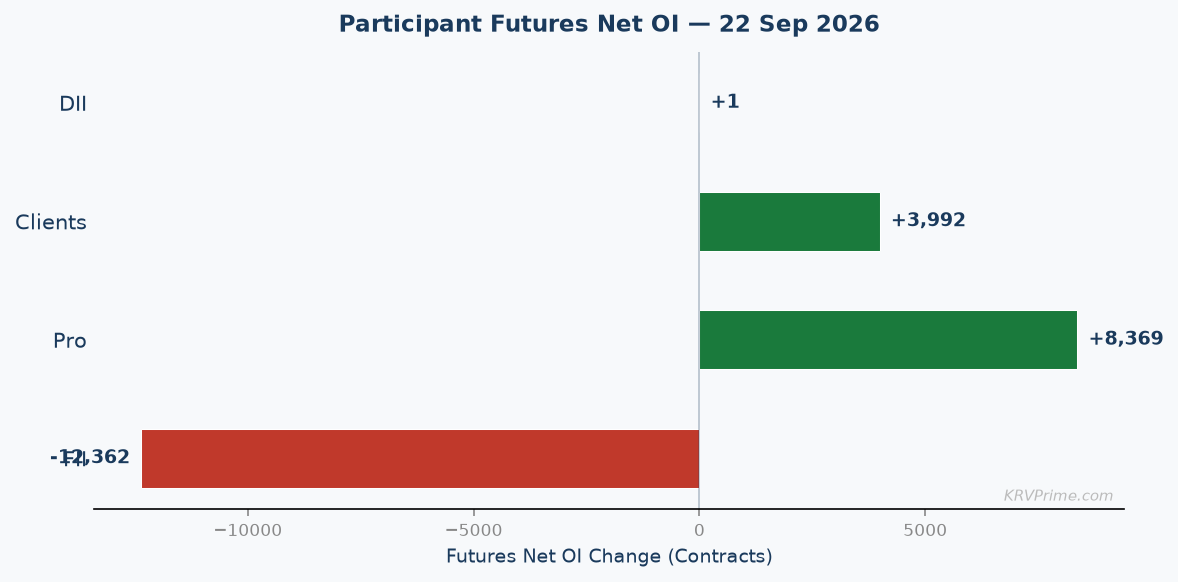
- Futures net deteriorated from -290,546 to -302,908 (net change -12,362 contracts). On the long side, FIIs shed 7,474 contracts from 47,731 to 40,257 tagged [Long Unwinding - High Vol], confirming this was a deliberate, high-conviction reduction — not a passive roll-off. On the short side, they added 4,888 contracts from 338,277 to 343,165 tagged [Short Buildup - High Vol], again a purposeful addition under elevated volume. The resulting gross short-to-long ratio stands at a commanding 8.52:1 (343,165 shorts versus 40,257 longs) — this is unambiguously a directional short position, not a hedge. The simultaneous long unwinding and short buildup, both tagged High Vol, represent a dual-leg bearish acceleration: FIIs are not merely holding their short book, they are actively expanding it on this expiry day, signalling conviction that the market has further downside ahead.
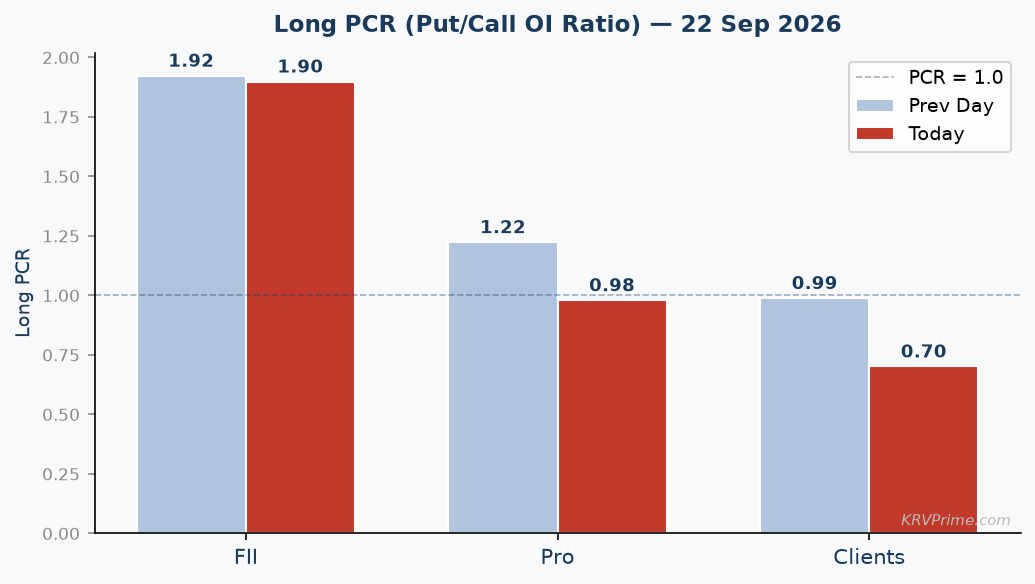
- FII Long PCR declined from 1.92 to 1.90 (chg -1.28%) and Short PCR collapsed from 0.77 to 0.52 (chg -32.59%). The Long PCR of 1.90 remains deeply defensive — FIIs continue to hold nearly twice as many put longs as call longs on the buy side, confirming a persistent hedging or outright bearish options posture. The dramatic Short PCR collapse from 0.77 to 0.52 is the most significant PCR signal today: FIIs were already writing more calls than puts on the short side (Short PCR < 1), and this ratio has now compressed further, meaning they covered far more short puts than short calls in today's expiry unwind. In absolute terms, the short put cover of 330,570 contracts dwarfed the short call cover of 162,664 contracts, reaffirming that FIIs were using short puts as a premium income layer rather than as a bullish bet — and they have now largely exited those. The dominant signal is that FIIs retain their bearish architecture (net short futures, Long PCR near 2.00, net short calls) even after the expiry cleanup.
- Call OI net stands at -256,374 (Long 561,866 [Long Unwinding - High Vol], Short 818,240 [Short Covering - High Vol], net change -18 — essentially flat). Put OI net stands at +642,226 (Long 1,066,896 [Long Unwinding - High Vol], Short 424,670 [Short Covering - High Vol], net change +3,796). Despite the massive gross unwind on both sides driven by expiry, the net positions barely moved: call net changed by only -18 contracts and put net improved by +3,796. The architecture remains a net short calls + net long puts combination — a classic synthetic short or protective put collar overlay on top of the futures short book. This triple-layer confirmation (futures short + short calls + long puts) across all three instruments is the most internally consistent bearish positioning visible across all participants today.
- Synthesis — FII Post-Expiry Bearish Consolidation: FIIs have used today's expiry event not to lighten their bearish load but to consolidate and in fact deepen it. The futures net worsened by -12,362 to reach -302,908, the gross short ratio expanded to 8.52:1, and the options architecture remains a textbook synthetic short: net short 256,374 calls, net long 642,226 puts, and a Long PCR of 1.90. The Short PCR collapse from 0.77 to 0.52 tells us the short-put income leg of their strategy has been largely retired post-expiry, leaving behind a cleaner, more directionally bearish options book. All four data legs — futures direction, futures volume tag, Long PCR level, and options net — are aligned bearish with no internal contradictions. Compared to the prior session, FIIs have accelerated their short thesis rather than reversing or holding steady, which is the strongest possible signal of continued bearish conviction heading into the next expiry cycle.
- Forward: Watch FII futures net in tomorrow's session — if it deteriorates further below -310,000 contracts, it will confirm a fresh short-buildup cycle has begun post-expiry. Conversely, if FII futures net improves toward -290,000 (i.e., covers approximately 13,000 shorts), that would mark the first meaningful signal of thesis reconsideration and could trigger a sharp short-covering rally. The critical options-side watch is whether FIIs rebuild their short-put book (Short PCR recovering back above 0.65) in the new expiry cycle — if they do, it signals a range-bound view; if they stay at 0.52 or lower, the directional short thesis remains dominant and Nifty's 23,300 weekly PE support will face a serious test.
DII Cautiously Neutral — Futures Unchanged, Options Mildly Repositioned
- Futures net is virtually unchanged at +13,181 (prev 13,180 → today 13,181, net change +1 contract). The long side added a negligible 1 contract (prev 40,954 → today 40,955) tagged [Long Buildup - Low Vol], and the short side was completely flat at 27,774 contracts tagged [Short Flat - Low Vol]. The Low Vol tags on both sides are critical — they confirm this is not an active decision day for DIIs in the futures market; they are in a holding pattern with a gross long-to-short ratio of 1.47:1 (40,955 longs versus 27,774 shorts). This is a mild net long bias in futures, consistent with DIIs' typical role as long-biased institutional buyers, but the near-zero activity today contrasts sharply with the aggressive repositioning seen across FIIs, Pros, and Clients — suggesting DIIs were largely observers during today's expiry unwind. In direct contrast to FIIs who were aggressively adding to shorts (+4,888 short contracts), DIIs sat completely still, which implies their medium-term bullish view on the underlying has not been shaken by today's session.
- DII PCR data is not available from the provided dataset — no Long PCR or Short PCR figures are disclosed for DIIs. However, we can infer directional intent from their options OI changes: DIIs added 3,902 call longs (Long PCR-equivalent behaviour on the call side) while simultaneously covering 615 short calls and unwinding 6,371 put longs. The put unwind is notable — a reduction of 6,371 long puts tagged [Long Unwinding - Low Vol] suggests DIIs are gently reducing their downside hedge rather than adding to it, which is a mildly bullish signal (they feel less urgency to protect against a sharp fall). The call buildup on the long side — +3,902 contracts tagged [Long Buildup - High Vol] — is the sharpest directional signal from DIIs today: buying call options under High Vol conviction while reducing put protection implies a quiet, incremental upside bias.
- Call OI net stands at +10,634 (Long 12,609 [Long Buildup - High Vol], Short 1,975 [Short Covering - High Vol], net change +4,517). Put OI net stands at +63,189 (Long 63,189 [Long Unwinding - Low Vol], Short 0 [Short Flat - Low Vol], net change -6,371). The call net has expanded sharply by +4,517 — DIIs are now net long 10,634 calls with the long side tagged High Vol, which is one of the few unambiguously directional bullish signals in today's data. The put net remains large at +63,189 but has contracted by -6,371 as DIIs trim existing protective put positions. The resulting architecture is net long calls + net long puts — a classic long straddle or strangle posture — but the asymmetry is telling: the put book is very large (63,189) versus the call book (10,634), meaning the dominant hedging orientation is still protective, not aggressively bullish. This architecture is consistent with DIIs holding a large equity book (hence the big put hedge) while selectively adding call exposure to participate in potential upside.
- Synthesis — DII Quiet Accumulation with Selective Upside Positioning: DIIs present the picture of a cautious, long-biased institutional player who did not participate in today's expiry volatility but made one deliberate move: adding 3,902 call longs under High Vol conviction. Their futures net is essentially flat at +13,181, their short side is completely immobile, and their put unwind was Low Vol — none of these scream urgency. The High Vol tag on the call long buildup stands out precisely because everything else was quiet — it suggests a targeted, considered decision to add upside exposure rather than a panic response to expiry. Compared to FIIs (who are sitting at -302,908 futures net and systematically short), DIIs are on the opposite side with a modest +13,181 futures net long and a growing call long book — this FII vs DII divergence is a classic institutional tug-of-war signal, with DIIs betting on stabilisation or mild recovery while FIIs press bearish. The risk to this thesis is the large put unwind: if DIIs are genuinely comfortable with the outlook, the continued reduction of 63,189 long puts in coming sessions would be a strong confirming signal.
- Forward: The key DII watch for tomorrow is whether they continue adding call longs (specifically if the call Long OI grows above 15,000 contracts) while the put OI continues to decline below 60,000 — that combination would confirm a genuine tilt toward net bullish options positioning. If instead DIIs begin rebuilding put longs and the call buildup stalls, the safer interpretation is that today's call addition was a one-off expiry-cycle initiation rather than a trend signal. Given that DII futures are locked at +13,181 with no movement, a break of that stasis — either long addition above 42,000 or short buildup above 29,000 — would be the first structural signal that DIIs are shifting their medium-term market view.
Pro Transitioning Bullish — Aggressive Futures Long Buildup Against Options Expiry Cleanup
- Futures net improved sharply from +35,647 to +44,016 (net change +8,369 contracts). On the long side, Pros added 6,237 contracts (prev 64,099 → today 70,336) tagged [Long Buildup - High Vol] — a deliberate, high-conviction expansion of their long book. On the short side, they covered 2,132 contracts (prev 28,452 → today 26,320) tagged [Short Covering - Avg Vol] — a routine but directionally consistent reduction of their short exposure. The resulting gross long-to-short ratio stands at 2.67:1 (70,336 longs versus 26,320 shorts), making Pros the most aggressively net-long futures participant today by far. The High Vol tag on the long buildup is especially significant on an expiry day — Pros are not simply rolling; they are initiating fresh directional length with conviction, which is counter-narrative to the bearish tilt being expressed by FIIs simultaneously. This FII vs Pro divergence in futures is the single most important inter-participant tension in today's data.
- Pro Long PCR declined sharply from 1.22 to 0.98 (chg -19.94%) and Short PCR collapsed from 1.19 to 0.88 (chg -26.31%). The Long PCR falling below 1.00 (from 1.22 to 0.98) is a decisive pivot — Pros have flipped from holding more put longs than call longs to now holding more call longs than put longs for the first time. This is a structural shift in options orientation from defensive/hedged to directionally bullish on the long side. The Short PCR collapsing from 1.19 to 0.88 means Pros were previously writing more puts than calls (Short PCR > 1 = income/bullish short-put strategy) and have now pivoted to writing more calls than puts — consistent with the massive call-writing expiry cleanup visible in their options OI. Together, both PCR moves reinforce the same message: Pros are rotating from a balanced/defensive options posture to one that is increasingly bullish on the long futures side, while their options book resets post-expiry.
- Call OI net turned negative at -60,180 (Long 723,801 [Long Unwinding - High Vol], Short 783,981 [Short Covering - High Vol], net change -127,792). Put OI net collapsed to +21,640 (Long 709,217 [Long Unwinding - High Vol], Short 687,577 [Short Covering - High Vol], net change -98,111). Both the call net and put net contracted massively — the call net swung from +67,612 to -60,180 (a shift of -127,792) and the put net crashed from +119,751 to +21,640 (a shift of -98,111). The High Vol tags on all four legs confirm this was not passive expiry decay but active, deliberate repositioning. The resulting architecture — marginally net short calls (-60,180) and marginally net long puts (+21,640) — is a mildly bearish options overlay, but critically, these are post-expiry remnants at much smaller scale than yesterday. The more important signal is the futures book (+44,016 net long) which is increasingly the dominant directional expression for Pros, with the options book having been largely neutralised through today's expiry cleanup.
- Synthesis — Pro Expiry Reset with Emerging Bullish Futures Bias: Pros present the most interesting strategic pivot in today's data. They have used the expiry event to aggressively clean up a large, balanced options book (shedding over 433,669 call longs, 305,877 call shorts, 707,567 put longs, and 609,456 put shorts in a massive bilateral unwind) while simultaneously building their futures long position to +44,016 net — the strongest net long futures reading among all four participants. The Long PCR crossing below 1.00 (0.98) and Short PCR falling to 0.88 confirm that Pros are entering the new expiry cycle with a lighter, more directionally bullish footprint. Compared to FIIs, who are at -302,908 futures net, Pros are almost perfectly counter-positioned — Pros long at +44,016 vs FIIs short at -302,908 — making this a clean institutional arbitrage tug-of-war that will define market direction in the coming sessions. The High Vol tag on Pro futures long buildup is the key confirmation that this is not accidental or a hedge: Pros are expressing a view that the market is oversold or range-bound near current levels.
- Forward: The critical threshold to watch for Pros is whether their futures net continues to expand above +50,000 in tomorrow's session — if it does, it will confirm that today's buildup was the beginning of a fresh long campaign and not merely expiry positioning. Simultaneously, watch whether the Long PCR (currently at 0.98) falls further toward 0.80 in the new expiry cycle, as that would confirm Pros are adding call longs while shedding remaining put longs — a clean rotation to outright bullish. The key risk to the Pro bullish thesis is a reversal of today's futures long buildup: if futures net retreats below +35,000 (back toward pre-today levels) while FIIs continue adding shorts, the tug-of-war resolves in FIIs' favour and Pros' bullish positioning would be wrong-footed.
Client Cautiously Bullish — Futures Long with Massive Options Expiry Unwind
- Futures net improved from +241,719 to +245,711 (net change +3,992 contracts). On the long side, Clients added 3,787 contracts (prev 297,064 → today 300,851) tagged [Long Buildup - High Vol] — a deliberate if modest addition to an already very large long book. On the short side, they covered a marginal 205 contracts (prev 55,345 → today 55,140) tagged [Short Covering - Avg Vol] — routine and not a strong directional signal. The gross long-to-short ratio stands at 5.46:1 (300,851 longs versus 55,140 shorts) — Clients remain the largest absolute holders of futures long positions among all participants, and with 300,851 contracts long, they dwarf every other participant's futures book. The High Vol tag on the long buildup confirms this was a deliberate decision to add length on an expiry day, not passive rollover — and aligns Clients directionally with Pros (both building futures longs) against FIIs (building futures shorts). The Client vs FII divergence in futures is particularly sharp: Clients at +245,711 versus FIIs at -302,908 means these two participants are the dominant structural opponents defining tomorrow's directional tug-of-war.
- Client Long PCR collapsed from 0.99 to 0.70 (chg -29.05%) and Short PCR declined from 1.27 to 1.10 (chg -13.51%). The Long PCR falling from 0.99 to 0.70 means Clients have shifted from a near-parity put/call long book to now holding 43% more call longs than put longs — a meaningful rotation toward upside participation on the long options side. This is directionally consistent with their futures long buildup and suggests retail/client money is positioning for a recovery or continuation of recent levels rather than a sharp decline. The Short PCR declining from 1.27 to 1.10 is noteworthy — Clients were writing more puts than calls on the short side (Short PCR > 1), and while this ratio has declined, it remains above 1.00, meaning Clients continue to write more short puts than short calls. A Short PCR above 1.00 on the short side reflects either a premium-income strategy or a belief that the downside is limited — both of which are mildly bullish orientations. Together, both PCR readings reinforce a bullish-leaning options posture that is consistent with the futures long bias.
- Call OI net expanded significantly to +305,921 (Long 2,691,260 [Long Unwinding - High Vol], Short 2,385,339 [Short Covering - High Vol], net change +123,294). Put OI net improved to -727,055 (Long 1,888,142 [Long Unwinding - High Vol], Short 2,615,197 [Short Covering - High Vol], net change +100,686). Despite both sides unwinding massively in absolute terms (call longs shed 1,109,893, call shorts shed 1,233,187, put longs shed 1,870,981, put shorts shed 1,971,667), the NET positions improved for Clients on both legs — call net expanded by +123,294 and put net improved by +100,686 (becoming less negative). The resulting architecture is net long calls (+305,921) combined with net short puts (-727,055) — a synthetic long or risk reversal construction: Clients are buying calls and selling puts simultaneously, which is a classic aggressive bullish options expression. This synthetic long in options, layered on top of a massive +245,711 futures long, makes Clients the most comprehensively bullish participant in today's market across all three instruments.
- Synthesis — Client Synthetic Long Architecture Confirms Bullish Conviction: Clients present the most unambiguous bullish positioning in today's data, with a three-layer confirmation: futures net long at +245,711, net long calls at +305,921, and net short puts at -727,055 (improving by +100,686). The synthetic long architecture (long calls + short puts) is an aggressive, cost-efficient way to express a bullish view — it is not a hedge; it is a directional bet. The Long PCR at 0.70 and Short PCR at 1.10 both reinforce this bullish orientation from the PCR side. The High Vol tags across all major Client options legs, despite the massive absolute unwind, confirm these are deliberate repositioning decisions under expiry rather than passive decay. Compared to FIIs at -302,908 futures net, Clients at +245,711 are the dominant counter-force — and crucially, both participants are adding to their directional positions today (FIIs adding shorts, Clients adding longs), making tomorrow's session a high-stakes resolution of this institutional standoff. Clients' bullish thesis is supported by Pros (also futures net long at +44,016) but faces the headwind of FIIs' deeply entrenched short book and the overall PCR collapse to 0.93.
- Forward: The key Client threshold to monitor is whether their call net OI continues to expand above +350,000 in the new expiry cycle — that would confirm fresh call buying is being added rather than existing positions being rolled. Critically, the short-put book (currently -727,055 net) must hold its ground: if Clients begin aggressively covering short puts (put net improving sharply above -600,000), it signals they are losing confidence in the downside containment thesis and the synthetic long is unwinding. The 23,300 Nifty weekly PE support is the anchor for the Client short-put strategy — a sustained breach of that level would put pressure on Client short puts and could trigger a forced unwind that accelerates any downturn.
Bull vs Bear Strength by Participant
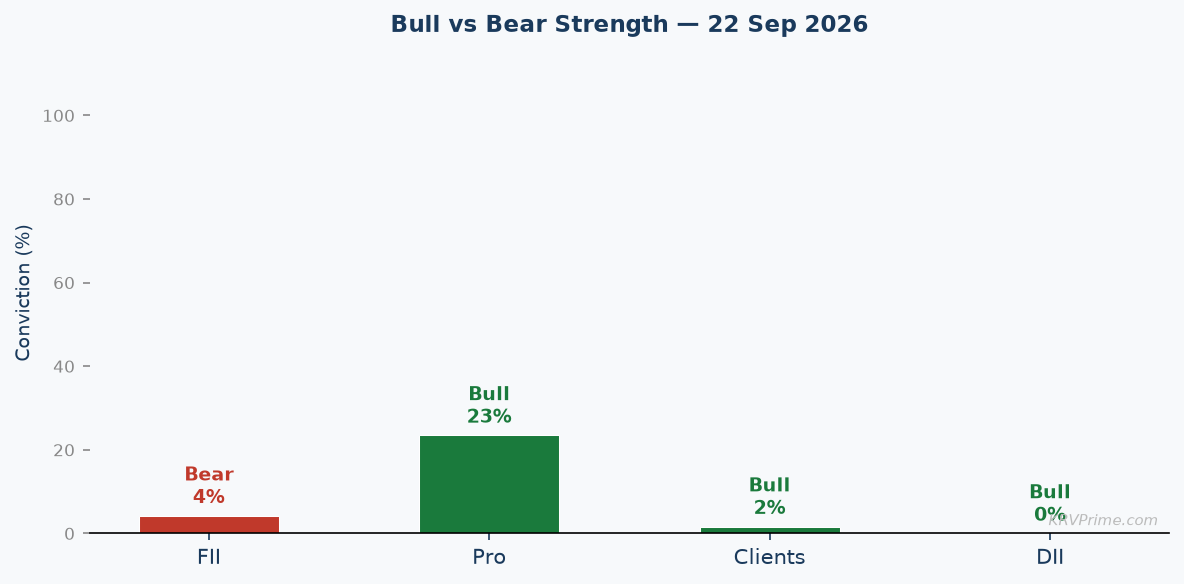
FII Strongly Bearish 85% ▼▼ | Clients Bullish / Synthetic Long 70% ▲▲ | Pro Emerging Bullish 65% ▲ | DII Cautiously Neutral 45% ▶ |
Conclusion — Market Outlook for Tomorrow (23 Sep 2026)
The structural picture emerging from today's expiry-day data is one of a deeply bifurcated market: FIIs have accelerated their directional short position to a net of -302,908 futures contracts (gross short-to-long ratio of 8.52:1) while simultaneously maintaining a synthetic short in options (net short 256,374 calls, net long 642,226 puts), representing the heaviest and most internally consistent bearish institutional position in today's data. On the opposing side, Clients hold a massive +245,711 futures net long and have constructed a synthetic long in options (net long 305,921 calls, net short puts of -727,055), while Pros have added +8,369 to their futures long to reach +44,016 net. DIIs are essentially neutral in futures at +13,181 but have quietly added 3,902 call longs under High Vol conviction. The bulls (Clients + Pros) and bears (FIIs) are both adding to their positions on the same expiry day, making this an increasingly high-conviction confrontation that must resolve directionally in the next 1–3 sessions.
The overall PCR has collapsed from 1.17 to 0.93 — a -19.90% single-session drop — driven primarily by put OI falling 43.86% versus call OI falling 29.91%. This put-led collapse is structurally bearish: it means the floor of put support beneath the market has been significantly thinned, reducing the buffer against downside moves. India VIX at 11.00 (down -2.22%) sits in a complacency zone — the market is not pricing fear, but the PCR collapse is not being accompanied by upside price follow-through (Nifty closed down -0.36%). This divergence between low VIX and collapsing PCR is a warning signal: complacency can unwind rapidly if FII short pressure intensifies. The weekly PE support at 23,300 (OI-based) is the critical structural floor — it has absorbed today's selling but with significantly less put OI defending it post-expiry. The weekly CE resistance at 23,350 sits only 21 points above the close of 23,329, creating an extremely compressed range that demands a directional resolution.
The bearish thesis reverses if FII futures net shows meaningful improvement (covering toward -280,000) alongside a PCR recovery above 1.00 in the new expiry cycle — those two signals together would confirm the FII short book is being unwound and Clients/Pros are winning the tug-of-war. Conversely, the bull case collapses if Nifty sustains a break below the 23,300 weekly PE support, which would put pressure on Client short-put positions and potentially trigger a cascade of forced unwinds across the synthetic long architecture. VIX rising above 12.50 from the current 11.00 would be the volatility confirmation of a breakdown scenario.
Scenario 1 — Bull case:
If FII futures net improves from -302,908 toward -285,000 (short covering of approximately 18,000 contracts) in tomorrow's session, and the overall PCR recovers back above 1.00, the Client + Pro synthetic long architecture will be validated. A VIX sustained below 10.75 alongside call OI rebuilding above 8,500,000 in the new expiry cycle would confirm range stabilisation and set up a move toward the monthly CE resistance at 24,000 for Nifty and 58,000 for BankNifty.
Scenario 2 — Bear case:
If FII futures net deteriorates further below -315,000 (fresh short addition of over 12,000 contracts) and the overall PCR fails to recover above 0.93, the put floor collapse will leave Nifty vulnerable at the weekly PE support of 23,300. A break and close below 23,300 on Nifty would trigger Client short-put unwinds (put net currently -727,055), potentially accelerating a move toward the monthly PE support at 23,000. VIX rising above 12.50 in this scenario would confirm the fear transition from complacency to defensive positioning.
Key Resistance — Nifty Weekly 23,350 (Weekly CE max OI resistance) — FIIs are the dominant call writers on the short side (818,240 short calls), actively capping upside at this level. Any close above 23,350 with FII call short OI declining would signal capitulation by the largest bear in the market. | Key Support — Nifty Weekly 23,300 (Weekly PE max OI support) — Clients hold the largest put long book (1,888,142 long puts) and short put book (2,615,197 short puts) anchored near this level. A sustained breach below 23,300 would force Client short-put unwinds and remove the most significant structural floor in the current expiry cycle. | Trigger to Watch Overall PCR crossing back above 1.00 — the collapse from 1.17 to 0.93 is the single most bearish structural signal today. A recovery above 1.00 (requiring put OI to stabilise while call OI is contained) would indicate the expiry unwind is complete and fresh put buying is returning, restoring the structural floor. If PCR remains below 0.93 with FII futures net below -310,000, the bear case is strongly confirmed. |