
Market Participants Analysis dated 23.09.2026
KRVPrime — Daily Market Outlook
Key Market Signals — Data: 23 Sep 2026
NIFTY 50 23,446.80 ▲ +117.80 (+0.50%) | BANK NIFTY 56,548.90 ▲ +333.35 (+0.59%) | SENSEX 74,828.25 ▲ +299.17 (+0.40%) |
OVERALL PCR 1.01 ▲ +0.08 (+8.37%) PCR crossing above 1.00 signals put OI now exceeds call OI — marginally bullish sentiment shift. | INDIA VIX 10.35 ▼ -0.65 (-5.93%) VIX in ultra-low complacency zone; sharp drop signals option sellers dominating and low near-term fear. | TOTAL OI CHANGE 49,923,980 ▲ +3,359,320 (+7.21%) Large OI expansion on an up-day suggests fresh money entering — broadly constructive but warrants directional confirmation. |
FUTURES OI 895,126 ▼ -9,672 (-1.07%) Futures OI contracting on an up-day may indicate short covering rather than fresh long build — mildly cautionary. | CALL OI CHANGE 9,260,288 ▲ +1,281,217 (+16.06%) Significant call OI expansion signals strong resistance writing and hedging activity above current levels. | PUT OI CHANGE 9,375,975 ▲ +1,921,087 (+25.77%) Put OI expanding faster than call OI drives PCR above 1.00 — protective hedging and bullish put selling both contributing. |
Participant-wise Key Points
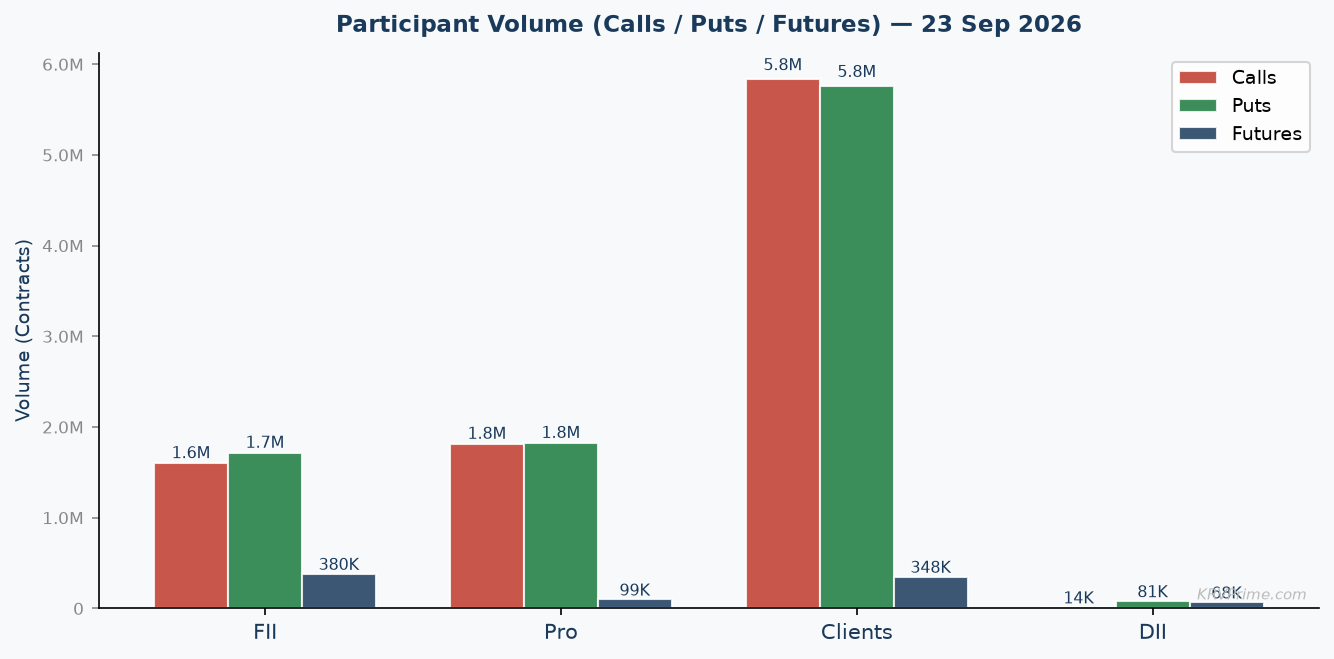
FII Cautiously Bearish — Reducing Futures Short, Aggressively Repositioning Options
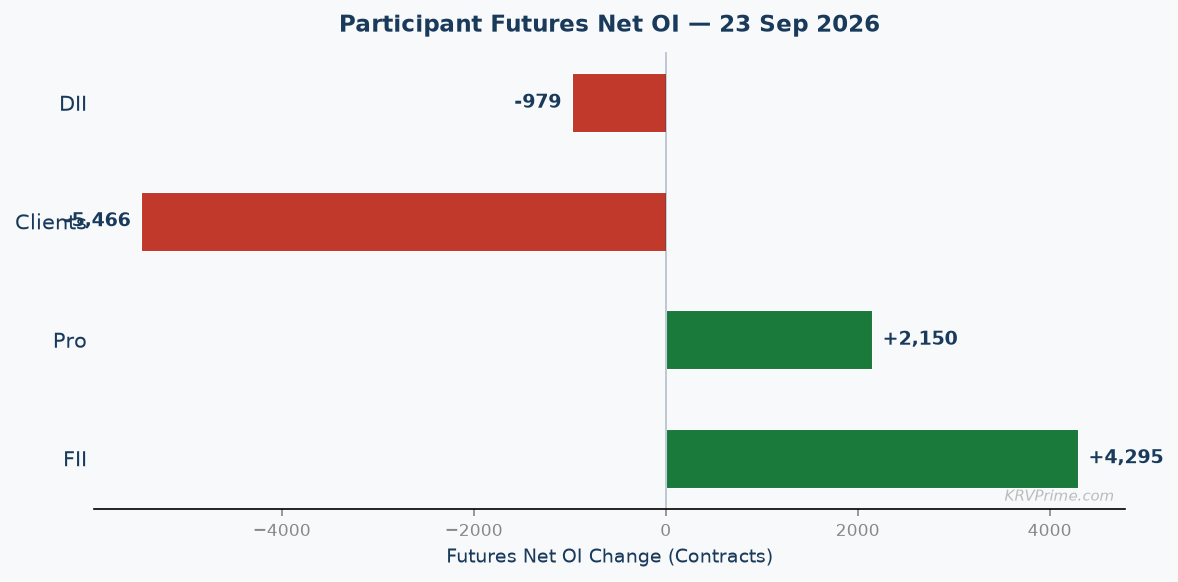
- Futures net improved from -302,908 to -298,613 (net change +4,295 contracts). The Long side added 354 contracts (prev 40,257 → today 40,611, +0.88%) tagged [Long Buildup - High Vol], while the Short side shed 3,941 contracts (prev 343,165 → today 339,224, -1.15%) tagged [Short Covering - Avg Vol]. The High Vol tag on the long buildup confirms this was a deliberate, conviction-backed addition of fresh longs rather than a mechanical roll, while the Avg Vol tag on short covering indicates routine rather than panic-driven cover. The gross short-to-long ratio stands at 339,224 : 40,611 = 8.35:1, which despite the marginal improvement from yesterday's implied ratio remains an overwhelming directional short — FIIs are not capitulating; they are trimming modestly at the edges while the core bear book stays fully intact. The +4,295 net improvement on a +0.50% up-day in Nifty is consistent with forced partial short-covering rather than a genuine thesis reversal.
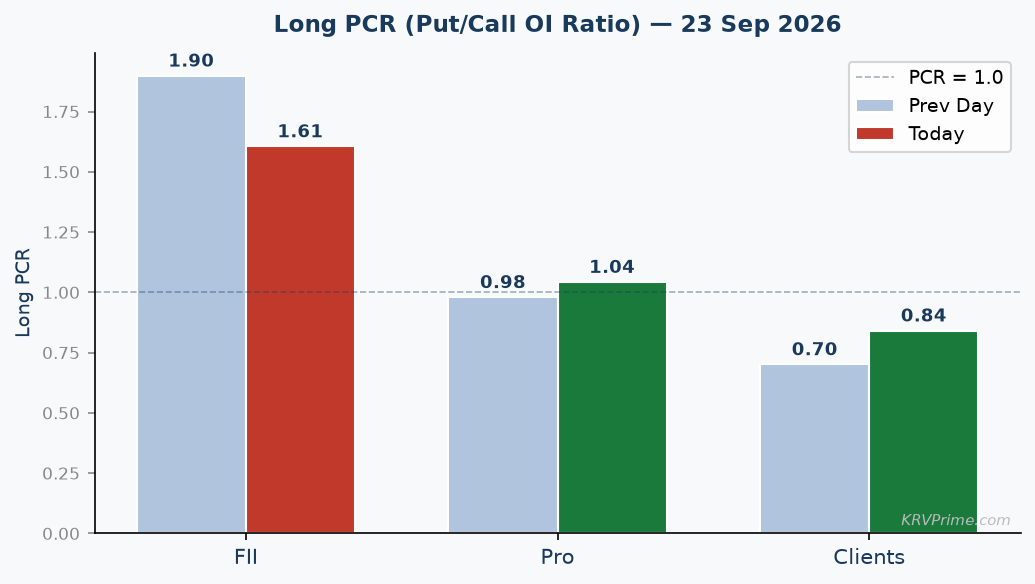
- Long PCR fell sharply from 1.90 to 1.61 (-15.44%) and Short PCR rose sharply from 0.52 to 0.65 (+25.05%). A Long PCR of 1.61 means FIIs still hold 61% more put longs than call longs — this remains a deeply defensive, bearish-leaning options posture, though the steep 15.44% drop in Long PCR signals they are reducing their put-long edge relative to call longs, possibly monetising profitable put positions or rolling strikes closer to market. The Short PCR rising from 0.52 to 0.65 (+25.05%) tells us FIIs are now writing proportionally more puts relative to calls on the short side — this is a crucial shift: rising Short PCR means they are beginning to sell puts (a mildly bullish or range-bound income strategy) in greater volume, which partially contradicts the dominant futures short. The net interpretation is nuanced — FIIs are lightening their directional put hedge while simultaneously adding put-writing income, suggesting they believe the immediate downside risk is diminishing even as they maintain the core short futures book.
- Call OI net stands at -188,797 (Long: 705,480 [Long Buildup - Low Vol]; Short: 894,277 [Short Buildup - Low Vol]), with both legs expanding — call longs added 143,614 contracts (+25.56%) and call shorts added 76,037 contracts (+9.29%). Put OI net stands at +552,364 (Long: 1,132,740 [Long Buildup - Low Vol]; Short: 580,376 [Short Buildup - Low Vol]), with put longs adding 65,844 contracts (+6.17%) and put shorts adding a massive 155,706 contracts (+36.67%). The Low Vol tags on all four legs indicate these are lower-conviction repositioning moves rather than high-conviction institutional deployments. The architecture — net short calls (-188,797) paired with net long puts (+552,364) — continues to represent a bearish collar / synthetic short structure, but the aggressive put-short addition of 155,706 contracts (+36.67%) signals FIIs are financing their hedge by selling downside puts, transitioning toward a ratio put spread or put-financed bear collar where catastrophic downside is being partially capped in exchange for premium income.
- Synthesis — FII Adaptive Bearish Collar with Put-Financing Overlay: FIIs present a sophisticated multi-leg repositioning story today. Their futures net of -298,613 confirms the core directional short remains dominant at an 8.35:1 short-to-long ratio, yet the +4,295 net improvement — driven by both fresh longs [High Vol] and short covering [Avg Vol] — tells us this is a live, dynamically managed position rather than a static carry. The options architecture has shifted meaningfully: the aggressive +155,706 put short addition (+36.67%) alongside a more modest +65,844 put long addition (+6.17%) signals FIIs are transitioning from a pure protective put stance toward a put ratio spread or sold-put financed hedge, collecting premium on lower strikes while maintaining upper-strike put longs for tail protection. The falling Long PCR (1.90→1.61) and rising Short PCR (0.52→0.65) both corroborate this transition — they are reducing their net put-long dominance while writing more puts, a move consistent with a view that the market will not crash sharply from current levels but remains unlikely to break significantly higher. Compared to the previous session, FIIs have accelerated the put-writing activity while barely touching the core futures short, which creates an interesting internal tension: the futures book says 'down', the accelerating put-short book says 'not too far down or too fast'. The Low Vol tags on all options legs introduce a note of caution — these are not high-conviction deployments, suggesting some of this repositioning is algorithmic or roll-driven ahead of a near-term expiry.
- Forward: Watch whether FII futures net crosses above -290,000 contracts in tomorrow's data — a move to that level would represent approximately 8,600 additional contracts of net improvement and would signal an accelerating thesis shift from 'manage the short' to 'reduce the short meaningfully'. If FII futures net fails to improve further and remains anchored near -298,613, the core bearish structure stays in force and any intraday rallies toward the CE OI resistance at Nifty 24,000 should be sold. The secondary watch is whether FII Short PCR continues rising above 0.65 — if it crosses 0.70+, that would confirm put-writing has become the dominant options theme and would be a moderate bullish signal for near-term range stability.
DII Defensively Bullish — Reducing Futures Longs, Aggressively Building Put Longs
- Futures net declined from +13,181 to +12,202 (net change -979 contracts). The Long side shed 979 contracts (prev 40,955 → today 39,976, -2.39%) tagged [Long Unwinding - High Vol], while the Short side held flat at 27,774 contracts (chg 0, +0.00%) tagged [Short Flat - High Vol]. The High Vol tag on the long unwinding is the critical data point here — this was not a passive reduction but a deliberate, high-conviction exit from index futures longs, suggesting DIIs are intentionally trimming their directional bullish futures exposure on a day when Nifty closed up +0.50%. The Short Flat at High Vol is equally telling: DIIs had every opportunity to cover their 27,774 shorts on the up-move but chose not to — implying they are content to carry a natural hedge against their equity portfolio or they expect some near-term weakness. The gross long-to-short ratio stands at 39,976 : 27,774 = 1.44:1, a modest net long but declining — DIIs are slowly de-risking their futures book.
- DII options data does not include a PCR breakdown in the provided data set, so Long PCR and Short PCR values are not available for this participant. However, from the Put OI net which stands at +81,486 (with zero short puts), it is clear that DIIs are operating purely as put buyers with no put-writing activity whatsoever — their entire put book is a protective long, with a Long PCR directional proxy derived from put long of 81,486 versus call long of 12,644, implying a put-to-call long ratio of approximately 6.45:1. This is an extreme protective posture, far exceeding even FII defensive positioning, and signals DIIs view the downside risk as materially elevated relative to their call exposure. The absence of short puts (zero) and the massive put long build today reinforces that DIIs are not in an income-writing mode — they are buying pure protection at scale.
- Call OI net stands at +10,922 (Long: 12,644 [Long Buildup - Low Vol]; Short: 1,722 [Short Covering - Low Vol]), with call longs nearly flat (+35 contracts, +0.28%) and call shorts reduced by 253 contracts (-12.81%). Put OI net stands at +81,486 (Long: 81,486 [Long Buildup - High Vol]; Short: 0 [Short Flat - Low Vol]), with put longs adding a substantial 18,297 contracts (+28.96%) at High Vol confirmation. The combination of a near-flat call position and a massive, High Vol put long addition creates a protective put / portfolio insurance architecture — DIIs are not expressing a directional view through calls at all; they are buying index puts at scale to insulate against a market decline. The High Vol tag on the put long buildup is the session's most important DII signal: this is a deliberate, high-conviction defensive move, executed on a day when VIX fell to 10.35, making puts cheaper — DIIs are using the VIX compression to load up on downside protection at relatively low cost.
- Synthesis — DII Portfolio Insurance at Low VIX — Stealth Defensive Pivot: DIIs present a coherent and internally consistent defensive repositioning story today. They are simultaneously reducing futures longs (-979 contracts, [Long Unwinding - High Vol]), holding shorts unchanged ([Short Flat - High Vol]), and aggressively adding put longs (+18,297 contracts, +28.96%, [Long Buildup - High Vol]) while carrying zero put shorts — a textbook portfolio insurance / protective put strategy at scale. The decision to buy 18,297 put contracts at High Vol on a day when VIX sits at a compressed 10.35 is strategically astute: falling VIX lowers option premiums, making protective puts cheaper, and DIIs appear to be capitalising on this window to hedge their large underlying equity book. The contrast with FII positioning is notable: FIIs are building put shorts (income strategy, implying limited downside expected) while DIIs are building put longs (insurance strategy, implying meaningful downside feared) — these two institutional heavyweights are taking opposite sides of the put market, which creates a natural tension and suggests differing downside conviction levels. Compared to the previous session, DIIs have accelerated their defensive posture significantly — the +28.96% single-day put long increase at High Vol is not a gradual hedge; it is a deliberate uplift in protection that suggests either an internal risk committee decision or foreknowledge of near-term event risk. The net futures long of +12,202 (declining) combined with the large put long book effectively creates a delta-hedged equity-long with downside floor — a classic institutional pre-event or pre-volatility positioning.
- Forward: The key watch for DIIs tomorrow is whether put long OI continues to expand above 81,486 contracts — any further addition at High Vol would confirm this is a multi-day defensive accumulation campaign, not a one-off hedge. If DII put longs hold flat or decline tomorrow, it may signal the hedge purchase is complete and the downside fear premium has been expressed. Additionally, watch the futures net: if it falls below 10,000 contracts (from today's 12,202), it would indicate DIIs are further trimming index futures exposure, strengthening the read that they expect at minimum a period of consolidation or weakness near current Nifty levels around 23,446.80.
Pro Balanced Bullish — Expanding Both Sides, Net Long Futures and Net Long Puts
- Futures net improved from +44,016 to +46,166 (net change +2,150 contracts). The Long side added 2,396 contracts (prev 70,336 → today 72,732, +3.41%) tagged [Long Buildup - Low Vol], while the Short side added 246 contracts (prev 26,320 → today 26,566, +0.93%) tagged [Short Buildup - Low Vol]. The Low Vol tags on both legs signal these are lower-conviction, possibly opportunistic additions rather than high-conviction directional statements — Pros are gently expanding both sides of their futures book, with the net drift mildly bullish at +2,150 contracts. The gross long-to-short ratio stands at 72,732 : 26,566 = 2.74:1, a meaningful net long that has improved from yesterday's 70,336 : 26,320 = 2.67:1, indicating a very gradual accumulation of bullish futures bias. However, the Low Vol context tempers excitement — Pros are not aggressively positioning; they are making modest incremental additions consistent with their role as market-maker and arbitrageur rather than outright directional punter.
- Long PCR rose from 0.98 to 1.04 (+6.45%) and Short PCR rose from 0.88 to 0.97 (+10.36%). A Long PCR of 1.04 means Pros now hold 4% more put longs than call longs — this has crossed above 1.00 for the first time, signalling a marginal shift toward net put dominance on the long side, consistent with hedging the growing futures long book. The Short PCR rising from 0.88 to 0.97 (+10.36%) tells us Pros are writing puts and calls in increasingly balanced proportion on the short side, with puts slightly less dominant — a Short PCR approaching 1.00 indicates near-parity between call and put writing, consistent with a strangle-selling or range-trading strategy. Both PCR movements — Long PCR crossing 1.00 and Short PCR approaching 1.00 — together tell us Pros are operating a delta-neutral to mildly long book, collecting premium from both sides while hedging the futures long via put purchases. This is broadly consistent with their role as systematic option market makers.
- Call OI net stands at -10,935 (Long: 899,939 [Long Buildup - Low Vol]; Short: 910,874 [Short Buildup - Low Vol]), with call longs adding 176,138 contracts (+24.34%) and call shorts adding 126,893 contracts (+16.19%) — the net is barely negative at -10,935, effectively near-neutral. Put OI net stands at +57,109 (Long: 938,739 [Long Buildup - Low Vol]; Short: 881,630 [Short Buildup - Low Vol]), with put longs adding a massive 229,522 contracts (+32.36%) and put shorts adding 194,053 contracts (+28.22%). The architecture — near-neutral calls combined with net long puts (+57,109) — creates a mildly bullish risk reversal tilt where the put long book slightly exceeds put short book, providing some directional hedge while the massive gross positions on both sides reflect the market-making and strangle-management role. The Low Vol tags on all four options legs confirm these are not high-conviction trades; they are systematic, balanced additions consistent with Pros rolling and expanding their book ahead of expiry.
- Synthesis — Pro Systematic Expansion: Delta-Long Futures Hedged with Near-Neutral Options Book: Pros tell a consistent story of moderate, systematic expansion across all four legs — futures, calls, and puts, both long and short sides. Their futures net of +46,166 (up from +44,016) is backed by a 2.74:1 long-to-short gross ratio, the most net-bullish futures book among all participants after Clients. The options architecture is a classic market-maker's balanced book — near-zero call net (-10,935) and a modest put net (+57,109) driven by the fact that put long additions (+229,522) slightly outpaced put short additions (+194,053). The rising Long PCR (0.98→1.04) and rising Short PCR (0.88→0.97) both confirm Pros are systematically adding to both put longs and put shorts in roughly proportional fashion, consistent with delta-neutral management. Compared to the previous session, Pros have accelerated the absolute size of their options book significantly — the combined put additions of +229,522 longs and +194,053 shorts in a single day represent a major gamma expansion, suggesting Pros are gearing up for a high-activity expiry environment. The internal consistency across all legs and the Low Vol tags suggest this is algorithmic, expiry-driven book management rather than a sudden macro call.
- Forward: The key watch for Pros tomorrow is whether their futures net sustains above +46,000 contracts — if it continues to build toward +50,000, it would signal an accelerating directional tilt rather than passive market-making. The secondary signal is whether their options book Long PCR continues to push above 1.04 — a further rise toward 1.10+ would indicate Pros are adding protective put longs in excess of their call longs, shifting from neutral market-making toward a directional hedge that aligns with the DII protective put thesis. If instead Long PCR retreats below 1.00 tomorrow, it would signal Pros are reverting to pure strangle-neutral mode and any directional read from their book should be discarded.
Client Hedged Bearish — Unwinding Futures Longs, Massively Expanding Put Positions
- Futures net declined from +245,711 to +240,245 (net change -5,466 contracts). The Long side shed 6,607 contracts (prev 300,851 → today 294,244, -2.20%) tagged [Long Unwinding - Avg Vol], while the Short side shed 1,141 contracts (prev 55,140 → today 53,999, -2.07%) tagged [Short Covering - Avg Vol]. The Avg Vol tags on both long unwinding and short covering indicate this is routine profit-taking and de-risking on both sides rather than a sharp institutional decision — retail participants are gradually reducing gross exposure in both directions. The gross long-to-short ratio remains strongly net long at 294,244 : 53,999 = 5.45:1, making Clients the most net-long futures participant in absolute contract terms. However, the direction of change — declining net from +245,711 to +240,245 — signals Clients are slowly reducing this net long dominance, possibly distributing into the Nifty +0.50% up-move rather than adding to longs at current levels. This is a mild warning sign: the largest futures bull book is trimming, not adding.
- Long PCR rose from 0.70 to 0.84 (+19.95%) and Short PCR rose from 1.10 to 1.14 (+4.21%). A Long PCR of 0.84 means Clients hold 16% more call longs than put longs on the long side — structurally they remain net call-dominant, consistent with a retail bullish bias in long options. However, the dramatic +19.95% single-day rise in Long PCR from 0.70 to 0.84 is the sharpest PCR shift of any participant today, signalling that Clients added put longs at a far greater pace than call longs today — put protection is being added aggressively even as the overall call-dominant posture is maintained. The Short PCR rising from 1.10 to 1.14 (+4.21%) tells us Clients continue to write more calls than puts on the short side — a mildly capping strategy, consistent with retail covered-call writing or speculative call selling above current market levels. The key divergence today is the Long PCR surge (+19.95%) while Short PCR only nudged up (+4.21%) — Clients are adding put longs much faster than they are writing puts, signalling net growing concern about downside even as the futures book stays net long.
- Call OI net declined to +188,810 (Long: 3,012,081 [Long Buildup - Low Vol]; Short: 2,823,271 [Short Buildup - Low Vol]), with call longs adding 320,821 contracts (+11.92%) and call shorts adding an even larger 437,932 contracts (+18.36%) — the net call position narrowed from +305,921 to +188,810, a reduction of 117,111 contracts, as call short additions outpaced call long additions. Put OI net improved to -690,960 (Long: 2,535,022 [Long Buildup - Low Vol]; Short: 3,225,982 [Short Buildup - Low Vol]), with put longs adding 646,880 contracts (+34.26%) and put shorts adding 610,785 contracts (+23.36%) — the net put position improved from -727,055 to -690,960, a net improvement of +36,095 contracts, driven by put long additions outpacing put short additions. The overall architecture — net long calls (+188,810) combined with net short puts (-690,960) — represents a synthetic long / bullish risk reversal posture, but today's flows show Clients are actively narrowing the call net and narrowing the put-short net simultaneously, transitioning toward a more hedged stance. The Low Vol tags on all four legs suggest these are retail-driven, distributed, lower-conviction additions rather than single concentrated institutional trades.
- Synthesis — Client Gradual Transition: From Synthetic Long Toward Hedged Directional: Clients remain the largest futures net long (+240,245 contracts) and maintain a synthetic long options architecture (net long calls +188,810, net short puts -690,960), yet today's session shows a clear directional transition underway. The futures long unwinding (-5,466 net, [Long Unwinding - Avg Vol]) combined with accelerating put long additions (+646,880 contracts, the single largest put addition of any participant in absolute terms) tells a story of a participant group that is bullish but increasingly nervous — they are keeping their long exposure but buying insurance in large quantities. The Long PCR surge of +19.95% (0.70→0.84) is the standout PCR move of the day across all participants and confirms the put-protection theme is accelerating rapidly among retail Clients. Compared to FIIs who are selling puts (income strategy), Clients are buying puts at record pace — this creates a direct FII-vs-Client put market dynamic where FIIs are supplying put premium and Clients are consuming it, with Pros acting as intermediaries. The internal tension in the Client book — declining futures net long, surging put long additions, but still net short puts overall — suggests a participant group that has not yet committed to a directional bear view but is hedging increasingly aggressively against the possibility. The Low Vol tags across all legs moderate the conviction read, consistent with a distributed retail hedging wave rather than a concentrated institutional decision.
- Forward: Watch whether Client futures net breaks below 235,000 contracts tomorrow — a further decline from today's 240,245 would confirm that retail participants are genuinely reducing their long index exposure rather than managing routine daily fluctuations. The secondary trigger is the Client Long PCR: if it continues rising above 0.90 (from today's 0.84), the put-protection campaign is accelerating and could eventually flip Clients from net call-dominant to net put-dominant on the long side — a psychologically significant shift that historically precedes broader market defensiveness. If instead Client futures net stabilises or recovers above 245,000 tomorrow while Long PCR retreats below 0.80, the defensive hedging read should be moderated and the residual bullish synthetic long architecture would remain the dominant theme.
Bull vs Bear Strength by Participant
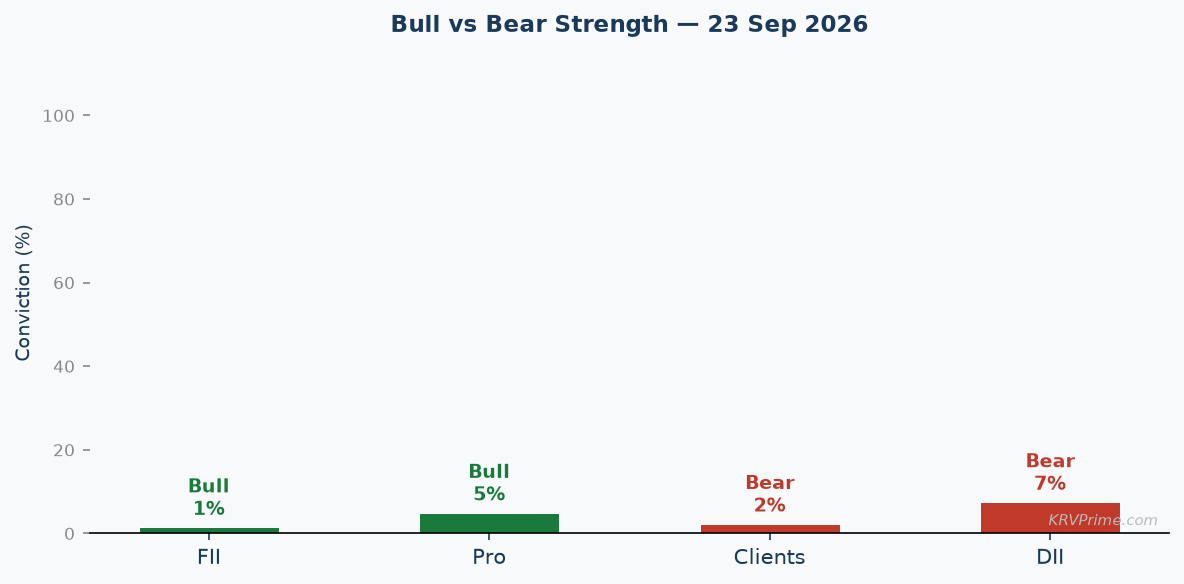
FII Cautiously Bearish 70% ▼ | DII Defensively Positioned 60% ▼ | Pro Neutral / Balanced 50% ▶ | Client Bullish but Hedging 55% ▲ |
Conclusion — Market Outlook for Tomorrow (23 Sep 2026)
The collective participant positioning on 23 Sep 2026 paints a picture of a market in cautious equilibrium — indices closed higher (Nifty +0.50% at 23,446.80, BankNifty +0.59% at 56,548.90, Sensex +0.40% at 74,828.25) but institutional money is not celebrating the move. FIIs maintain an overwhelming 8.35:1 futures short-to-long ratio at a net of -298,613 contracts, making only a token reduction of 4,295 contracts despite the up-move — this refusal to cover at scale on a bullish day is a notable contrarian signal. DIIs delivered the sharpest defensive move of the day, adding 18,297 put long contracts at High Vol (+28.96%) — the highest-conviction single action in today's data — while simultaneously unwinding 979 futures longs at High Vol, signalling institutional risk management committees are actively reducing index exposure and buying downside insurance. Pros are systematically expanding their book in market-maker fashion, broadly neutral, while Clients — despite holding the largest futures net long at +240,245 — are showing early signs of anxiety through the sharpest Long PCR surge of any participant today (+19.95%, from 0.70 to 0.84) and the largest single-session put long addition in absolute terms (+646,880 contracts). The net structural read: bulls hold the spot market but institutions are hedging aggressively, creating a classic capped upside, cushioned downside environment.
The Overall PCR rising from 0.93 to 1.01 (+8.37%) — crossing the psychologically significant 1.00 threshold — is mildly bullish on its own, as put OI now exceeds call OI system-wide. However, this PCR expansion is driven partly by FII put-writing (income strategy, implying limited downside) and partly by DII and Client put buying (insurance strategy, implying feared downside) — these are structurally opposing reasons for the same PCR move, which means the bullish signal from PCR>1.00 must be treated cautiously. India VIX collapsing from 11.00 to 10.35 (-5.93%) into the ultra-low complacency zone further complicates the read: cheap VIX is making DII and Client put purchases cost-effective, potentially inflating put OI mechanically rather than reflecting a sharp bearish shift. The total OI expansion of +3,359,320 contracts (+7.21%) on an up-day is broadly supportive, but the simultaneous Futures OI contraction of -9,672 (-1.07%) confirms that the OI build is concentrated entirely in options — specifically call OI +16.06% and put OI +25.77% — indicating participants are expressing views through options rather than building fresh futures longs. The net signal: the market is in a low-volatility, hedged holding pattern with institutional players unwilling to commit directionally into futures.
The bull case requires FII futures net to improve meaningfully above -290,000 contracts alongside a further PCR push toward 1.10+ and VIX staying compressed below 10.50 — that combination would signal short-covering is becoming sustained and the put-writing community (FIIs) is growing more comfortable with range stability, allowing Nifty to test the CE OI resistance wall at 24,000. The bear case materialises if DII put buying accelerates further (Long Buildup above 90,000 contracts), Client Long PCR crosses 0.90 (retail panic-hedging), and FII futures net deteriorates back toward -310,000 — a scenario where all three non-Pro participants are defensively positioned simultaneously, which would expose the PE OI support at 23,000 in Nifty as the floor. At current levels, the balance of institutional evidence favours range-bound consolidation between 23,000 and 24,000 in Nifty, with the upside capped by FII call writing and the downside cushioned by DII and Client put longs.
Scenario 1 — Bull case:
If FII futures net improves above -290,000 contracts (implying sustained short-covering beyond today's token +4,295 reduction) AND the Overall PCR rises above 1.10 (signalling put OI dominance is expanding) AND India VIX remains compressed below 10.50, the short-covering momentum could carry Nifty toward the CE OI resistance at 24,000 — the call wall where FIIs and Clients have concentrated their short positions. A PCR above 1.10 combined with falling VIX would confirm sellers of downside protection (FIIs) are gaining confidence in range stability, reducing tail risk and potentially triggering a momentum chase by Client futures longs who would then re-add the 6,607 contracts unwound today.
Scenario 2 — Bear case:
If FII futures net deteriorates below -305,000 contracts (fresh short addition, reversing today's partial cover) AND DII put long OI crosses 100,000 contracts (acceleration of institutional hedging) AND the Overall PCR retreats below 0.95 (call OI overtaking put OI on a down-day), the weight of the combined institutional bear positioning would press Nifty toward the PE OI support at 23,000 where DII and Client put longs provide a structural floor. A VIX spike back above 12.00 — reversing today's -5.93% collapse — would validate the defensive hedges and potentially trigger Client futures long unwinding below 230,000 net contracts, amplifying the downside move.
Key Resistance Nifty 24,000 (CE max OI strike, both weekly and monthly) — FIIs hold 894,277 call short contracts here and Clients hold 2,823,271 call short contracts, making this the heaviest supply zone in the market. Any rally toward 24,000 faces combined institutional call-writing resistance from FIIs and retail call sellers; a sustained close above 24,000 would trigger a gamma squeeze and force significant short-covering. | Key Support Nifty 23,000 (PE max OI strike, both weekly and monthly) — DIIs hold 81,486 put long contracts at High Vol conviction and FIIs hold 1,132,740 put long contracts, creating a dense institutional put support floor. BankNifty's equivalent PE support sits at 56,000, currently well below spot at 56,548.90, providing a comfortable buffer for BankNifty bulls. Client put longs of 2,535,022 contracts further reinforce this floor as the zone where put holders would aggressively defend positions. | Trigger to Watch Overall PCR crossing and sustaining above 1.05 (from today's 1.01) is the primary confirmation trigger for the bull case — it would signal that put OI is structurally dominating call OI across the market, reducing the resistance pressure from call writers. Conversely, India VIX reclaiming 11.00 (reversing today's -5.93% drop back to yesterday's level) would be the bear-case confirmation trigger, signalling that option buyers are paying up for protection again and the institutional hedges placed by DII (+18,297 put longs at High Vol) are being validated by the market. |